The bank alert came at 9:14 on a Tuesday morning: BALANCE BELOW $5.
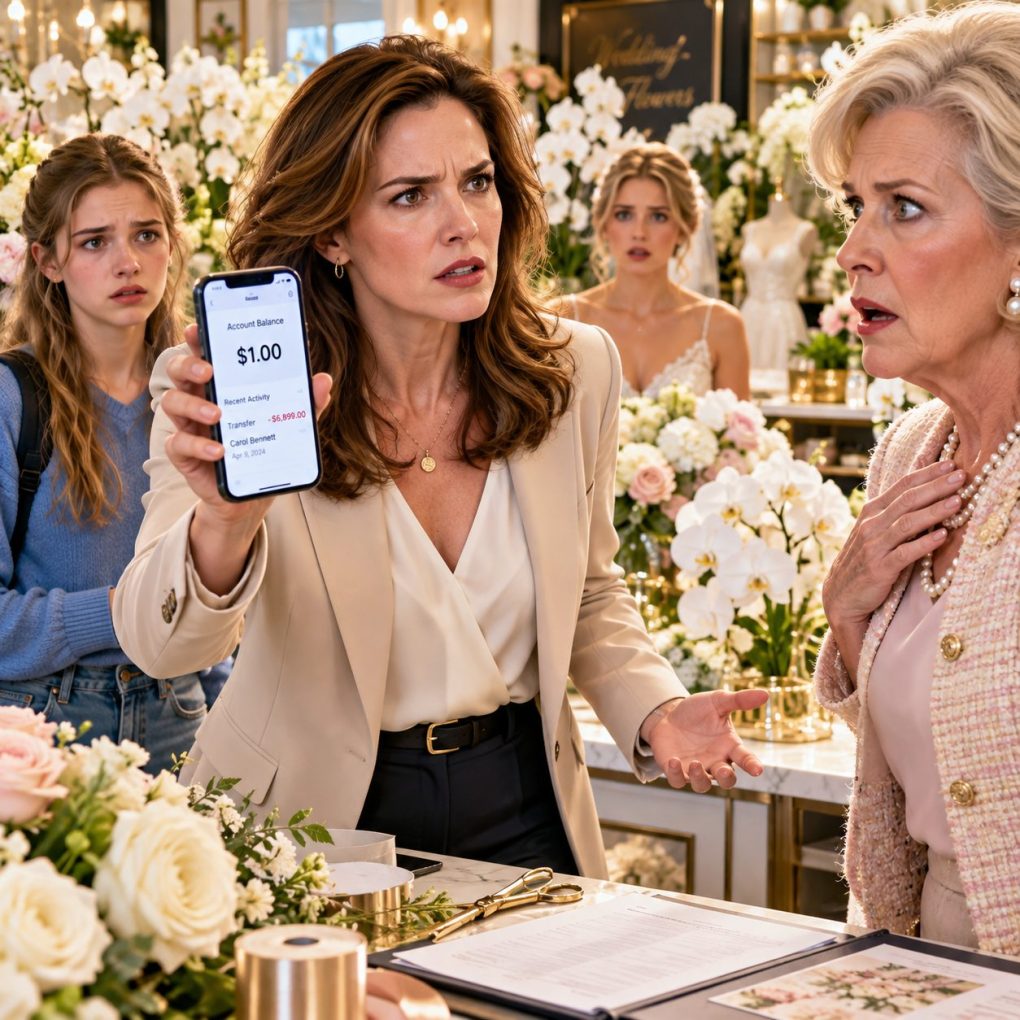
I was in our kitchen when my seventeen-year-old daughter, Emma, came downstairs holding her phone with both hands.
“Mom,” she whispered. “Where’s my money?”
Three years of dog walking. Rain, snow, summer heat, Christmas mornings. Emma had saved $6,900 for a six-week marine science internship on the North Carolina coast. The program was unpaid, and that money was supposed to cover housing, meals, transportation, and gear.
Her balance was $1.
I opened the account history.
One transfer.
$6,899.
Recipient: Carol Bennett.
My mother.
I called her immediately.
Mom answered cheerfully, with music behind her. “I’m at the florist. Can I call you later?”
I stared at the screen.
“The florist?”
“For Megan’s wedding. The centerpieces cost more than expected, but they’re gorgeous. White garden roses, orchids—”
“You took Emma’s money.”
Silence.
Then my mother sighed like I was inconveniencing her.
“Oh, that.”
Emma’s face changed.
Not anger.
Hope.
She was waiting for Grandma to say it was a mistake.
Mom didn’t.
“Megan’s wedding is in nine days,” she said. “The florist needed payment today. Emma’s internship isn’t until June.”
“It’s April.”
“Exactly. She has time.”
Emma froze.
I felt something cold settle behind my ribs.
Mom continued. “She’s young. She can earn it back. Family comes first, and Megan only gets married once.”
Emma had walked dogs before school at six in the morning. She had skipped concerts, weekend trips, new clothes. She tracked every deposit in a spreadsheet and kept a photo of sea turtles above her desk because she wanted to work in marine wildlife rehabilitation.
My mother knew all of that.
Worse, she knew exactly where the money was.
When Emma was fourteen, I had opened a youth account at my mother’s credit union. Mom was added as an adult co-owner while I was recovering from surgery.
I had forgotten her name was still attached.
She hadn’t.
“Put it back,” I said.
“I can’t. The florist has it.”
“Then use your savings.”
“I don’t have that kind of money sitting around.”
Emma finally spoke.
“You said you were proud of me.”
Mom heard her.
“Oh, sweetheart, don’t be dramatic. You have months. I’ll help after the wedding.”
Emma’s eyes filled, but she didn’t cry.
Then Mom added, “Your aunt Megan is stressed enough. Please don’t make this about you.”
Emma looked at me.
I nodded.
Mom mistook my silence for surrender.
“See?” she said. “Your mother understands.”
I pulled out the wedding budget I had managed for eight months and looked at the payments still scheduled on my credit card.
Catering.
Rentals.
Rehearsal dinner.
Almost $14,000.
“You’re right, Mom,” I said calmly. “Megan’s wedding is in nine days.”
Then I opened my banking app.
“And Emma does have time.”
Mom laughed with relief.
I moved my thumb toward the first scheduled payment.
What she didn’t know was that the $6,899 she stole had just made me look much more closely at every dollar connected to that wedding.
Something about the numbers suddenly didn’t make sense. And once I started calling the people Mom had been dealing with, I realized Emma’s missing savings weren’t the beginning of the problem. They were the first piece of something much bigger.
I didn’t cancel the wedding.
I canceled permission for anyone to charge my card until I knew what had happened.
Then I called the florist.
The manager pulled up Megan’s file and made me sit down.
The flowers had already been funded.
Megan’s future in-laws had transferred $10,000 for florals and décor six weeks earlier. The florist had received a $3,200 deposit. The remaining balance was $6,740, due that morning.
Almost exactly what Mom had taken from Emma.
“Who has been handling the account?” I asked.
“Carol Bennett.”
My mother.
I called Megan next.
She answered from work. I asked one question: “Did you know Mom took Emma’s internship money?”
Her silence lasted maybe two seconds.
Then she said, “What?”
That was enough.
I forwarded the transfer screenshot.
Megan called me back three minutes later, crying. Her fiancé’s parents had given Mom $10,000 because Mom insisted she could negotiate with vendors and keep everything organized. Megan believed that money was still sitting in the wedding account except for the deposit.
It wasn’t.
By noon, Megan and I were sitting across from a branch manager at Mom’s credit union.
The manager couldn’t discuss Mom’s private accounts, but she could discuss Emma’s.
Because Mom was still listed as a joint owner, the transfer had not triggered fraud controls. Technically, she had authority to move the money.
Emma looked sick.
Then the manager frowned.
“There’s something else you should know.”
Two weeks earlier, someone had requested a replacement debit card for Emma’s account.
Not Emma.
Not me.
Mom.
The mailing address entered on the request wasn’t Mom’s house.
It was a post office box across town.
The manager immediately restricted the account and opened an internal review. I moved Emma’s remaining dollar into a new account at my bank that afternoon.
On the drive home, Megan called again.
She had confronted Mom about the $10,000.
Mom finally admitted she had “borrowed” part of it.
“How much?” I asked.
“Almost all of it.”
For what?
Mom wouldn’t say.
Then Megan found an envelope in a drawer at our parents’ house while Dad helped her look for vendor receipts.
Inside were past-due notices.
Credit cards.
A personal loan.
And a letter warning that their home equity line was delinquent.
Mom hadn’t stolen Emma’s savings because orchids were expensive.
She had spent the wedding money somewhere else, panicked when the florist demanded its balance, and used my daughter’s account to cover the hole.
But that still wasn’t the worst part.
At 6:17 that evening, Emma checked the email connected to her internship application.
There was a message from the program coordinator.
Someone had emailed them that morning pretending to be me.
The message said Emma was withdrawing from the internship because of “a family financial emergency.”
Emma read it twice.
Then she looked at me.
“Grandma wasn’t trying to borrow my money,” she whispered.
“She was trying to make sure I wouldn’t need it back.”
I called the internship coordinator before Emma could finish crying.
I explained everything, forwarded the bank record, and told her Emma had never withdrawn.
Thankfully, the coordinator had flagged the email because it came from an address she had never seen before. Emma’s spot had not yet been offered to anyone else.
By the next morning, she was reinstated.
Then I called the florist again.
Because Mom’s final payment had been processed only hours earlier and the flowers had not been ordered, the manager agreed to void the $6,740 balance payment. The money went back to Mom’s account, which the credit union had restricted during its review.
Dad drove Mom to the branch that afternoon.
She transferred $6,899 back to Emma.
Every dollar.
Then the truth came out.
Mom had secretly accumulated more than $38,000 in credit-card and personal-loan debt after a home décor resale business she started online failed. Instead of telling Dad, she kept making minimum payments and moving money between accounts.
When Megan’s future in-laws sent $10,000 for wedding flowers and décor, Mom used most of it to cover overdue bills, convincing herself she would replace it before anyone noticed.
She couldn’t.
So when the florist’s balance came due, she raided Emma’s account.
And the fake internship withdrawal?
Mom admitted that too.
She knew Emma would need the $6,900 by June. If the internship disappeared, she believed she could repay the money slowly over the summer and no one would discover what she had done.
That was the part Emma couldn’t forgive.
Neither could I.
Megan canceled the elaborate floral plan, kept only the original deposit, and replaced the centerpieces with simple arrangements from a local grocery florist. She and her fiancé cut several other expensive extras too.
“The wedding is not worth destroying Emma over,” she told Mom.
Dad took control of the household finances, froze their joint credit cards, and hired a credit counselor. Mom sold inventory from her failed business and some jewelry to begin repaying Megan’s future in-laws.
I removed her from every account connected to Emma.
Permanently.
Nine days later, Megan still got married.
The ballroom had fewer flowers.
Nobody cared.
Emma wore a navy dress and danced until her feet hurt. Mom attended, but sat quietly near the back and left early. Emma was polite.
She did not hug her.
Three months later, I stood beside a bus at six in the morning while Emma loaded a duffel bag, rubber boots, and a battered backpack underneath.
Her internship money was untouched in her new account.
Before boarding, she turned to me.
“You know what hurt most?” she asked. “It wasn’t the money. It was realizing Grandma thought my future was the easiest thing to sacrifice.”
I nodded.
Then she smiled.
“But she was wrong.”
She spent six weeks working with injured sea turtles, collecting water samples, and coming home exhausted and happy.
That fall, she added one line to the spreadsheet where she had tracked three years of dog-walking money.
My future is not anyone else’s emergency fund.
I printed it and taped it above my desk.
Because sometimes protecting your child means making sure the people who love them learn that love does not come with withdrawal privileges.