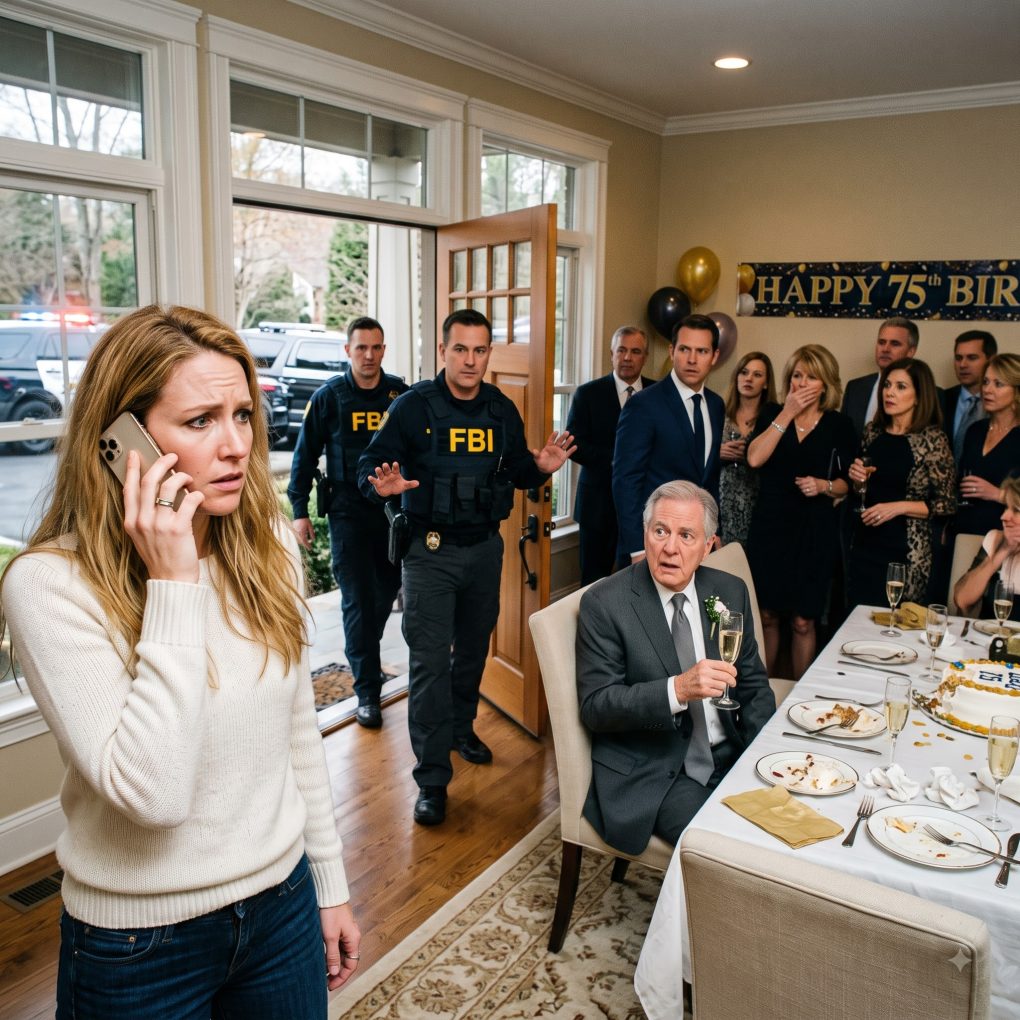
At Dad’s 75th birthday, my brother announced: “Pack your bags, loser. This house is going up for sale.” Everyone cheered—until I made one call and the FBI showed up.
“PACK YOUR BAGS, LOSER. THIS HOUSE IS GOING UP FOR SALE!”
My brother, Derek, shouted it across the dining room while holding a champagne glass over our father’s birthday cake.
Twenty-three relatives burst into laughter.
My mother actually raised her glass. “Finally! Someone is going to do something with this place.”
I stood beside the fireplace, staring at the framed photograph of my late grandmother. She had left me this house—or so I had always believed.
Dad was turning seventy-five. Instead of celebrating him, Derek had brought a real estate agent, printed property listings, and a folder of documents.
“Buyers are coming Monday,” he announced. “You have until Sunday night to get your junk out.”
I looked at my father.
“Dad, did you sign something?”
He avoided my eyes.
“Your brother knows what he’s doing, Emily. Don’t make a scene.”
That hurt more than Derek’s insults.
For three years, I had lived in the house to care for Dad after his heart surgery. I paid the property taxes, repaired the roof, and covered the insurance when his retirement checks fell short.
Derek visited twice a year—and somehow, he was now selling the house.
“You can’t sell a property you don’t own,” I said quietly.
His smile widened.
“Oh, I think you’ll find out exactly who owns it.”
He slapped a document onto the table. It carried Dad’s signature and what appeared to be a notarized authorization giving Derek control over the property.
My stomach tightened.
The signature looked real.
But the date was impossible.
Dad had been hospitalized that day, heavily sedated after emergency surgery.
I pulled out my phone.
Derek leaned closer. “Who are you calling? Your imaginary lawyer?”
“No,” I answered. “Someone who needs to see these documents.”
I stepped onto the porch and dialed a number I had saved months earlier.
“It’s Emily Carter,” I whispered. “The property documents have appeared. My brother is trying to sell the house, and I believe the signatures are fraudulent.”
The woman on the other end asked me one question.
“Has he shown anyone the original paperwork?”
“Everyone at the party.”
“Stay there. Don’t confront him. We’re contacting the agents.”
I returned inside.
Derek was already raising his glass again.
“To new beginnings!”
Then sirens sounded outside.
Three black SUVs pulled into the driveway.
The laughter died.
Men and women in dark jackets approached the front door. One displayed a badge.
“Federal agents. Nobody leave the property.”
Derek’s champagne glass slipped from his fingers and shattered.
An agent stepped into the dining room, looked directly at him, and said:
“Derek Carter, we need to speak with you about the property fraud investigation—and the missing money.”
My father suddenly stood up.
“Wait,” he gasped. “You don’t understand. My son wasn’t the only person who signed those papers…”
And when the agent placed the next document on the table, my mother began to cry.
Emily thought her brother was simply trying to steal the family home. But the federal investigation had uncovered something far more disturbing—something that could destroy the family her father had spent seventy-five years trying to protect.
And the person Emily trusted least might not be the person she should fear most.
“Ma’am, please sit down,” the agent told my mother.
She shook her head so violently that her earrings swung against her neck.
Derek backed toward the kitchen.
“I’m not answering anything without an attorney.”
“That’s your right,” the agent replied. “But you’re going to want to explain why you submitted a deed transfer containing a forged signature and why the sale proceeds were directed to an account under your control.”
Derek stared at him.
“What account?”
The agent opened a folder.
“An account ending in 4821.”
My brother’s face lost its color.
I knew those numbers.
They belonged to the account Dad had used to receive payments from a small commercial property he inherited years ago. He had told us that the rental income was meant to cover his medical expenses and maintain the family home.
Derek had supposedly been helping him manage it.
“Dad,” I said, turning toward him. “How much money is missing?”
Dad sank into his chair.
“Almost four hundred thousand dollars.”
The room went silent.
My mother covered her mouth.
Derek immediately pointed at her.
“She told me to move it!”
Mom recoiled. “You said it was temporary! You said the investment would pay everything back!”
The agent raised his hand.
“Both of you will have an opportunity to explain your involvement.”
I felt as if the floor had shifted beneath me.
For years, my mother had told relatives that I was selfish for refusing to help Derek with his business. She had called me ungrateful whenever I questioned why Dad’s accounts seemed to be running low.
Now I understood why they had wanted me out of the house so urgently.
If Derek sold it, the proceeds could cover the money he had taken—or conceal where it had gone.
But the agent wasn’t finished.
“Ms. Carter, you contacted our office several months ago regarding suspicious financial activity. Is that correct?”
I nodded.
I had reported unexplained withdrawals after finding bank statements in Dad’s desk. I hadn’t known whether a crime had occurred. I simply wanted someone qualified to investigate.
The agent turned to Derek.
“Your sister provided information that helped establish a timeline. But we already had evidence from the financial institutions involved.”
Derek glared at me.
“You set me up!”
“No,” I said. “I asked why Dad’s money was disappearing. You decided to make the evidence disappear with it.”
Then another agent entered carrying a thin envelope.
“There’s one more issue,” he said. “The property’s ownership records don’t match the documents submitted for the sale.”
He placed an official-looking copy in front of Dad.
Dad read the first page. His hands began to tremble.
“This is impossible.”
“What is it?” I asked.
He looked at me with wet eyes.
“Your grandmother changed her estate plan before she died.”
Derek gave a nervous laugh. “She left everything to Dad. Everybody knows that.”
The agent shook his head.
“Not according to the recorded trust documents.”
He turned the page toward me.
My name appeared beneath the heading identifying the property’s beneficiary.
But there was another name listed in the supporting records.
My mother’s.
Dad stared at her.
“You told me you never signed anything.”
Mom began sobbing.
And then she whispered the words that made my blood run cold.
“I didn’t sign the deed, Richard. But I helped Derek get the money.”
The agent closed the folder.
“Then we need to discuss the transaction that happened before your husband entered the hospital.”
Dad slowly looked at his wife of forty-eight years.
“What transaction?”
She couldn’t answer.
Because the next document contained a transfer authorization bearing Dad’s signature—and a date when he had been unconscious.
Nobody spoke for several seconds.
My father stared at the transfer authorization as though the paper itself had betrayed him.
“That’s my signature,” he finally said.
The agent nodded. “It resembles your signature, sir. However, the bank’s records indicate that this authorization was submitted electronically using credentials associated with your account while you were hospitalized.”
Dad looked at Derek.
“Did you use my computer?”
Derek’s jaw tightened.
“I was trying to protect the family.”
“From what?” I asked.
He swung toward me.
“You have no idea what it takes to keep a business alive! I had employees. Loans. Investors threatening to sue me. Every month, something went wrong, and Dad kept telling me to be patient.”
“So you stole his money?”
“I borrowed it!”
“Without permission?”
He said nothing.
One of the agents asked everyone to remain in place while the investigators documented the papers. They weren’t there to settle a family argument. They were investigating possible financial crimes, and every statement made that afternoon could matter.
My mother sat down at last.
For years, she had been the person who reminded me that family loyalty meant forgiveness. She’d told me not to embarrass Derek when he failed to repay loans, not to mention his unpaid bills, and not to question him when he asked Dad for money.
I had believed she was simply protecting her favorite child.
Now I wondered how long she’d known what was happening.
“Mom,” I asked, “why did you help him?”
She wiped her face.
“Because I thought I could fix it before your father found out.”
“That isn’t an answer.”
She looked at the guests gathered around the dining room. Some had lowered their eyes. Others were staring openly, as if the birthday party had become a courtroom.
“Derek told me he was going to lose his company,” she whispered. “He said the creditors would take everything. He promised he could repay the money after he sold a development project.”
“And the house?”
“He said selling the house was the only way to cover the remaining debt.”
“But it isn’t his house.”
She looked at Dad.
“I know that now.”
The words were so small that I almost didn’t hear them.
Dad pushed his chair away from the table.
“Tell them what you did, Linda. All of it.”
She began to cry harder.
And that was when the first real secret came out.
The truth about the trust
My grandmother, Evelyn Carter, had been a practical woman who disliked arguments and distrusted promises that weren’t written down.
She had purchased the house in a quiet Pennsylvania town decades earlier. After my grandfather died, she renovated it room by room, kept careful records of every expense, and built up savings from a small commercial property she rented to local businesses.
She loved both her son, Richard, and her grandchildren. But she had never pretended that love meant everyone should receive the same responsibilities.
When I was twenty-four, I helped her organize her bills and insurance documents after she struggled to keep track of the paperwork. I worked in accounting, and I was comfortable with numbers.
Derek, meanwhile, had a gift for selling ideas. He could make a risky business sound like a guaranteed success. Grandma enjoyed his enthusiasm, but she worried about his habit of borrowing against tomorrow.
Before she died, she established a revocable living trust and placed the house into it. The trust named Dad as the person entitled to live there during his lifetime, while providing for the property’s eventual transfer according to her written instructions.
The documents also included safeguards for managing the property if Dad became incapacitated.
I was named as the successor trustee under specified circumstances, with the responsibility to protect the property and follow the trust’s terms. I wasn’t automatically allowed to do whatever I wanted with it, and I couldn’t simply throw Dad out or sell the house for personal gain.
Grandma had wanted the house maintained, not turned into a prize in a family feud.
I remembered the afternoon she explained the arrangement to me.
“People get strange around property,” she had said, sliding the papers into a folder. “The best way to prevent arguments is to make sure nobody can pretend they don’t know the rules.”
At the time, I thought she was being overly cautious.
I didn’t understand how right she was.
After Grandma died, Dad continued living in the house. He paid some expenses from his income, and I gradually took over the maintenance when his health began to decline.
Derek was never the owner.
He had no authority to sell the property simply because he was Dad’s son.
But the recorded deed and trust documents didn’t tell the entire story of what happened next.
According to the agent, investigators had found that Derek submitted documents claiming that Dad had authorized him to transfer the property. Those papers were accompanied by financial records suggesting that the family home would be sold to cover debts connected to Derek’s business.
The proposed sale had never been completed.
A title company had flagged inconsistencies in the documentation, and the attempted transaction attracted further scrutiny. My earlier report concerning the suspicious withdrawals gave investigators another reason to examine the financial trail.
The federal agents weren’t there because a family member had made an angry phone call. They had been investigating potential financial misconduct, and the evidence had led them to our front door.
That distinction mattered.
Derek had spent years convincing our relatives that he was the successful son and I was the difficult daughter who couldn’t let go of an old grudge.
Now the records were speaking for themselves.
The money Mom helped move
The agent asked my mother to explain the transfers.
She admitted that Derek had told her his company was in danger of collapsing. He showed her overdue invoices, messages from creditors, and a spreadsheet claiming that a major payment was expected within weeks.
He said he needed temporary access to Dad’s rental income.
Mom had access to some of Dad’s financial information because she helped him with bills. She had also kept copies of documents he used when arranging his medical care.
Derek persuaded her to help transfer money into an account he controlled, telling her it would be returned as soon as his business received payment.
The first transfer was relatively small.
When the expected payment didn’t arrive, Derek asked for more.
Mom said she had panicked when she realized the money was not coming back. Instead of telling Dad, she accepted Derek’s next promise: the sale of the house would solve everything.
She had allowed herself to believe that if the property sold quickly enough, no one would ever need to know.
“Did you know the authorization was false?” the agent asked.
Mom pressed her hands together.
“I knew Richard hadn’t approved the sale. Derek said he’d take care of the paperwork.”
“Did you provide him with your husband’s account credentials?”
She nodded.
Dad closed his eyes.
I had never seen him look so old.
He wasn’t only grieving the missing money. He was realizing that the two people he had trusted most had made decisions behind his back while he was recovering from surgery.
“Why didn’t you tell me?” he asked her.
“I was ashamed.”
“You were afraid of the consequences,” he replied. “And you let me believe my own son was helping me.”
Mom had no answer.
The investigators collected copies of the financial documents and explained that they would need to verify the account records, the trust paperwork, and the authenticity of the signatures. They made no promise about when the investigation would conclude.
Derek, meanwhile, had stopped trying to look confident.
He kept insisting that he intended to repay everything.
But intent wasn’t the same as authorization, and a promise to return money didn’t erase the question of how it had been obtained.
One agent asked him to step aside for a private conversation with his attorney.
Derek looked at me before he left.
“You could have handled this privately.”
I couldn’t believe he was still saying it.
“You announced in front of twenty-three people that I was being thrown out of my own home,” I replied. “You brought a real estate agent to Dad’s birthday and waved around documents you had no right to use. What exactly did you think a private conversation would accomplish?”
He looked away.
For the first time in my life, my brother had nothing clever to say.
The second twist
I thought the worst revelation was over.
Then Dad asked the question nobody else had thought to ask.
“What happened to the money from the commercial property?”
The agent consulted his notes.
“Some of the funds went to business creditors. Other payments went to accounts associated with your son’s company. We are still tracing the remaining transfers.”
Dad frowned.
“Derek told me the business was doing well.”
“It wasn’t,” I said softly.
The truth was that Derek’s company had been struggling for more than a year. He had taken out loans to finance a project that failed to attract enough investors. Instead of telling the family, he continued presenting himself as a successful businessman.
He bought expensive gifts, hosted dinners, and posted photographs from hotels that made his life look effortless.
Meanwhile, he was falling further into debt.
But the investigators had discovered another detail: some of the disputed funds had been used to pay the mortgage on a condominium Derek had purchased with his wife, Megan.
He had told everyone that the condominium was financed entirely through his company’s profits.
Megan, who had been standing near the hallway, suddenly stepped forward.
“I didn’t know,” she said.
Derek turned on her.
“Stay out of this.”
“No,” she replied. Her voice shook, but she didn’t back down. “You told me the company paid you a salary. You said the money for the down payment was yours.”
The agent explained that the financial records would have to establish what she knew and whether she had participated in any improper transactions. Being married to Derek did not automatically make her responsible for his conduct, just as being his sister did not make me responsible.
Megan began to cry.
“I signed paperwork because he told me everything was legitimate.”
She looked at Dad.
“I’m sorry.”
Dad nodded slowly, but he didn’t reassure her. There were too many unanswered questions.
Then Derek made one final mistake.
He pointed at me and shouted, “She knew about the trust! She knew the house would eventually be hers! She wanted me ruined so she could keep everything!”
The agent interrupted him.
“Mr. Carter, the trust does not give your sister unlimited ownership today. The documents establish specific responsibilities and future interests. We will determine what was represented, who submitted the paperwork, and whether anyone knowingly made false statements.”
His words were measured and precise.
They were also the first time someone had explained the situation without turning it into a contest between siblings.
I hadn’t reported Derek because I wanted the house.
I had reported suspicious financial activity because Dad’s money was disappearing.
The difference was everything.
What happened after the birthday
The party ended without cake being served.
Relatives left in small groups, speaking in hushed voices. Several apologized to me at the door. One aunt admitted she had believed Derek’s claim that I was refusing to help Dad.
I didn’t ask anyone to take my side.
I was tired of defending myself against stories my brother had invented.
Over the following weeks, investigators continued examining the documents and financial transactions. Dad hired an independent attorney to advise him about the trust and protect his interests. I also obtained separate legal advice regarding my responsibilities as successor trustee.
The proposed sale was stopped while the ownership records and disputed authorization were reviewed.
The trust’s attorney confirmed that Derek had no authority to sell the house merely because he was Dad’s son. The suspicious transfer documents did not override the existing trust arrangements, and the property remained protected while the dispute was addressed.
The financial investigation took longer.
Some of the money had gone to legitimate business creditors. Other transfers remained disputed, and recovering the full amount would require tracing the funds and following the applicable legal process.
There was no instant miracle and no dramatic check arriving the next morning.
There were bank statements, interviews, legal bills, and difficult conversations.
Derek eventually retained an attorney and stopped contacting me directly about the house. The authorities pursued the allegations based on the evidence they could establish, not simply because our family had accused him.
Mom moved into the guest room for a while after Dad told her he needed space. Their marriage did not collapse overnight, but neither did it return to normal because she apologized.
Dad had questions she couldn’t answer with a single expression of regret.
I refused to become their mediator.
For years, I had been expected to absorb the consequences of everyone’s decisions. I had paid for repairs, covered shortfalls, and remained silent when Derek humiliated me.
This time, I helped Dad find professionals who could protect his finances, then let them do their jobs.
I continued living in the house while its legal status was clarified. I kept receipts for maintenance costs, documented repairs, and made sure Dad’s expenses were paid transparently.
I didn’t change the locks to punish my brother.
I didn’t sell the house out of spite.
And I didn’t use the trust to threaten anyone.
Grandma had created the arrangement to preserve the property and protect Dad’s right to live there. I intended to honor that purpose.
The conversation with Dad
About three months after his birthday, Dad asked me to sit with him in the living room.
The framed photograph of Grandma still stood above the fireplace.
“I owe you an apology,” he said.
I waited.
“I knew Derek was having money problems. I knew he was asking for help. But I convinced myself that helping him was the same as believing in him.”
He rubbed his hands together.
“When he said you were being selfish, I believed him because it was easier than admitting I had ignored the warning signs.”
My throat tightened.
“I wasn’t trying to take anything from you, Dad.”
“I know that now.”
He looked toward the window.
“When you asked whether I had signed those papers, I should have answered you honestly. I was embarrassed. I didn’t want the family to know how much trouble we were in.”
“You were scared.”
“Yes,” he said. “But you were scared too, and you still told the truth.”
I sat beside him.
For years, I had wanted Dad to defend me when Derek mocked my job, my finances, or the fact that I hadn’t built my life around impressing other people.
I had imagined that one day Dad would stand up at a family gathering and tell everyone how wrong they had been about me.
But when the moment finally came, I discovered that I didn’t need a public speech.
I needed honesty.
“I don’t want to spend the rest of my life fighting Derek,” I told him. “I want you to be safe. I want the money accounted for. And I want this house to stop being used as leverage.”
Dad took my hand.
“Then that’s what we’ll do.”
We sat quietly for a while.
For the first time since the investigation began, I felt as though the house was a home again rather than a battleground.
The birthday that finally ended
Almost a year later, Dad celebrated his seventy-sixth birthday.
There were fewer guests this time. No real estate agent. No folder of mysterious documents. No champagne toast about throwing someone out.
Dad asked me to help him arrange the dining room, and we placed Grandma’s photograph beside the cake.
He gave a short toast before dinner.
“This house has survived a lot,” he said. “But a house is not valuable because of its price. It’s valuable because the people inside it respect one another.”
He paused.
“I didn’t always understand that. I’m trying to do better.”
He didn’t name Derek.
He didn’t mention the investigation or ask the family to forgive anyone.
He simply sat down and began serving dinner.
The legal process continued beyond that birthday. The disputed transactions were reviewed, the trust remained in place, and any financial recovery depended on what the records and courts ultimately established.
Derek and I did not suddenly become close.
He sent one message saying he hoped I could forgive him someday. I didn’t respond immediately. Forgiveness, if it ever came, would not mean pretending the documents had been harmless or that Dad’s trust had never been broken.
Mom and Dad began counseling, and Dad kept control of his personal finances with independent professional guidance. Mom had to rebuild trust through consistent actions rather than promises.
I learned to say no without explaining myself for an hour.
I learned that helping someone did not require protecting them from every consequence.
And I learned that silence could be useful—but only when it gave you time to gather facts, not when it allowed someone else to keep hurting you.
Sometimes, I still remember the sound of those champagne glasses clinking together while Derek announced that I had to leave.
I remember the laughter.
I remember stepping outside and making that phone call with shaking hands.
But what I remember most clearly is the moment the federal agent placed the documents on the table and asked everyone to stop pretending.
The sirens hadn’t arrived because I was rich, powerful, or secretly waiting to destroy my family.
They arrived because the evidence deserved to be examined.
My grandmother’s trust protected the house. The financial records exposed the trail. And the truth gave my father a chance to make decisions based on facts instead of fear.
Derek had told me to pack my bags because he believed that the loudest person in the room controlled the outcome.
He was wrong.
The house remained a place where Dad could live with dignity, and I stopped allowing family pressure to dictate what I owed everyone else.
I didn’t celebrate my brother’s downfall.
I celebrated the fact that I no longer had to lie to protect him.
And every year, when Dad blows out his birthday candles, I make the same quiet wish:
That the people we love will learn to tell the truth before the truth has to arrive with sirens.
Because the most important thing I saved that day wasn’t a house. It was my father’s right to know what was happening to his own life—and my own right to stop being the family scapegoat.