The closing was supposed to happen at nine the next morning, and by noon my parents were already arguing over which wall in the new kitchen should hold their family photos.
I stood in their driveway holding the final settlement statement and tried to feel proud.
For eight months, I had paid for almost everything that made their “dream home” possible.
The $48,000 down payment.
The inspection and sewer scope.
The appraisal gap.
The electrical work the seller refused to cover.
Even the closing costs.
My parents, Denise and Robert, kept telling me they would add my name to the deed after closing.
“You’re not just helping us,” Mom had said. “This will always be your home too.”
I believed her.
They had spent my whole childhood reminding me how lucky I was to have parents who “sacrificed everything.” Whenever I hesitated before helping financially, Dad would smile and say, “We never kept score with you.”
So I stopped keeping score with them.
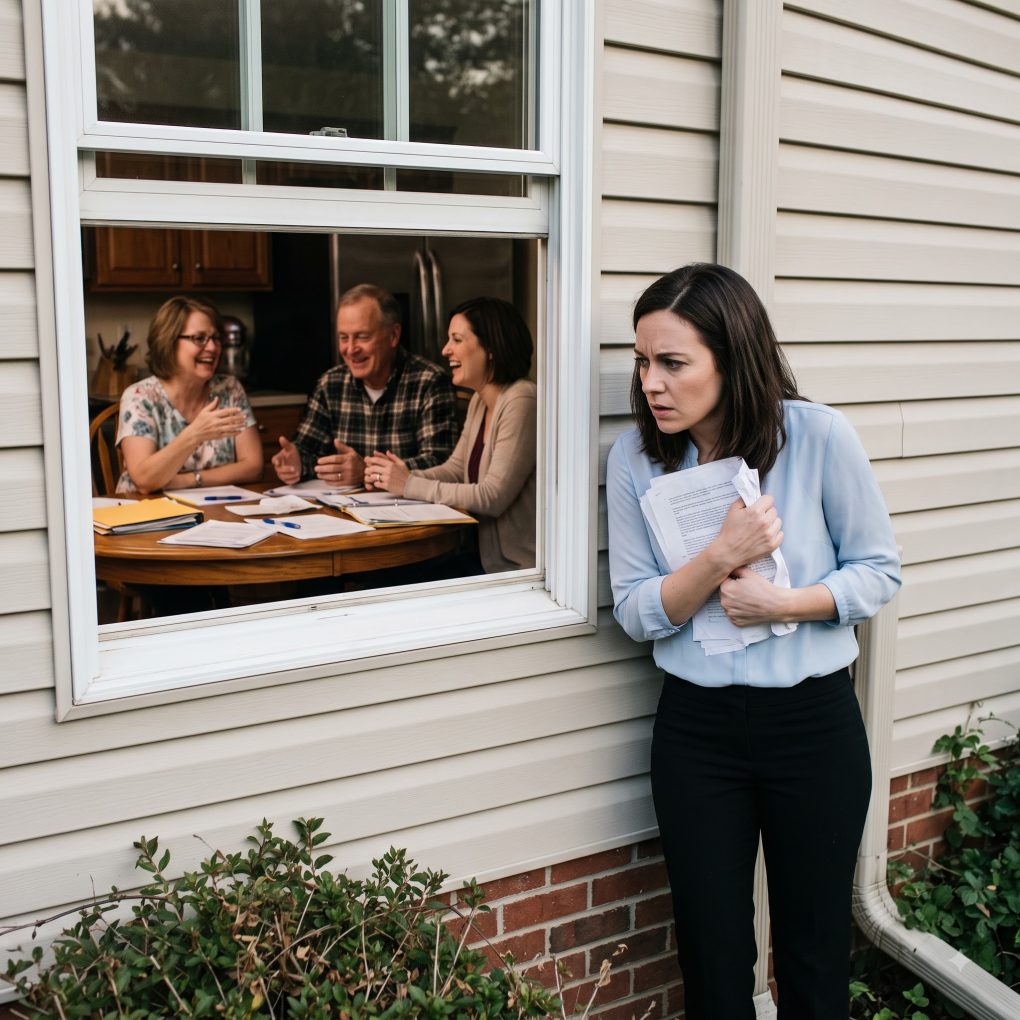
That afternoon, I drove over to drop off the wire instructions. Their kitchen window was open.
I heard Mom laughing before I reached the back door.
“She still thinks we’re putting her on the deed.”
I stopped.
Dad said, “Keep your voice down.”
“She’s not here.”
Then my sister, Lauren, spoke.
“What happens when she figures it out?”
Mom answered immediately.
“She won’t do anything. Emily is too grateful. She always has been.”
My fingers tightened around the folder.
Lauren lowered her voice.
“And the trust?”
Dad said, “After closing, we transfer the house into the family trust. You and the boys are the beneficiaries. Emily doesn’t need to know until later.”
I couldn’t breathe.
Lauren laughed nervously. “She paid for half this place.”
“More than half,” Mom corrected.
Then all three laughed.
I stood beneath that window while the people I trusted most discussed me like I was a financing plan.
Dad added, “Once the money funds tomorrow, it’s done. She signed the gift documentation.”
My stomach dropped.
I had not signed a gift letter.
Three days earlier, their loan officer had emailed one because the lender needed proof my money was an unconditional gift.
I had left it unsigned.
Mom apparently thought I had completed it.
I backed away without making a sound.
Inside my car, I opened the email and called the closing attorney.
“This is Emily Carter. I’m the third-party source of funds for Denise and Robert Carter’s purchase tomorrow.”
“Yes, Ms. Carter.”
“Has my contribution been disbursed?”
“No. Funds won’t be disbursed until closing is complete.”
“Good. I’m not signing the gift affidavit, and I’m withdrawing authorization for any additional funds from me.”
There was a pause.
“Then their lender may not be able to fund.”
“I understand.”
By 5:43 that evening, Dad had called me eleven times.
At 5:51, Hannah emailed that the lender had pulled its clear-to-close and the seller was moving to a backup offer.
The house they thought was already theirs was gone before sunset.
They thought losing the house was the worst thing that could happen. By morning, a document carrying Emily’s name would reveal that the betrayal had started long before she ever stood beneath that kitchen window.
My phone kept ringing until almost midnight.
I answered on the twelfth call.
Mom didn’t say hello.
“What did you do?”
I sat at my kitchen table, staring at the unsigned gift affidavit. “I stopped paying for a house you planned to give Lauren.”
Silence.
Then Dad came on the line.
“You misunderstood a private conversation.”
“I heard the words family trust.”
“That was estate planning.”
“With Lauren and her boys as beneficiaries.”
Mom snapped, “After everything we’ve done for you, you’re destroying our retirement over paperwork?”
There it was again.
Gratitude.
The leash they had disguised as love for thirty-two years.
I asked one question. “Were you ever going to put me on the deed?”
Neither answered.
I hung up.
The next morning, closing attorney Hannah Brooks called. She explained that some money I had advanced—inspection fees, appraisal costs, and electrical work—was likely unrecoverable. But the large transfer sitting in escrow had not been released.
Then Hannah said, “There’s another issue.”
She emailed me a PDF.
I opened it and felt cold.
It was the gift affidavit.
My name appeared at the bottom.
So did an electronic signature.
“I didn’t sign this.”
“That’s why I’m calling,” Hannah said. “The lender received this copy yesterday.”
I enlarged the page.
The signature looked like mine, but the email address in the verification line was one digit different from my real address.
Someone had created an almost identical account.
“Who submitted it?”
“We’re preserving the records. Don’t contact anyone about the document until you speak with counsel.”
My parents’ betrayal had just become something else.
I hired an attorney that afternoon.
By Friday, the lender had frozen the file and opened an internal fraud review. My parents kept insisting the signature problem was a “clerical mistake.”
Lauren called me crying.
“I didn’t know about the fake email.”
“But you knew about the trust.”
She went quiet.
“How long?”
“Since Christmas.”
Seven months.
She had eaten dinner with me and watched me write checks for a house she knew would eventually benefit her children.
“Why didn’t you tell me?”
“Mom said you wanted to help.”
“I wanted to help our parents.”
“She said you didn’t care about ownership.”
I laughed because otherwise I would have screamed.
Then Lauren whispered, “Emily, there’s more.”
I closed my eyes.
“What?”
“The house wasn’t the first time.”
She told me to look at the account our parents opened when I was sixteen—the one where I deposited money from summer jobs, internships, and my first salaried position because Dad said he was “helping me save.”
I hadn’t used it in years.
I logged in.
The transaction history showed transfers I had never noticed because the statements went to my parents’ address.
Small amounts at first.
Then larger ones.
One recipient appeared repeatedly.
LAUREN CARTER.
I called my attorney.
He told me to download every statement immediately.
Then I reached the oldest available record.
A transfer for $21,000 had been made eight years earlier.
The memo contained three words.
“Lauren house deposit.”
The $21,000 transfer changed the question.
I was no longer asking whether my parents had betrayed me once.
I was asking how long they had been doing it.
My attorney, David Kim, traced the old account documents with me. It wasn’t a custodial account, as Dad had implied. It was a joint savings account opened when I was sixteen, with both our names attached.
That meant Dad could withdraw money without asking me.
Legally complicated.
Emotionally simple.
Eight years earlier, Lauren and her then-husband had bought their starter home. Mom told everyone they received “help from his family.”
The help was mine.
Lauren came to my apartment the following Sunday carrying a binder.
“I found these in Mom’s desk,” she said.
Inside were handwritten pages where Mom tracked money taken from my account.
Summer job: $1,400.
Internship savings: $3,200.
House deposit: $21,000.
Beside several entries, Mom had written one word.
Repayment.
“For what?” I asked.
Lauren started crying. “She says raising you cost more because of your braces, college applications, everything.”
I stared at her.
They had turned ordinary parenting into an invisible invoice.
Two weeks later, their attorney requested a settlement meeting.
Mom barely looked at me.
Dad did.
He admitted he created the look-alike email address and copied my signature from an old insurance form onto the gift affidavit because the lender would not approve the mortgage without documentation for my contribution.
“I was going to explain after closing,” he said.
“No. You were counting on me being too grateful to object.”
He had no answer.
The house was already gone. The seller closed with the backup buyer eleven days after my parents’ failed closing.
My escrowed contribution—$48,000 plus the amount reserved for closing expenses—was returned. I lost several thousand dollars on inspections, appraisal work, and repairs I had funded before owning the property.
I considered that tuition.
The older money took longer.
Because Dad had been a joint account holder, recovering every historical transfer through court would have been expensive and uncertain. But the forged affidavit gave my parents a much bigger problem with the lender.
We settled.
They repaid the $21,000 house deposit, reimbursed my unrecoverable purchase expenses, and signed a written acknowledgment that I owed them nothing for being raised.
Lauren sold investments and returned the smaller transfers she admitted receiving.
After that, I closed every account connected to my parents.
I changed banks.
Changed beneficiaries.
Changed emergency contacts.
Then I changed the hardest thing: my definition of family.
Six months later, I used part of the returned money as a down payment on a small brick townhouse outside Cincinnati.
Two bedrooms. A narrow patio. A kitchen window over the sink.
On moving day, Mom sent one message.
“We loved you. I hope someday you remember that.”
I read it twice.
Then deleted it.
Love may include sacrifice and forgiveness.
It does not require one person to remain conveniently deceived so everyone else can benefit.
My parents thought gratitude guaranteed my silence.
What they heard afterward was nothing.
No screaming.
No revenge speech.
Just the sound of every financial door they had used quietly locking behind me.
And this time, I kept the keys.