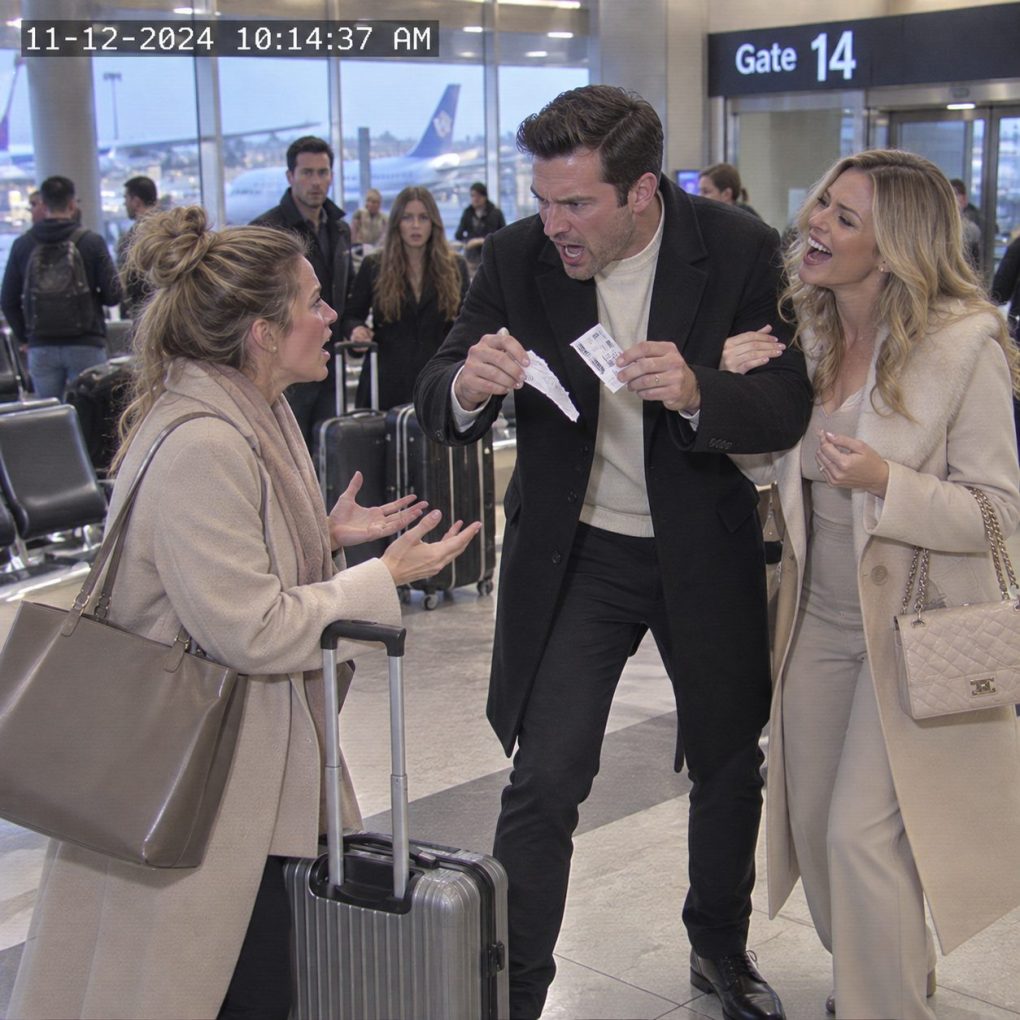
My husband ripped my boarding pass in half at JFK Airport while his mistress laughed beside him. “You’re not coming to Geneva, Emily. This deal belongs to me now!” he shouted. Then he boarded the plane carrying documents for the $85 million sale of the company we had built together. He thought I would return home crying. Instead, I called our corporate attorney. By the time his plane landed in Switzerland, the investors had received evidence of his fraud, and the entire transaction was in danger.
My name is Emily Carter. I’m forty-two years old, and I live in New York. Fifteen years ago, my husband, Richard, and I founded Carter Biomedical Solutions, a company manufacturing specialized laboratory equipment. I developed our original technology while Richard handled sales and investor relationships.
We started in a rented warehouse with three employees. After years of financial struggles, our company expanded into international markets. By last year, we employed 180 people and generated nearly $26 million in annual revenue. I owned fifty-one percent of the voting shares, while Richard controlled thirty-nine percent. The remaining shares belonged to early investors.
Three months earlier, a Swiss investment group approached us about purchasing a controlling interest for approximately $85 million. Richard immediately took charge of negotiations. He claimed the investors preferred dealing with him because he was the company’s public representative.
I initially trusted him. Then I discovered unusual consulting payments totaling $640,000. The money had been transferred to a company registered under the name of his executive assistant, Vanessa Reed. When I questioned Richard, he insisted the payments covered legitimate international business development expenses.
Two weeks later, I discovered Richard and Vanessa were having an affair. I confronted him privately, but he refused to discuss our marriage. Instead, he demanded that I sign documents transferring my voting authority to him before the Geneva negotiations.
I refused. Our shareholders’ agreement required board approval for major transactions, and my controlling shares couldn’t be transferred without my written consent.
At JFK Airport, Richard finally revealed his intentions. Vanessa stood beside him wearing an expensive ivory coat. When I approached the departure gate, Richard grabbed my printed boarding pass and tore it apart.
“You’re finished, Emily!” he shouted. “The investors want me, not some laboratory technician pretending to be an executive.”
Vanessa laughed as Richard walked toward the gate. I watched them disappear, then called our attorney, Sarah Mitchell. “Send the board everything we found,” I instructed. “And notify the Swiss investors that Richard has no authority to sell my shares.”
Four hours later, Sarah called back. The investors had suspended their scheduled signing ceremony. More importantly, their lawyers had discovered that Richard’s transaction documents contained a forged authorization bearing my signature.
I was sitting in an airport lounge when Sarah explained what the Swiss legal team had uncovered. Richard had submitted a document claiming I had granted him authority to negotiate and approve the transfer of my controlling shares. The signature looked convincing, but I had never signed it.
Sarah had already compared the document with our corporate records. The supposed authorization contained an electronic signature certificate issued through an account I didn’t recognize. Our internal technology team confirmed that the account had been created using company administrative credentials two weeks earlier.
The discovery was serious because Richard had repeatedly assured the investors that all necessary shareholder approvals were secured. In reality, our board had authorized preliminary negotiations only. No final sale agreement had been approved, and no shareholder had granted Richard unrestricted authority.
Sarah immediately requested an emergency board meeting. She also instructed our IT director to preserve relevant emails, transaction records, and access logs. I approved the preservation measures through the proper corporate procedures, knowing that any investigation would require reliable evidence rather than personal accusations.
Meanwhile, Richard’s plane landed in Geneva. According to an email forwarded by the investors’ attorney, he arrived expecting a private dinner followed by the final negotiations. Instead, representatives informed him that the transaction was suspended pending an independent review.
Richard called me seventeen times. When I finally answered, he was furious. “WHAT DID YOU TELL THEM?” he demanded. I explained that I had corrected inaccurate statements concerning ownership and voting authority. He accused me of destroying fifteen years of work because I was jealous of Vanessa.
Then he threatened to remove me from the company. I reminded him that corporate governance didn’t work that way. As majority voting shareholder, I had rights he couldn’t simply erase. Richard shouted that he had already promised Vanessa a senior executive position after the acquisition.
The following morning, our finance director uncovered additional irregularities. Several consulting invoices submitted by Vanessa’s company contained vague descriptions, duplicate billing periods, and approvals issued directly by Richard. The questionable payments had continued even after our accounting department requested supporting documentation.
Our independent auditors began reviewing the transactions. Preliminary findings suggested that some payments lacked adequate business justification. We couldn’t yet establish whether every invoice was fraudulent, but the evidence was sufficient for the board to restrict Richard’s spending authority while the investigation continued.
By Wednesday, the board had placed Richard on administrative leave. His access to corporate banking systems and confidential transaction materials was suspended. The directors appointed our chief operating officer as interim president and retained outside counsel to conduct an independent investigation.
Vanessa returned to New York alone. She contacted me through an attorney, claiming Richard had promised her ownership in the company after the sale. I declined to discuss her personal relationship with him. Any legitimate employment or compensation claim would be reviewed through the company’s legal process.
Then Sarah received another message from Geneva. The investors had discovered that Richard was negotiating a separate personal consulting agreement worth $4.5 million, payable after the acquisition. The arrangement had never been disclosed to our board. When the investors demanded an explanation, Richard reportedly insisted the money was compensation for delivering the company without my interference.
The independent investigation lasted six weeks. During that period, I continued managing our research and manufacturing operations while the interim president handled daily executive decisions. I refused to let Richard’s misconduct jeopardize the jobs of 180 employees who had helped build Carter Biomedical Solutions.
Investigators examined the consulting payments, the disputed shareholder authorization, and Richard’s communications with the Swiss investors. They found evidence that he had instructed an administrative employee to create the unauthorized signature account. The employee admitted following Richard’s directions but denied knowing the document would be presented as genuine.
The forensic accounting review identified approximately $510,000 in payments that lacked sufficient supporting documentation. Richard’s attorneys disputed the findings, arguing that the expenses involved confidential business development. However, the company initiated civil proceedings seeking recovery of funds it believed had been improperly transferred.
The board also reviewed Richard’s undisclosed consulting arrangement. The proposed $4.5 million payment created a substantial conflict of interest because Richard stood to receive personal compensation if the acquisition succeeded. He had not disclosed the arrangement during the board’s consideration of the transaction.
Richard eventually returned to New York and demanded a meeting with me. We met in a conference room with our attorneys present. He looked exhausted, but his first words were another accusation. “You could have handled this privately instead of humiliating me internationally.”
I stared at him. “You tried to transfer my shares without permission, concealed company payments, and negotiated millions for yourself. What exactly did you expect me to do?” Richard said nothing. For the first time in fifteen years, he seemed unable to control the conversation.
Our divorce proceedings began shortly afterward. The company shares were addressed according to applicable marital property rules, existing ownership agreements, and the court’s eventual determinations. I didn’t pretend that my fifty-one percent voting interest automatically settled every financial question between us.
Meanwhile, the Swiss investors expressed continued interest in our technology. They proposed restarting negotiations after the investigation concluded and the company established stronger governance procedures. This time, I led the discussions alongside independent directors and outside counsel.
Four months later, we signed a revised agreement involving a minority investment rather than the original controlling acquisition. The arrangement provided capital for expansion while allowing our existing management team to retain operational independence. The board approved the transaction after reviewing independent financial advice and the necessary shareholder consents.
Richard resigned from his executive position under a negotiated separation agreement. The company continued pursuing its financial claims, while the disputed signature documents were referred to the appropriate authorities. I couldn’t predict every legal outcome, but the evidence had permanently changed his position.
One year after the airport confrontation, I traveled to Geneva again. This time, I attended an international medical technology conference as the company’s chief executive officer. After presenting our newest laboratory system, I stood beside the conference center windows overlooking the city. I remembered Richard tearing my boarding pass while Vanessa laughed. He believed that destroying one piece of paper could erase my authority, my work, and my future. Instead, his actions exposed everything he had tried to conceal. I hadn’t needed revenge. I had needed the truth, the records, and the courage to defend what I had spent fifteen years building.