“My family threw a party to celebrate kicking me out. I quietly took one photo of their banner before leaving—and ruined everything for them 2 weeks later.”
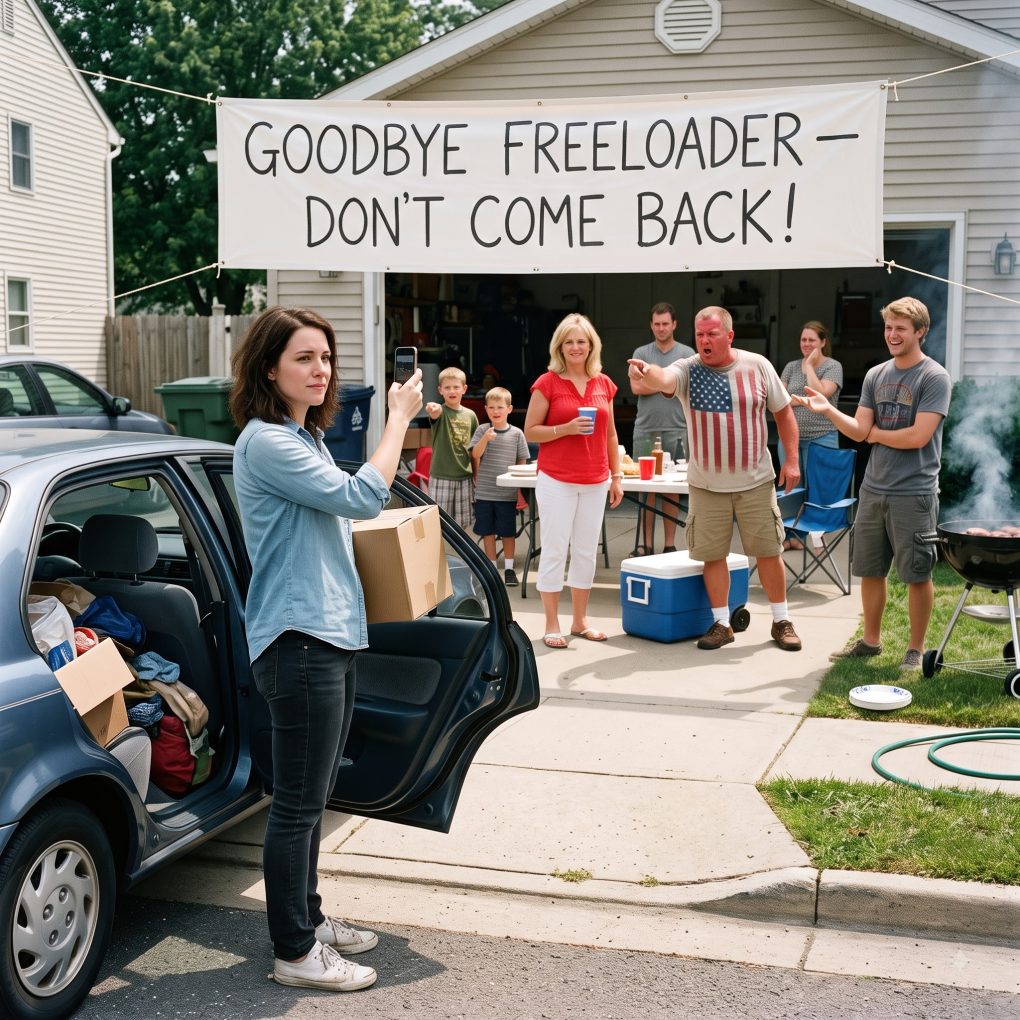
The banner above my mother’s garage read, “GOODBYE FREELOADER — DON’T COME BACK!”
Thirty feet below it, my family was throwing a barbecue to celebrate kicking me out.
My uncle Frank stood on the patio, drunk enough to spill beer down his shirt. “Twenty-nine years old and no career! Your poor mother had to feed your lazy ass for years!”
My brother Tyler laughed, picked up a hot dog, and hurled it at my car.
“There’s your last free meal, loser!”
It bounced off the hood.
Even my little cousins were pointing and laughing.
I stood beside my trunk, staring at the last cardboard box I’d come to collect. My clothes, an old laptop, and a framed photograph of my late grandmother were packed inside.
Mom sat beneath a red patio umbrella, smiling like she’d organized the greatest party of her life.
“Don’t forget to thank us for putting up with you so long!” she called.
I didn’t answer.
For three years, I’d lived in her house while working temporary jobs and completing online courses in project management. What my family never mentioned was that I’d also paid the electric bill, covered groceries, and contributed $900 a month toward household expenses.
When I lost my job eight months earlier, I kept paying until my savings ran dangerously low. I asked Mom for two months to get back on my feet.
She gave me one week.
Then she changed the locks.
Now, as my relatives celebrated my humiliation, I lifted my box into the car, took one clear photograph of the banner with everyone partying beneath it, and drove away.
Nobody noticed the second photograph I took before leaving: the garage, the house number, and the expensive new patio renovation Mom had recently claimed she couldn’t afford.
Two weeks later, my phone exploded.
Tyler: “TALK NOW.”
Uncle Frank: “Sweetie, I was drunk. I didn’t mean any of it.”
Mom: “CALL ME BACK. PLEASE. I’M BEGGING YOU.”
I stared at the messages without replying.
Then an unfamiliar number called.
“Is this Daniel Carter?” a woman asked. “I’m calling about your mother’s property. We need to discuss the documents she submitted—and your name appears on them.”
My stomach tightened.
“What documents?”
She paused.
“Your mother says you agreed to take financial responsibility for the house. But the information we’ve received suggests something very different.”
I sat down slowly.
Because the house they’d thrown me out of wasn’t the only thing my family had been lying about.
The photograph I took at that barbecue was about to become the least of my family’s worries. Someone had discovered what my mother had done behind closed doors—and suddenly, the son they called a freeloader was the one person they desperately needed to find.
“Mr. Carter?” the woman repeated. “Are you still there?”
I gripped my phone.
“Yes. Who are you?”
“My name is Rachel Morgan. I work with the servicing department handling a loan secured against your mother’s property. Your name appears as a guarantor on documents submitted during a recent refinancing application.”
I felt the blood drain from my face.
“I never guaranteed my mother’s loan.”
“That is what I needed to clarify. The signature resembles yours, but some details don’t match the identification we have on file. We need you to confirm whether you authorized the agreement.”
I told her I had not.
She advised me to submit a written dispute and preserve any relevant records. I promised to do so, then immediately called a lawyer.
His name was Michael Reeves, and he’d helped me review an employment contract the previous year. After I explained the situation, he told me not to contact my mother until we’d examined the documents.
That afternoon, I received copies of the disputed paperwork.
My name appeared beneath a personal guarantee for a $185,000 home-equity loan.
I had never seen the document before.
The application claimed I earned $78,000 a year and had agreed to be responsible for the debt if Mom defaulted. The employment information was partly accurate, but it listed an employer I’d left months earlier.
Someone had taken old information and used it to make me look financially stable.
Then I noticed the date.
The application had been submitted four days before Mom kicked me out.
Suddenly, the barbecue made a horrible kind of sense. She hadn’t merely decided she was tired of supporting me. She’d been preparing to remove me from the house while using my name to support a loan.
Michael advised me to dispute the signature, contact the relevant credit bureaus, and secure my financial accounts.
As we reviewed the paperwork, another detail emerged: the loan proceeds had been intended partly to pay for the new patio, a kitchen renovation, and expenses connected to Tyler’s struggling car-detailing business.
My family had called me a freeloader while trying to make me legally responsible for their spending.
Then Tyler called again.
This time, I answered.
“Daniel, what did you tell the bank?” he demanded.
“Nothing except the truth.”
“You’re going to ruin Mom’s life!”
“Did you know she used my name on a loan?”
Silence.
“Tyler?”
“I didn’t know about the signature,” he finally said. “But Mom told me you’d agreed to help with the refinance.”
“I didn’t.”
He exhaled sharply.
“She said you were living there for free, and this was the least you could do.”
I closed my eyes.
“I paid her $900 a month.”
“What?”
“Every month. I have the transfers.”
He went quiet again.
Then he said something that changed everything.
“Mom told everyone you hadn’t paid rent in three years. She said she was throwing the barbecue because you owed her thousands.”
I opened my banking app and stared at the records I’d saved.
Three years of payments.
Thirty-six months of groceries, utilities, and transfers.
The evidence was all there.
But before I could send it to Tyler, Michael called with an update.
The lender had reviewed the disputed application and identified an additional problem.
The property wasn’t worth as much as Mom had claimed, and the loan could not proceed on the terms submitted without further verification.
More importantly, the person who had uploaded the disputed guarantee had used an email address connected to our family.
Michael lowered his voice.
“Daniel, the lender has preserved the submission records. Your mother may have believed she could blame the paperwork on you, but there’s a trail showing who sent it.”
I stared at the barbecue photograph on my computer.
My relatives laughing beneath that banner.
My uncle pointing at me.
My brother throwing food at my car.
Mom smiling while everyone watched me leave.
For the first time, I understood why they were calling.
They weren’t suddenly ashamed of humiliating me.
They were afraid I’d stop protecting them from the consequences of their own decisions.
Then my mother sent a message.
Please come home tonight. We need to talk before the bank makes a decision.
A second message followed.
Bring the documents proving you paid rent. Don’t show them to anyone else.
I read it twice.
She still thought she could control the story.
But Michael had already found one more document that Mom hadn’t mentioned—a signed household agreement establishing exactly what I had paid and what she had promised in return.
And when I saw the final page, I realized the loan wasn’t the only reason she’d been so desperate to get me out.
The final page of the household agreement was dated two years earlier.
Mom had signed it after I paid $4,500 toward an emergency repair to the home’s plumbing system. The agreement stated that my monthly contributions covered household expenses and that the money I advanced for repairs would be repaid when the house was refinanced or sold.
It wasn’t a deed. It didn’t give me ownership of the house. It wasn’t some secret document that magically made the property mine.
But it was proof that Mom had acknowledged my financial contributions and promised to repay a specific amount.
Michael read it carefully.
“This is useful,” he said. “It supports your account of what happened. We’ll need to verify the payments and the exact balance, but she can’t reasonably claim you never contributed anything.”
I looked at the signature.
My mother’s handwriting was unmistakable.
For years, she’d told relatives that I was an adult child who refused to grow up. She’d conveniently left out the months I’d worked two jobs, the groceries I’d bought, and the repair bill I’d covered when she said she couldn’t afford it.
Now there was a signed document confirming at least part of the truth.
“What do we do?” I asked.
“First, we formally dispute the guarantee. Second, we preserve all evidence. Third, we make sure you don’t sign anything under pressure. And if your mother wants to discuss repayment, she can do it through the proper channels.”
I agreed.
That evening, Mom called from her personal number.
I let it ring twice before answering.
“Daniel!” she cried. “Thank God. Where have you been?”
“Working.”
“Why haven’t you called me back? Your brother says you’ve been talking to lawyers.”
“I have.”
She went quiet.
Then her voice changed.
“You don’t need lawyers. We’re family. We can settle this at home.”
“You submitted a loan application using my name.”
“I was trying to get the house refinanced.”
“Did I sign the guarantee?”
“You know how complicated paperwork is.”
“That isn’t an answer.”
She sighed dramatically.
“I thought you’d understand. You lived here for years. We fed you. We gave you a roof over your head. We never charged you what a stranger would have charged.”
“I paid you $900 a month.”
“That was for groceries and bills.”
“And I paid for the plumbing repair.”
“You offered to help!”
“You signed an agreement saying you’d repay me.”
Her silence lasted several seconds.
Then she said, “I can’t believe you’re doing this to your own mother.”
I looked at the documents spread across my table.
“I’m not doing anything to you. I’m correcting a false statement about me.”
She began crying.
“Please come home. The bank is asking questions, and I don’t know what to tell them.”
“Tell them the truth.”
“Daniel, please.”
It was the first time she’d begged me for anything.
Not because she’d missed me. Not because she regretted the banner or the laughter.
Because the lender was asking questions she could no longer answer with a story about her lazy son.
“I’ll communicate through Michael about the loan,” I said. “If you want to talk about our relationship, that can happen separately.”
Then I ended the call.
The next morning, I received a long email from Tyler.
He attached screenshots of the family group chat from the week before the barbecue.
Mom had written that I was living off her, refusing to work, and draining her retirement savings. She said she’d given me years to get my life together and that kicking me out was the only way to teach me responsibility.
Uncle Frank had responded with laughing emojis.
Tyler had written, About time.
The messages made my chest tighten, but one detail mattered more than the insults.
Mom had told them all that I was being evicted because I owed her $12,000 in unpaid rent.
There was no lease stating I owed that amount. There was no accounting supporting it. My bank records showed regular payments, and the household agreement described those payments as contributions toward expenses.
The story she’d told the family was not simply an exaggeration.
It was a version of events designed to make everyone believe I deserved what happened to me.
I forwarded the screenshots to Michael and saved the original messages.
Then I called Tyler.
“Why are you sending me this now?”
His voice sounded tired.
“Because I found out about the loan.”
“You knew Mom was kicking me out.”
“I thought you weren’t paying her anything.”
“You never asked me.”
“I know.”
He paused.
“Daniel, I saw you leaving with that box. I laughed because everyone else was laughing. I threw that hot dog because I thought you were a loser who’d never get anywhere.”
He swallowed.
“I’m sorry.”
I wanted to believe him. But an apology couldn’t erase the fact that he’d humiliated me for entertainment.
“Why did you text ‘TALK NOW’?”
“Because Mom said the lender needed your confirmation. She thought if I could get you to come home, you’d sign whatever they put in front of you.”
That hurt more than the barbecue.
Even now, his first instinct had been to help Mom get what she wanted from me.
“You weren’t calling because you missed me,” I said.
“No. Not at first.”
At least he was finally telling the truth.
“I need some time, Tyler.”
“I understand.”
For once, he didn’t argue.
Over the following week, Michael and I submitted a formal dispute to the lender. I provided identification, employment records, bank statements, and copies of the household agreement. I also explained that I had not consented to guarantee the loan.
The lender paused the application while it investigated the discrepancy. It requested further documentation from Mom and preserved the records connected to the submission.
I changed my banking passwords, enabled additional security protections, and reviewed my credit reports. I also placed fraud alerts where appropriate.
The process was stressful, slow, and frustrating. There was no dramatic courtroom scene or instant declaration that everyone else was guilty. There were forms, calls, questions, and waiting.
But I was no longer waiting for my family to admit I deserved respect.
I was protecting myself.
The lender eventually determined that it could not rely on the disputed guarantee without valid authorization. My name was removed from the application, and the loan could not proceed as originally proposed. Mom had to provide accurate information about her finances and the property’s value.
The investigation into the submitted documents continued separately. I didn’t make public accusations or speculate about legal outcomes. I simply cooperated with the people responsible for reviewing the evidence.
Without the expected loan, Mom had to scale back her renovation plans. She canceled some purchases and negotiated with contractors over work she could no longer afford to complete immediately.
Tyler’s business also had to confront its own financial problems. Mom could no longer use the proposed refinance to help cover his expenses, and he began cutting costs and looking for additional work.
For the first time, they had to make decisions based on their actual finances instead of treating my name as a backup plan.
The household agreement became important when Michael formally requested repayment of the $4,500 repair advance and an accounting of the other disputed expenses. Mom initially denied owing me anything beyond a few hundred dollars.
Then we provided the bank transfers.
Every payment had a date, an amount, and a recipient.
Some were labeled utilities. Others were labeled household contribution or plumbing repair. I had kept the records because I tracked my budget carefully, not because I expected to use them against my mother.
Mom could argue about whether the arrangement was fair, but she couldn’t honestly say no money had changed hands.
After several weeks of negotiation, she agreed to repay the documented repair advance in installments. The other household contributions were treated according to the original arrangement and supporting records; I didn’t claim that every dollar I’d spent living there was a loan.
That distinction mattered to me.
I wasn’t trying to take her house or punish her for every unpleasant thing she’d ever said.
I wanted the truth recorded accurately, my name removed from a debt I had never accepted, and the money she had explicitly promised to repay returned.
The barbecue photograph stayed on my phone.
I never posted it online. I didn’t need thousands of strangers to tell me my family had behaved cruelly. I had watched them do it with my own eyes.
Still, I kept the photograph as a reminder of the day I stopped begging to be treated fairly.
Two months later, Uncle Frank called.
“Sweetie,” he began, using the same nickname he’d shouted across the patio. “I was drunk. I didn’t mean what I said.”
“You called me lazy in front of children who were laughing at me.”
“I had too much to drink.”
“That explains why you were drunk. It doesn’t explain why you thought humiliating me was acceptable.”
He sighed.
“Your mother said you weren’t contributing. I believed her.”
“You could have asked me.”
“I should have.”
His apology wasn’t perfect, but he didn’t demand that I forgive him. He admitted that he’d enjoyed being part of the crowd and that he regretted it.
I told him I needed time.
For once, that was enough.
Mom’s apology came on a handwritten card.
She wrote that she’d been frightened about money and angry that I hadn’t recovered from losing my job as quickly as she’d expected. She admitted that she had used the barbecue to convince herself and everyone else that kicking me out was justified.
She also admitted that she’d told relatives I never paid anything because she didn’t want them asking questions about the household finances.
The card ended with a sentence I had waited years to hear:
You were struggling, but you were not worthless. I treated you as if you were.
I read it several times.
I wanted to believe she understood. But I also knew an apology was only a beginning.
I replied that I was willing to talk when she could respect my boundaries and stop expecting me to solve her financial problems. I did not move back home. I did not agree to guarantee any loan. And I did not promise to pretend the barbecue had never happened.
Instead, I rented a small apartment near my new job.
I found a position coordinating operations for a regional logistics company. It wasn’t glamorous, but it paid reliably and offered room to advance. I built my savings again, replaced my old laptop, and bought a secondhand dining table.
For the first time in years, I knew exactly what my monthly expenses were and didn’t have to wonder whether someone would change the rules without telling me.
Tyler eventually visited me.
He arrived carrying a bag of groceries and an awkward expression.
“I know this doesn’t fix anything,” he said, “but I wanted to bring you something other than an apology.”
We cooked dinner together.
He told me he had stopped expecting Mom to rescue his business. He was taking responsibility for his own debts and had begun paying down what he owed.
I didn’t tell him everything was forgiven.
But I listened.
Over the next year, our relationship improved slowly. He learned that being my brother didn’t entitle him to my money or my immediate forgiveness. I learned that I could allow someone to make amends without pretending their actions hadn’t hurt me.
Mom and I also began speaking again, cautiously. We met for lunch occasionally, and she stopped making jokes about my career. She didn’t always understand my boundaries, but when she crossed one, I ended the conversation instead of arguing until we were both exhausted.
The family never held another barbecue to celebrate my humiliation.
Frank stopped drinking so heavily at family events, though I knew that was a decision he had to make for himself. The younger cousins who had laughed at the banner were old enough to understand that the joke hadn’t been funny. One of them eventually apologized for joining in.
I accepted the apology.
Not because the memory no longer hurt, but because I didn’t want to spend the rest of my life carrying every person’s worst moment as if it were my responsibility to punish them.
A year after the barbecue, I found the photograph while cleaning out my phone.
The banner was still stretched above the garage.
Tyler was pointing at my car. Frank was holding his beer. Mom sat beneath the umbrella, smiling as if she’d finally solved her biggest problem.
I looked at the picture for a long time.
Then I saved it to a folder with the bank correspondence and the signed household agreement.
I didn’t save it as a threat.
I saved it because I wanted to remember the difference between being rejected and being worthless.
My family had told a story in which I was a freeloader who deserved to be thrown out. The records told another story: I had contributed money, covered repairs, kept receipts, and refused to accept a debt that wasn’t mine.
I hadn’t become successful because they humiliated me.
I’d begun rebuilding because I stopped allowing their judgment to define me.
And when Mom called one evening to ask whether I would come over for dinner, I said I’d consider it.
“Can we start over?” she asked.
“No,” I replied gently. “We can start from where we are. But we can’t pretend the past didn’t happen.”
She was quiet for a moment.
Then she said, “I understand.”
I didn’t know whether she fully did.
But this time, I didn’t need to know before moving forward.
I had a job, a home, a future, and the right to decide who could enter it.
They had called me a freeloader beneath a banner designed to make me feel small.
Two weeks later, they begged me to come back.
The greatest change wasn’t that they needed me.
It was that I finally understood I could say no.