Dad gave me exactly one warning.
“If you won’t rescue your sister, I’ll handle it myself.”
We were standing in my kitchen after Sunday dinner, and my younger sister, Bethany, was crying into both hands because she owed nearly $30,000 across credit cards, a personal loan, and months of unpaid bills.
I had already offered something reasonable.
I would pay for a financial counselor.
I would help her negotiate payment plans.
I would even cover groceries for two months while she stabilized.
What I would not do was hand her $30,000.
Dad stared at me as though I had refused to pull her from a burning building.
“You have more than enough.”
“That doesn’t make her debt mine.”
“She’s your sister.”
“And she’s thirty-three.”
Bethany whispered, “You’ve always thought you were better than me.”
I looked at her exhausted face and felt sympathy.
But sympathy was not the same as surrender.
Dad left angry.
At 11:48 that night, my phone buzzed.
Transfer initiated: $29,740.
I sat upright in bed.
The balance of my emergency savings account dropped to almost zero.
I did not scream.
I did not call Dad.
I already knew exactly where the money had gone.
Three weeks earlier, Bethany had accidentally forwarded me an email containing payment instructions from a debt-settlement company called Henderson Resolution Group. The routing information in that email matched the destination shown in my banking alert.
Dad had paid her debt.
With my money.
The question was how.
I called the bank’s fraud line, reported the transfer as unauthorized, and asked them to preserve every access record connected to it.
Then I called my attorney, Nina Caldwell.
“Do not confront him,” she said. “Let the bank determine how he got access.”
I barely slept.
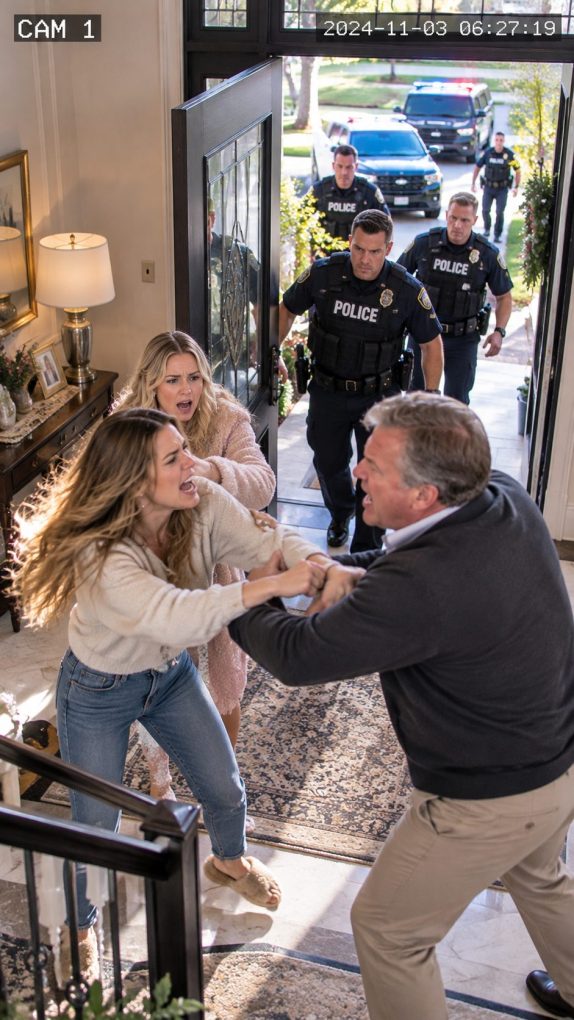
At 5:36 a.m., someone knocked hard on my front door.
I looked through the camera.
Two police officers stood on the porch.
For one horrifying moment, I thought something had happened to Dad.
Instead, the older officer showed identification.
“Ms. Morgan?”
“Yes.”
“We need to ask you about a transfer from your account shortly before midnight.”
“I already reported it.”
He exchanged a glance with his partner.
“That’s why we’re here.”
My stomach tightened.
“Why would police come this quickly over a bank transfer?”
The officer hesitated.
Then he asked the question nobody in my family could possibly have expected.
“Did your father have permission to tell the bank that you had died?”
I stopped breathing.
“What?”
He opened a notebook.
“Because at 10:14 p.m., someone claiming to be your father contacted the bank’s emergency services department and said you had died suddenly.”
The room seemed to tilt.
“He did what?”
“He also presented documents identifying himself as the temporary representative of your estate.”
My hands went cold.
“There is no estate. I’m standing here.”
“We understand.”
Then the officer continued.
“And that’s not the part that triggered the criminal referral.”
I stared at him.
“What did?”
He looked down at the report.
“The document he used to prove your death.”
It was a death certificate.
With my name on it.
And according to the issuing county printed across the top—
I had supposedly died three months earlier.
The death certificate was fake. That became clear almost immediately because the county listed on the document had no record of my death, and the certificate number belonged to an entirely different person. But the bank employee who received it overnight had initially treated the submission seriously enough to freeze normal account access while an estate-services representative reviewed the claim.
Dad had not simply logged into my online banking. Several years earlier, after I underwent emergency surgery, I had signed a very narrow financial power of attorney allowing him to pay specific bills if I became medically incapacitated. It had expired after six months. Dad apparently kept a scanned copy and altered the first page to remove the expiration language before sending it with the false death certificate.
The bank did not legally accept the altered document as valid authority over my estate. But an overnight employee made a procedural error and permitted an internal transfer request to enter processing before full verification was complete. That was why my available balance appeared nearly zero even though the recipient bank had not yet finally settled the funds.
Once I reported the transaction as unauthorized and the county confirmed the death certificate was false, the bank froze the transfer. Henderson Resolution Group never received the money. My account balance was restored after the investigation completed, though for several days the funds remained unavailable while the bank reconciled the transaction.
Dad did not know that yet. At 6:12 a.m., he texted Bethany: It’s taken care of. Stop worrying. She replied with three heart emojis and asked whether I had agreed after all. Dad answered: She’ll be angry for a while, but family comes first.
That message mattered because Bethany’s response suggested she had not known how Dad obtained the money. Investigators later confirmed she gave him the debt-settlement payment instructions but believed he intended to use his own savings or persuade me to help. Her desperation had helped create the pressure, but there was no evidence she created the false documents.
The death certificate came from an editable template Dad found online. Metadata from the file later showed it had been created on his home computer less than two hours after leaving my kitchen. He had copied the county seal from a public document, entered my information, and combined it with the altered power of attorney.
Dad’s defense was astonishingly simple. He told investigators he never intended anyone to believe I was permanently dead. He claimed the document was merely a way to “get around automated restrictions” long enough to move the money and planned to explain everything to me afterward.
Nina stared at me when she heard that explanation. “He is describing intent, not disproving it.” Expecting forgiveness after using false documents did not transform the transaction into authorized family assistance.
Then the bank produced the recorded overnight call. Dad told the employee I had “passed unexpectedly while traveling” and that Bethany’s debt needed to be paid immediately because it was an obligation I had promised to settle before my death. I had made no such promise.
He even became emotional during the call. His voice cracked while describing my supposed death, and the employee expressed condolences. Hearing my father perform grief over a daughter who was asleep twenty minutes away affected me more than seeing the account at zero.
But the final discovery explained why the police arrived so quickly. Dad had used the same fake death certificate somewhere else before contacting the bank. At 9:38 p.m., he had uploaded it to my life-insurance company.
And this time, he was not trying to help Bethany.
He had submitted a beneficiary claim for himself.
The insurance claim was for $250,000. Dad was an old contingent beneficiary from a policy I purchased before marriage and had forgotten to update after changing my broader estate plan. He apparently discovered the policy while searching through paperwork I stored at my parents’ house years earlier. The insurer had not paid anything because death verification required independent records.
That second submission transformed the story Dad had been telling. He could no longer plausibly argue that everything he did was merely an impulsive attempt to rescue Bethany. The same fabricated death certificate had been used to pursue money for himself before the unauthorized bank transfer ever began.
Investigators reviewed the two matters separately but shared the relevant digital evidence through proper channels. The bank preserved the altered power of attorney, recorded call, transfer logs, and login history. The insurer preserved the claim submission, uploaded certificate, and IP records. The county confirmed no valid death record existed.
Dad eventually admitted creating both documents. Through his attorney, he said panic over Bethany’s debt triggered a terrible decision and that the insurance claim was intended to reimburse whatever he took from me. That explanation still required pretending a person can secretly claim life-insurance proceeds on a living daughter and call it repayment.
The criminal case resolved through a negotiated plea involving attempted financial fraud, falsified records, and misuse of my identifying information. Because the transfer was stopped and the insurance company paid nothing, actual financial losses were limited, but the attempted amounts and planning still mattered during sentencing.
Bethany was not charged. She entered a legitimate debt-management program instead, sold a car she could no longer afford, moved into a smaller apartment, and took weekend work for nearly a year. For the first time, nobody erased the consequences of her choices with somebody else’s money.
Our relationship was strained, but not destroyed. Months later, she admitted that Dad had spent years teaching her every crisis would eventually become someone else’s responsibility. “I kept waiting for you to fix things because he kept promising you would,” she said. I answered, “And I kept fixing them often enough that both of you believed him.”
Dad and I stayed apart much longer. His first letters focused on Bethany: how frightened she was, how desperate he felt, how families were supposed to protect one another. I returned them unanswered. Nothing about Bethany’s debt explained why he filed a life-insurance claim on a daughter who was still alive.
His eventual apology finally confronted that. I wanted control over money that was not mine, and I decided the reason mattered more than your consent. That sentence did not restore trust, but it was the first one that did not ask me to share responsibility for what he had done.
I updated every account afterward. The expired power of attorney was formally revoked and flagged. My insurance beneficiaries were corrected. Old financial documents were removed from my parents’ house. I also enabled additional verification requirements with institutions holding substantial assets.
Bethany eventually paid off the final portion of her debt without a dramatic rescue. When she sent me a screenshot showing the balance at zero, she wrote, This time nobody had to die on paper. Dark humor, perhaps, but I laughed harder than I expected.
Dad thought “handling it himself” meant finding a way around my refusal. He believed the moral importance of helping one daughter allowed him to erase the consent of another. By sunrise, that belief had collided with recorded calls, digital metadata, bank controls, and a death certificate for a woman answering her own front door.
The strangest part was that my account balance returning to normal was not the thing that gave me peace.
It was realizing I no longer had to prove that my no was reasonable.
Bethany’s debt could be tragic.
Dad could be terrified.
I could have enough money to pay it ten times over.
And the answer could still be no.