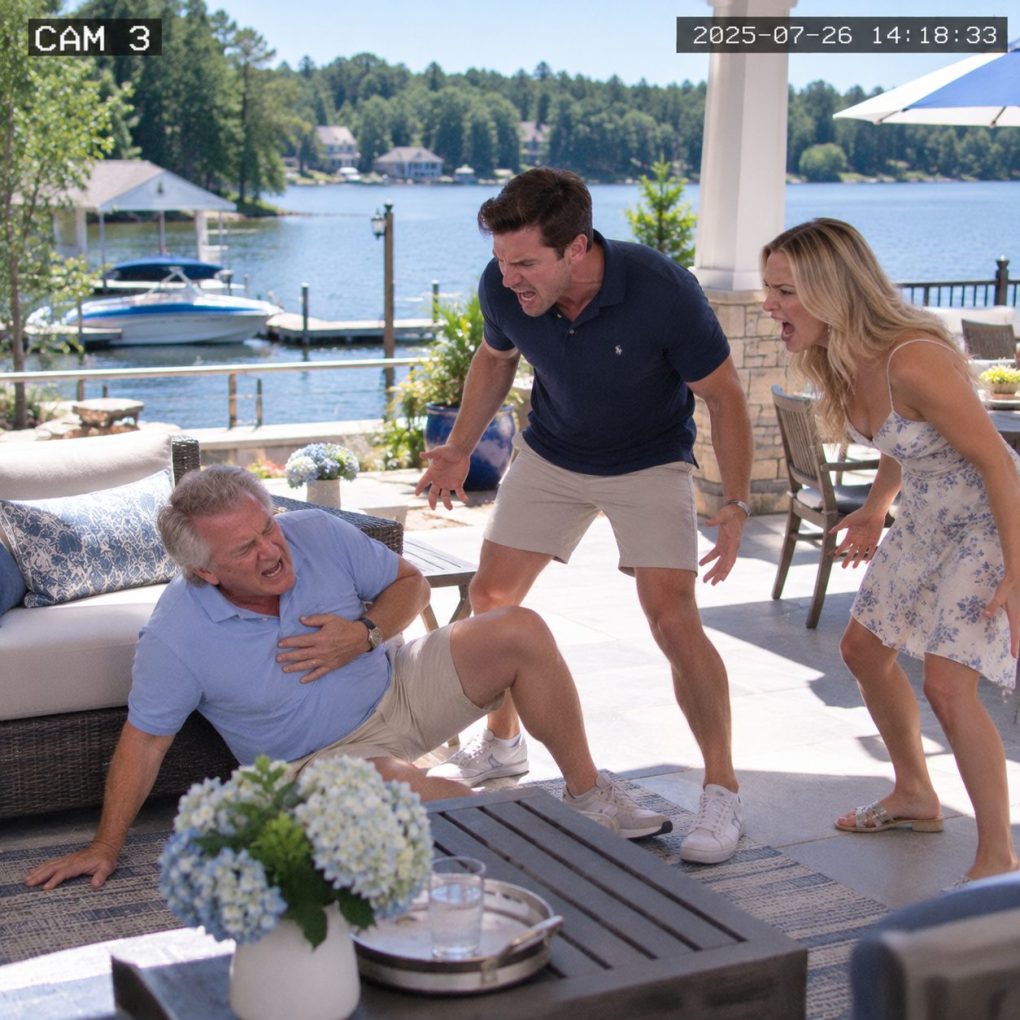
The pain hit so suddenly that the glass slipped out of my hand before I could put it down.
One second, I was standing beside the kitchen island at our lake house in Wisconsin. The next, I was on one knee, gripping my abdomen while something hot and vicious seemed to tear through my back. My son Eric glanced up from his phone. His wife, Vanessa, actually laughed. “Stop faking it, Dad. You just want attention.”
“I need a hospital.” I could barely get the words out. Eric sighed. “You said your stomach hurt yesterday too.” Vanessa raised her wineglass. “Every vacation becomes about you.” I looked at my own son and realized neither of them intended to help me. So I crawled far enough to reach the phone charging beside the sofa and called 911 myself.
Paramedics arrived eleven minutes later. By then, I was sweating so badly my shirt was soaked. My blood pressure had dropped, and one medic’s expression changed when I described the pain radiating into my back. They loaded me onto the stretcher while Eric stood on the porch complaining that the ambulance was blocking two cars.
Forty minutes after I left, while doctors were rushing me through imaging, Vanessa posted a photograph from my dock. She was holding a cocktail beside the sunset. Eric was smiling behind her. The caption read: FINALLY, PEACE. My sister sent me a screenshot before anyone knew whether I would survive the night.
The scan showed a leaking abdominal aortic aneurysm. The vascular surgeon explained that if the bleeding increased, I could die very quickly. Surgery was not optional. Before they took me upstairs, a nurse asked whether I had someone who could make decisions if I became unable to speak. That question terrified me for a reason unrelated to the operation.
Six months earlier, after knee surgery, I had given Eric a limited durable power of attorney so he could deal with contractors and pay several bills while I recovered. My attorney, Laura Bennett, had repeatedly reminded me to revoke it once I no longer needed help. I kept postponing it because Eric was my son. Suddenly, trusting him with even limited authority felt very different.
I called Laura from the hospital bed. “I need Eric removed from every financial role tonight.” She did not ask why until she confirmed I was lucid and understood what I was requesting. Then she arranged the revocation, contacted the institutions that had copies of the old authorization, and told me she would review every action taken under it.
I went into surgery expecting to wake up to questions about my heart, not my house. The procedure saved my life. By sunrise, I was in intensive care, weak but awake. Laura called at 6:18 a.m. Her voice was controlled in the way attorneys sound when the facts are worse than the client expects.
“Thomas, Eric used that power of attorney three weeks ago.”
My chest tightened.
“For what?”
“To support a home-equity application against the lake property.”
I stopped breathing for a moment.
The house was mortgage-free.
Laura continued.
“The requested credit line was $275,000.”
I whispered, “Why?”
“I’m working on that. But the bank also received instructions for where the proceeds would go.”
She gave me the account name.
Vanessa Mercer Holdings LLC.
At 6:34 a.m., Laura called Eric.
By 6:36, both his and Vanessa’s phones were calling me nonstop.
And suddenly the two people who had laughed while I collapsed were very interested in whether I was alive.
Laura’s first job was not to accuse anyone of theft. She obtained the power-of-attorney document, the bank application, and the lender’s verification records. My old authorization had allowed Eric to pay bills, communicate with certain vendors, and handle specified property-management tasks while I recovered from knee surgery. It did not authorize him to borrow hundreds of thousands of dollars against my real estate for his own benefit.
The bank had not funded the loan. Its underwriting department had questioned whether Eric’s authority extended to new secured debt and had requested direct confirmation from me. That request was still pending when I was hospitalized. Laura’s notice of revocation stopped the process before any lien was recorded or money moved.
Eric’s explanation was that the $275,000 was intended for “improvements” to the lake property. That might have sounded plausible if the application had not instructed the lender to deposit funds into Vanessa Mercer Holdings LLC. Vanessa created that company eight months earlier for an event-rental business that was already behind on equipment loans.
When Laura asked Eric why my house was being used to finance his wife’s company, he changed the explanation. He claimed I had verbally promised to help them if the business struggled. I had promised nothing of the kind. I had invested $20,000 when they started it and clearly told them there would be no second rescue.
Then Laura found emails between Eric and the loan officer. One said, Dad doesn’t like complicated paperwork, so deal with me directly. Another said I spent most of my time at the lake and had “started letting me take over financial decisions.” I was sixty-seven, still running my own engineering consultancy three days a week, and had never told anyone I was surrendering control of anything.
Vanessa’s social-media post was not evidence of financial fraud by itself. It did, however, establish that she knew I had been removed from the property by ambulance and was celebrating my absence while the loan application remained pending. Investigators later preserved the original post and messages rather than relying on screenshots alone.
One private message Vanessa sent a friend forty-eight minutes after posting publicly was harder to explain: If he stays in the hospital a few days, maybe Eric can finally finish everything without him hovering. Her friend replied, Finish what? Vanessa answered, The lake paperwork. Don’t worry about it.
The hospital crisis therefore became the point where two separate problems collided. My medical emergency exposed how little they cared about my safety, while Laura’s review exposed what they had been doing financially before I ever collapsed. I refused to combine those facts into some larger conspiracy without proof.
Eric drove to the hospital that afternoon and demanded to see me. I declined. Through a nurse, I told him communication would go through Laura until I was medically stable. He left a voicemail saying Vanessa had “worded things badly” and that the loan was supposed to benefit everyone.
Two days later, the lender produced the preliminary budget Eric had attached. Only $42,000 was allocated to actual lake-house improvements. More than $180,000 was marked for “business consolidation,” equipment debt, and working capital for Vanessa’s company. Another $28,000 was labeled simply family reimbursement.
Then the final attachment appeared. It was a valuation of my lake house accompanied by a handwritten note from Eric: If Dad becomes unable to manage things permanently, refinance first. Sale later if necessary.
Laura read that sentence to me in the hospital.
For the first time since surgery, I cried.
Not because my son had wanted money.
Because he had already begun planning what to do with my home if I stopped being capable of stopping him.
I remained in the hospital for nine days and spent another month recovering with my sister. During that period, Laura formalized the revocation of Eric’s authority everywhere it had ever been provided. My bank, investment manager, insurance carrier, property professionals, and medical providers received updated instructions identifying independent contacts instead.
The lake house remained untouched financially. No loan funded. No lien attached. No title changed. That distinction mattered to me because relatives immediately began exaggerating the story into “Eric almost stole the house.” What he actually did was attempt to use an old limited authority far beyond its intended purpose to obtain financing I had never approved.
The lender referred the suspicious documentation for review, and the appropriate investigators examined whether Eric had misrepresented his authority during the application process. Vanessa’s role was evaluated separately. Her company stood to receive most of the money, and her messages showed awareness of the transaction, but investigators still had to establish exactly what she knew about the legal limits of Eric’s power of attorney.
The matter ultimately resolved without a sensational trial. Eric accepted responsibility for financial misconduct connected to the loan application and misrepresentations about his authority. Because no funds were advanced, the consequences focused on the attempted transaction rather than a completed loss. Vanessa faced separate civil and financial consequences connected to information submitted for her business.
I changed my estate plan too, but not from an intensive-care bed. Months later, after recovering fully and completing an independent capacity review, I removed Eric as successor trustee and financial agent. His inheritance was placed into a professionally managed trust rather than left under his direct control. My daughter became one of the family advisers, but even she could not act alone.
Eric said I was punishing him. I answered, “No. I’m responding to what you did with authority when you had it.” The difference mattered. I did not erase him from my will because I was angry. I removed him from positions requiring a level of fiduciary trust he had already broken.
Vanessa never apologized for the FINALLY, PEACE post in a way I could accept. Her first explanation was that she meant the vacation had become calmer after the ambulance left. Somehow that was worse. Months later, she deleted her social-media accounts and stopped contacting me directly.
Eric eventually apologized without mentioning money. Almost a year after the aneurysm, he sat across from me in Laura’s conference room and said, “I convinced myself that because you had more than you needed, borrowing against it wasn’t really taking anything from you.” I answered, “And when I collapsed?” He looked down. “I thought you were exaggerating because believing that was more convenient.”
That sentence hurt more than the loan application. But it was honest. We began rebuilding limited contact after that, slowly and with boundaries. Forgiveness did not restore his financial authority. Some forms of trust require more than regret.
I returned to the lake the following summer. The dock was exactly where Vanessa had taken that photograph. I sat there alone at sunset with a cup of coffee and listened to the water hitting the pilings. No guests. No business discussions. No one deciding whether my pain was sufficiently convincing.
The strange part was that surviving surgery changed my feelings about the house. I had always imagined leaving it to family as a symbol of continuity. Now I understood that inheritance without boundaries can become entitlement long before anyone dies.
Eric and Vanessa panicked when Laura called because they thought the disaster was the canceled loan.
It wasn’t.
The real thing they lost that morning was the assumption that I would always recover, forgive, and hand them back the same access afterward.
I survived the aneurysm.
I survived the betrayal.
And when I came home, the lake house was still mine.
This time, so were the decisions.