The cashier tried the card twice before lowering her voice.
“I’m sorry. It’s still declining.”
Behind me, my six-week-old daughter began crying in her stroller.
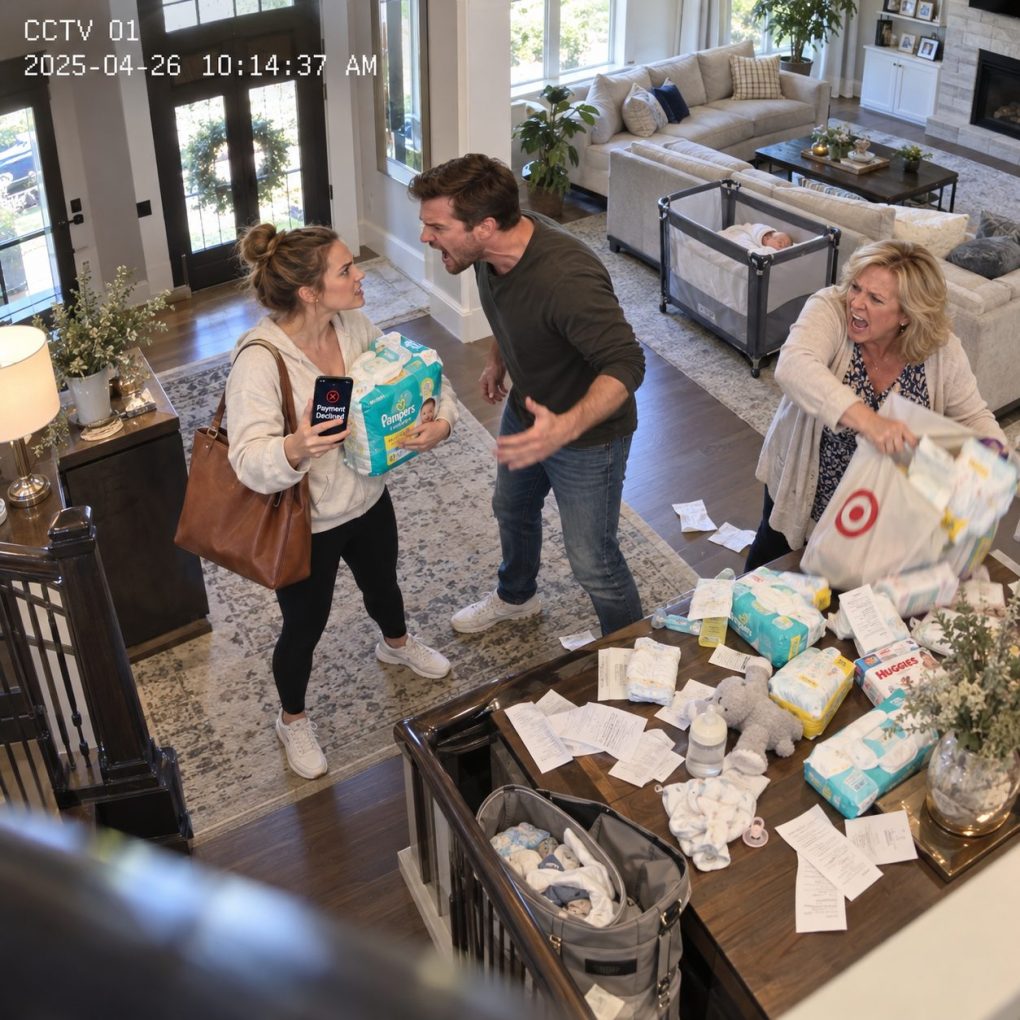
I looked down at the cart: diapers, formula, wipes, infant medicine, groceries. Nothing extravagant. Nothing that should have turned a Tuesday afternoon into humiliation.
“Try this one.”
The second card failed too.
My stomach tightened.
Both cards were connected to the household account my husband, Nathan, and I had used throughout our seven-year marriage. There should have been more than $18,000 available.
I stepped away from the register and called him.
He answered on the fourth ring.
“Nathan, both household cards are being declined.”
“So?”
“I’m buying diapers for Lily.”
A pause.
Then, with astonishing calm, he said, “Not my problem. Figure it out yourself.”
I thought I had misheard him.
“What happened to the account?”
His mother’s voice came through the speaker before he answered.
Margaret was apparently sitting beside him.
“You’ve lived off Nathan long enough,” she snapped. “Useless leech.”
Something inside me went completely quiet.
Nathan did not correct her.
Instead, he said, “Maybe this will teach you what money actually costs.”
Six months earlier, after a difficult pregnancy, I had stepped away from daily work at the interior-design company I founded before our marriage. Nathan had spent those months describing himself as the sole provider.
He liked that story.
His mother loved it.
Neither story was true.
Three years earlier, I sold controlling ownership of my company. Most of the proceeds remained separate property under our prenup, professionally managed by First Commonwealth Private Bank.
I rarely touched the money.
Nathan knew I had investments.
He did not know exactly how much remained because he repeatedly said my “little design payout” was irrelevant compared with his real-estate business.
That afternoon, standing beside a cart of diapers, I stopped protecting his ego.
I called my banker.
“Daniel, it’s Caroline.”
His voice immediately sharpened.
“I was about to call you. We received final clearance this morning.”
Three months earlier, I had placed $2.8 million from my separate account into a temporary reserve while Nathan’s company negotiated financing for a luxury condominium project. I had agreed only to provide proof of liquidity while deciding whether I would participate. No pledge had become final. No money had been transferred.
Nathan had been pressuring me to sign the permanent documents.
I had not.
“Do you still want the reserve held?” Daniel asked.
I looked at Lily.
Then at the declined card.
“Release the funds.”
“To your primary separate account?”
“Yes.”
“All of them?”
“Every dollar.”
I bought the diapers using an emergency card in my own name and drove to my sister’s house.
At 4:06 p.m., Nathan called.
At 4:09, Margaret called.
At 4:12, Nathan called again.
I ignored all three.
Then Daniel sent me a message.
Transfer completed. Reserve withdrawn. Lender notified that no personal liquidity support is available.
Ten minutes later, Nathan left a voicemail.
His voice no longer sounded powerful.
“Caroline, call me immediately. The bank just suspended our closing.”
I listened without replying.
Then another message arrived from Daniel.
There’s something else. The lender sent us a copy of the financial package Nathan submitted. You need to see page 47.
I opened it.
My name appeared beneath a statement promising $2.8 million of personal funds to Nathan’s project.
And beside my name was a signature.
It looked exactly like mine.
I had never signed it.
My attorney, Rebecca Sloan, told me not to accuse Nathan by text, not to confront Margaret, and not to forward the questionable signature around the family. First Commonwealth preserved the lender package, the original reserve instructions, and every authorization associated with my separate account. If someone had represented that I committed money I never approved, we needed original records rather than screenshots and anger.
The project lender had not yet advanced the construction funds. My $2.8 million was never collateral in the legal sense because the final participation documents remained unsigned. But Nathan’s financing package described my reserve as committed sponsor liquidity, making his company appear substantially stronger than it actually was. Once I withdrew it, the lender paused closing and reopened underwriting.
Nathan finally reached me through Rebecca. His explanation was that page forty-seven was merely a “draft commitment” prepared by his finance team and that everyone understood I would sign eventually. Rebecca asked why a draft carried my signature and had been submitted as executed. His attorney ended the conversation before Nathan answered.
The document metadata led to Nathan’s company controller, but the controller produced an email showing Nathan had sent her a scanned signature page from an old tax authorization and instructed her to “drop Caroline’s signature into the final packet so we don’t miss closing.” She had done it. Whether she understood the legal significance became a separate employment and investigative question.
Then I learned why the household cards had failed. Nathan had transferred $17,600 from our joint checking account into an account controlled by Margaret that morning. He told the bank it was repayment of a family loan. I had never heard of that loan, and Nathan could not produce an agreement showing the household owed his mother anything.
Margaret’s messages explained the timing. The night before, she wrote, If Caroline won’t sign the project money over, stop letting her enjoy the benefits of being your wife. Nathan replied, Tomorrow she learns who actually pays for her life. At 8:03 the next morning, he moved the household funds. By noon, my card was declining at the grocery store.
I did not empty our remaining joint accounts in retaliation. Rebecca advised me to preserve statements, secure enough money for Lily’s immediate needs, and let the divorce court sort marital funds properly. My separate investment proceeds remained separate because they had never been commingled with the household account or Nathan’s company.
The lender’s review uncovered another problem. Nathan had listed Margaret as a paid “project consultant” entitled to a $180,000 development fee upon closing. Her actual experience consisted of helping choose finishes for two rental properties. The lender asked for documentation of services. Nathan’s company had almost none.
That did not mean every part of the development was fraudulent. The land existed, permits were legitimate, outside investors were real, and contractors had been engaged. The project’s weakness was financing. Nathan had built the capital stack assuming my money would eventually become available because I was his wife and, in his words, “would come around.”
The closing missed its deadline. One investor withdrew. Another demanded revised terms. Nathan called Rebecca saying he needed only forty-eight hours of access to my reserve or the project could lose millions. She answered that my client had declined to invest and that marriage did not create authority over separately owned capital.
That evening, Rebecca forwarded me one final email obtained from the lender’s compliance review. Nathan had written it six weeks earlier after I again refused to sign the permanent commitment: Once the baby comes, she won’t have the energy to fight about money. I’ll handle it then.
I read that sentence while Lily slept against my chest.
The declined diaper card had not been an impulsive act of cruelty.
It had been leverage.
I filed for divorce the following week. Not because one credit card declined, and not because Margaret called me a leech. Those moments simply exposed a larger reality: Nathan had begun treating financial dependence as a tool for obtaining consent he could not get through an honest conversation.
The disputed $17,600 transfer was addressed through the divorce process. Nathan eventually produced evidence that Margaret had previously lent him money personally, but he could not show that our household account was obligated to repay it without my knowledge. The settlement credited the transfer appropriately rather than pretending every dollar he moved automatically belonged to me.
The lender referred the false signature issue for formal review. Nathan’s company controller cooperated and produced the instruction email, original file, and version history. Nathan later accepted responsibility through a negotiated resolution for submitting misleading financial documentation. The consequences were serious, but nobody fabricated a spectacular collapse beyond what the records supported.
His development project survived in a smaller form. Nathan brought in a new capital partner, surrendered part of his ownership, and sold one parcel intended for a second phase. The original plan would have made him far more money. Losing my $2.8 million did not destroy him; it forced the project to exist without pretending my assets were his.
Margaret never received the $180,000 consulting fee because the revised financing eliminated her contract. She blamed me for months. According to relatives, she repeatedly said I had “taken food from the family.” I found that remarkable from the woman who had watched her son empty the diaper account to teach the mother of his newborn a lesson.
Custody was handled separately from money. I did not try to keep Lily from Nathan because I was angry with him as a husband. The court considered parenting arrangements, stability, and our conduct independently. Nathan eventually became a consistent father, though communication between us remained structured and mostly written.
The $2.8 million returned to my investment portfolio, where it stayed. I did not spend it on a mansion or use it to advertise how wealthy I had secretly been. The point was never that I could outspend Nathan. The point was that I had been contributing to our life voluntarily while he increasingly described those contributions as proof that I depended on him.
Months after the divorce was finalized, Nathan apologized in a way I had not expected. “I thought being the one who controlled the checking account made me the provider,” he said. “I forgot that you choosing not to use your own money was not the same as you not having any.” I answered, “That still isn’t the worst part.” He knew what I meant.
The worst part was the grocery store. Not because strangers saw my card decline. Because our newborn needed diapers, and Nathan deliberately decided discomfort would make me easier to control. When that failed, the false signature revealed he had already been trying a different version of the same thing.
I eventually returned to work part-time, then rebuilt my role in the design business as an investor and adviser rather than trying to recreate my old life exactly. Lily grew into a fearless little girl who had no idea that one ordinary package of diapers once marked the end of her parents’ marriage. I intended to keep it that way.
Nathan and Margaret believed cutting off the household account would show me what my place was. Instead, it reminded me that dependency and trust are not the same thing. I had trusted my husband enough not to keep proving that I could survive without him. The moment he weaponized that trust, I stopped protecting the illusion. One phone call returned my money to my control, stopped a financing package built partly on a promise I never made, and ended the version of our marriage in which my silence was mistaken for permission.