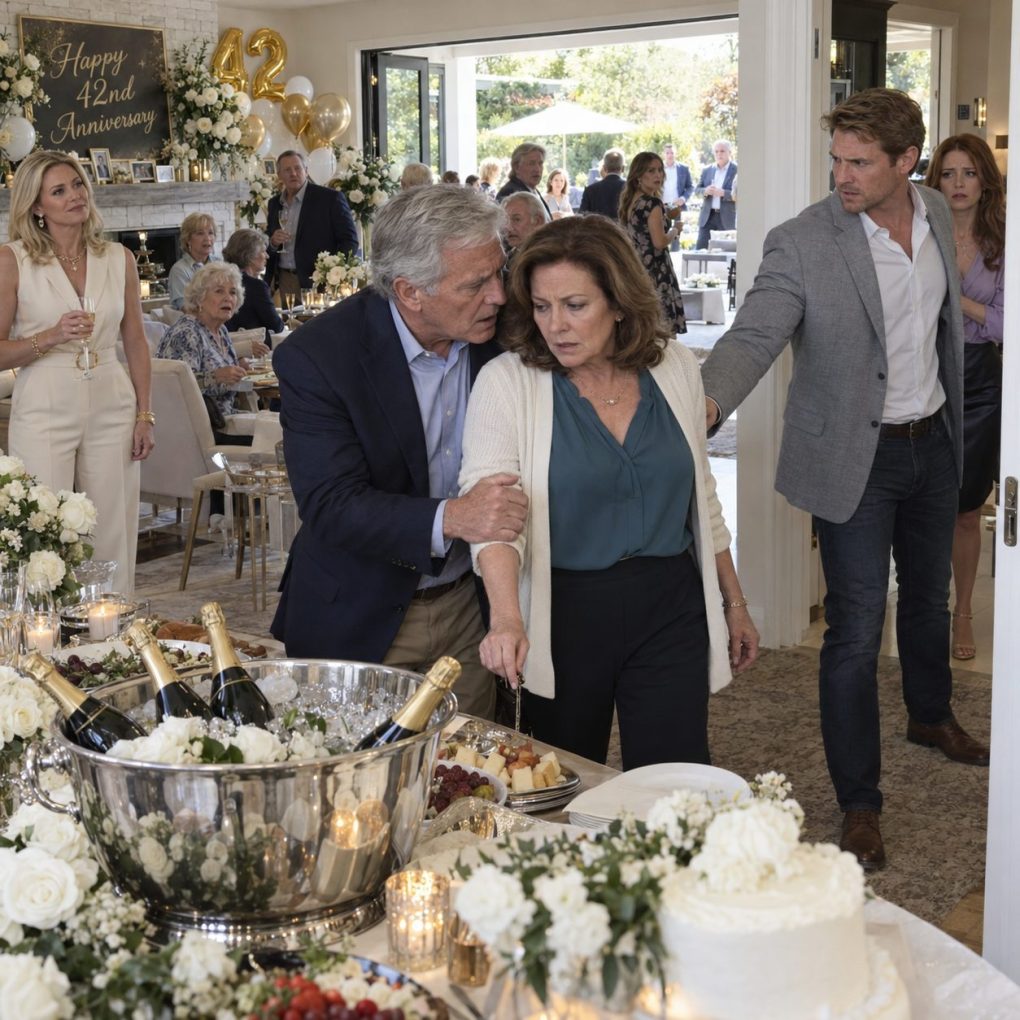
My husband caught my wrist halfway through our forty-second anniversary toast and whispered, “Pretend you’re sick. We’re leaving. Now.” I nearly laughed. Our three children had filled Caroline’s new house outside Philadelphia with forty-two white roses, our wedding photographs, and the song Paul and I danced to in 1984. Then his fingers tightened. “Look under the champagne bucket. Don’t react.”
A bank statement was tucked beneath the linen under the silver bucket. Our names were printed at the top, followed by HOME EQUITY LINE OF CREDIT and a balance of $168,400.
Eight months earlier, after Paul’s knee replacement, we had given our eldest daughter, Caroline, access to our banking app to handle utilities while I cared for him. But we’d never borrowed a dollar against the house we’d spent thirty years paying off. Paul was sixty-seven, I was sixty-five, and that modest brick house was supposed to keep us secure in retirement, not finance somebody else’s dream.
Across the room, Caroline raised her glass beside our son Ben. “To Mom and Dad,” she called, “who taught us everything we know about building a future!” Our youngest, Lucy, stood by the kitchen door, staring at Paul. His phone buzzed. I caught the message on the screen: DAD, PLEASE GET HER OUT BEFORE THE SPEECH.
“I feel faint,” I announced.
Caroline hurried over, her smile slipping. “Mom, not yet. We’re about to do the family tribute.”
“Your mother needs air,” Paul said.
Ben blocked the hallway. “You can’t leave after everything we put into this party.”
“Move,” Paul said, in a voice I hadn’t heard since the night a stranger threatened our children in a parking lot.
Ben moved.
Outside, we sat in our car while I called the lender’s fraud department. The representative froze further withdrawals, secured the account, and opened a dispute, but she couldn’t promise that the existing debt would vanish. The advances had been requested using our online credentials.
Paul pressed his forehead against the steering wheel. “Caroline had my password. I gave her the security codes.”
Lucy called as we pulled away. “I found the statement in Caroline’s home office while setting up the party,” she said, sobbing. “I hid a copy under the bucket and texted Dad because I couldn’t get either of you alone.”
“Did Caroline borrow against our house?” I asked.
“Yes,” Lucy whispered. “And Ben knew.”
“Then why throw us an anniversary party?”
Lucy took a ragged breath. “Because the toast wasn’t the surprise, Mom. They were planning to get your signatures afterward.”
Lucy arrived before breakfast with a folder and the kind of expression I’d seen on her face only once before, when she’d been a teenager admitting she had wrecked our car. She put three items on the kitchen table: transfer records, a mortgage gift letter, and a sheet headed ANNIVERSARY TRIBUTE.
The transfer records showed two advances from our existing home-equity credit line, routed through our checking account and then wired to the closing company for Caroline and Ben’s jointly purchased property. Caroline had changed our banking alerts to an email address she controlled. During Paul’s recovery, we’d let her use the login and had even read her one-time verification codes over the phone when she said a payment wouldn’t go through.
The gift letter was worse. It claimed we had freely given the children $168,400 for their down payment and expected no repayment. Beneath the statement were electronic signatures bearing our names.
“I never signed that,” Paul said.
“Neither did I.”
Lucy nodded. “I found a copy in the printer queue. Ben emailed Caroline that the lender needed it before closing. I don’t know which one forged it.”
The third page laid out a toast thanking us for our “generous early inheritance gift,” followed by a request that we sign a framed family declaration confirming the gift while a videographer recorded.
Suddenly every rose and wedding photograph felt like a prop.
Caroline answered my call on the fourth ring. “You scared everyone last night.”
“Did you forge our signatures?”
“We were going to pay you back when the rental units started earning,” she said.
“You told a mortgage lender it was a gift.”
Ben joined the call and blurted, “I didn’t take your passwords. Caroline handled the banking.”
“But you saw the gift letter,” Paul said.
Silence.
Finally Ben whispered, “I knew you hadn’t agreed. I thought we’d convince you afterward.”
Caroline snapped that we’d promised to help them get ahead and that the lender would “ruin everything” if we disputed the transfers. Ben, for the first time, told her to stop speaking for him.
Then Caroline made her last appeal. “Come over tonight. Sign the acknowledgment. We’ll sort out the money privately, and nobody has to get hurt.”
Paul looked at the forged signatures in front of us. “Someone already got hurt,” he said. “You just haven’t had to look at them yet.”
Our attorney’s first instruction was simple: sign nothing. We preserved the statements and messages, reported the suspected forgery to the mortgage lender, filed a police report, and changed every password and recovery contact. Our own bank was investigating the withdrawals, but because our credentials had been used, it warned us the disputed balance might remain payable while the investigation proceeded.
I hated making payments on money we hadn’t chosen to borrow. I hated even more that I was afraid to answer my children’s calls.
Caroline and Ben came to our kitchen three days later, after our lawyer told them we wouldn’t sign the gift acknowledgment. Caroline was furious; Ben looked as though he hadn’t slept.
“You’d really let your own daughter go to prison over a house?” Caroline demanded.
“You put our house at risk to buy yours,” I said. “And you still think you’re the victim.”
“We were building something for the family!”
“Then why did you hide it from the family?” Paul asked.
Ben stared at the table. “I knew the signatures weren’t theirs,” he admitted. “I didn’t make them, but I let the closing happen.”
Caroline wheeled toward him. “Don’t you dare throw me under the bus!”
“You told me they’d forgive us,” he answered. “You said we could talk them into it at the party.”
Lucy, standing by the doorway, began crying. Caroline pointed at her. “And you destroyed us.”
“No,” Lucy said. “I stopped you from asking them to bless it.”
For the first time, Paul raised his voice. “You were willing to destroy your parents for this house. Don’t blame the child who warned us.”
I had brought both children home from the hospital to this very house. Watching them accuse their sister of betrayal, I barely recognized the adults standing in my kitchen.
We refused to trade silence for repayment. Through their attorneys, Caroline and Ben listed the property for sale. After the mortgage and selling costs, the sale produced $131,600 toward the debt; Ben sold his truck and used savings, while Caroline borrowed against her retirement plan to cover the remaining $36,800 plus interest and fees. Months later, the bank confirmed the credit line was paid and its lien released. The fraud reports stayed on record; forgiveness was never a condition of telling the truth.
Ben eventually sent a handwritten apology. Caroline sent nothing. Lucy still visited every Sunday, although none of us pretended we had the same family.
On our forty-third anniversary, Paul and I ate takeout at our own kitchen table. Our old wedding song came over the radio. He touched my wrist, and for an instant I was back beside that champagne bucket, terrified.
Then he held out his hand.
“Dance with me,” he said.
This time, we didn’t have to run.