“Call someone who cares, Dad. I’m busy,” my daughter said while I lay on wet concrete with a broken hip, the ladder twisted against my porch railing. Behind her, I heard my son-in-law mutter, “Stop doing this every time.” I’d told her twice that I couldn’t stand, but she answered as if I’d merely asked for another errand. Then she hung up, leaving me staring at a gutter I’d been trying to repair because the contractor she promised to call never came.
My name is Robert Whitaker, I’m sixty-eight, and I live outside Dayton, Ohio. I’d called Melissa because she lived ten minutes away, held my medical power of attorney, and had promised my late wife that she’d look after me. I wasn’t asking her to perform surgery or pay a bill. I needed her to come while help was on the way.
The pain made my vision narrow. I dialed 911, told the dispatcher I couldn’t stand, and stayed still until paramedics reached me. At the hospital, X-rays showed a fractured femoral neck that would require surgery the following morning. When a nurse asked whom to contact, I gave her my daughter’s number out of habit, then stopped her before she called.
“Put down my neighbor’s number instead,” I said. “Her name is June.”
June Carter, seventy-one and stubborn enough to frighten a snowplow driver, showed up with my phone charger and the sweater I’d left on the porch. She stayed until the surgeon explained the operation, and when I apologized for dragging her out in the rain, she asked why the daughter I’d spent twenty years helping wasn’t sitting in her chair.
I couldn’t answer without crying.
Melissa hadn’t always been cruel. She’d cared for her mother through chemotherapy and handled my bills after the funeral, and somewhere between those exhausting years and her husband Derek’s struggling remodeling business, every request I made had become, in her words, “another crisis.” Perhaps I’d leaned on her too much. But I’d told her clearly that I’d fallen and couldn’t move.
Before the anesthesiologist came, I made a second call, this time to my longtime attorney, Elaine Porter. I asked her to visit the hospital, bring my existing power-of-attorney documents, and help me appoint someone who would actually answer during an emergency.
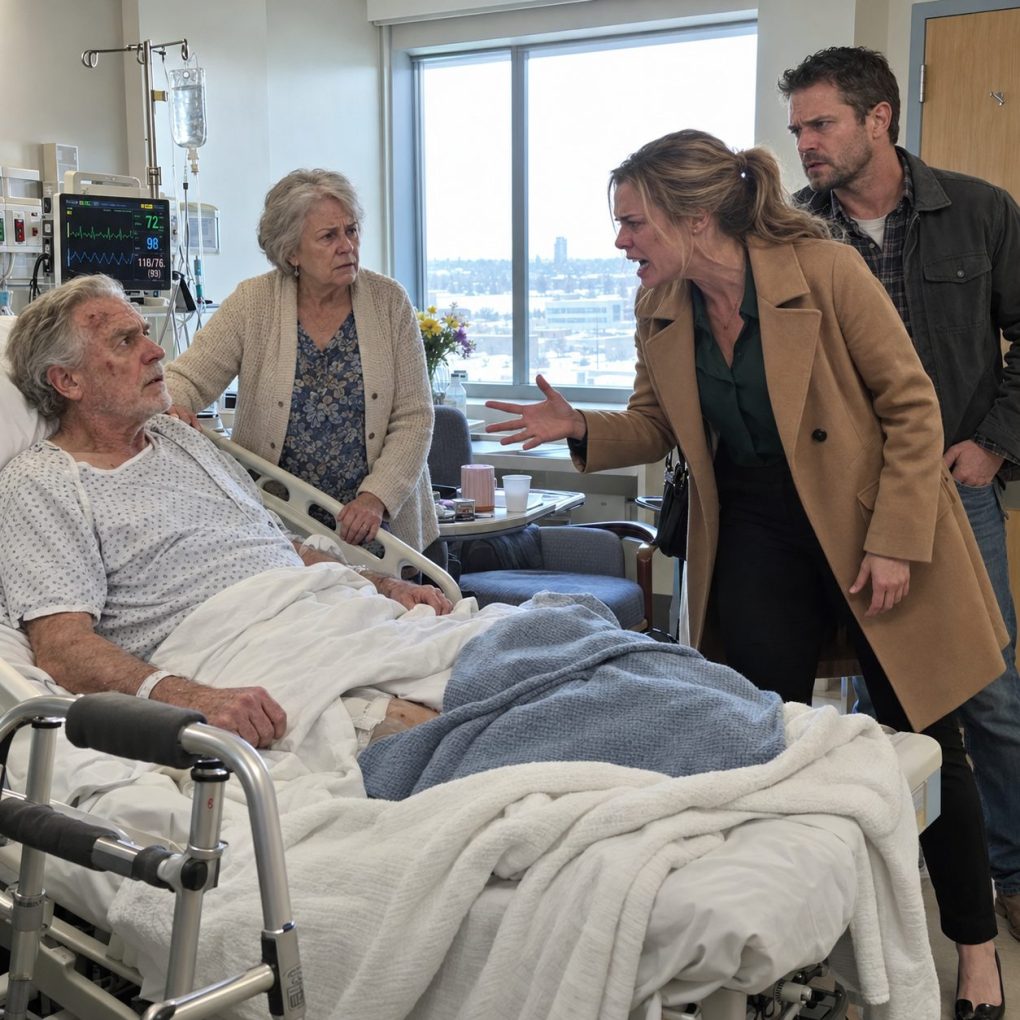
Six days later, Melissa burst into my hospital room, pale with anger, and demanded, “Why did you tell the bank I can’t touch your money?”
She hadn’t asked once whether I could walk.
I was sitting upright with a walker beside the bed when Melissa demanded that I restore her access immediately. Derek stood behind her holding his car keys so tightly his knuckles had gone white.
Elaine had visited after my surgery and helped me revoke the financial and medical powers of attorney naming Melissa, using the required signatures and notices. I’d appointed a licensed professional fiduciary to handle financial matters and June, with her agreement, as my healthcare agent until I could manage everything again. Elaine had also asked my bank for a complete transaction history, because Melissa had once assured me she paid household bills but had stopped providing statements.
What we found wasn’t a few grocery purchases or a misunderstanding about my utilities. Over nine months, $36,400 had gone from my savings into Derek’s remodeling business, often labeled HOME MAINTENANCE, even though he hadn’t repaired anything at my house. The day I was carried into surgery, another $18,000 transfer had been scheduled.
“Those were loans,” Melissa said, lowering her voice when a nurse passed the doorway.
“Show me where I agreed to them.”
“You said you’d help us if things got bad.”
I remembered offering to help with one overdue equipment payment, on the condition that we discussed the amount first. I had never approved emptying the money my wife and I saved for retirement and eventual care.
Melissa sat down hard. She admitted Derek’s business had been losing contracts, that creditors were threatening to seize equipment, and that she had convinced herself the transfers were temporary because she expected new work to arrive. He’d told her my savings were doing nothing, while their children needed a stable home.
“Your grandkids will suffer because you had to prove a point,” Derek said.
I asked him whether he’d known I was injured when he told Melissa to stop taking my calls. He stared at the floor.
Then Melissa said something worse than the insult on the phone: “I knew you said you couldn’t get up, Dad. I just thought you were exaggerating again.”
There was no shouting left in me. I asked them to leave so a physical therapist could help me take the six steps between the bed and the door.
Before she went, Melissa turned back. “If that transfer doesn’t clear by Friday, Derek’s company is finished.”
And for the first time, she looked frightened rather than angry.
On Friday, the transfer did not clear. Elaine had notified the bank that Melissa’s authority was revoked, and the account was secured while the disputed withdrawals were reviewed. Derek sold two work trucks and closed his remodeling business later that summer; the failure wasn’t caused by one blocked payment, but by debts he had hidden from everyone, including his wife.
Melissa sent me seventeen messages accusing me of choosing money over grandchildren. I wanted to answer every one, because their two boys had done nothing wrong, but Elaine advised me to let the records speak first. The bank referred the suspicious activity for review, and my attorney sought repayment through a civil agreement. There was no instant arrest, and I didn’t wake up one morning magically $36,400 richer.
After negotiating with their own lawyer, Melissa and Derek acknowledged the unauthorized withdrawals and agreed to repay the money over four years, secured by proceeds from the sale of equipment and a modest initial payment. I kept the right to pursue further remedies if they defaulted. I also paid a care manager to coordinate my rehabilitation rather than expecting family to do it for free.
The hardest conversation came after I moved home with a walker. Melissa visited alone and stood beneath the porch gutter where the ambulance crew had found me. She said she’d spent three years watching her mother die while I worked long hours, then another two years managing my appointments, and by the day I fell she resented every ring of her phone.
“I was tired,” she whispered. “But I heard you say your hip was broken. I should have come.”
I told her I wished she’d said she couldn’t keep managing my life. I would have hired help sooner. I also told her exhaustion could explain a terrible choice without excusing it, and that taking my savings was another choice entirely.
We didn’t hug. She didn’t receive her powers of attorney back. Yet I allowed her to visit with the boys, because I refused to make my grandchildren pay for their parents’ decisions. June still drives me to appointments, and I pay her gas money even though she always tries to refuse it.
By autumn, I could walk to the mailbox without my cane. Melissa had started a new bookkeeping job, and the first repayment checks arrived on schedule. We speak occasionally, usually about small things, while trust returns—if it ever does—at a pace neither of us can demand.
People say I ruined my daughter’s family over money. Others say I should cut her off forever. All I know is that when I was lying on the ground unable to stand, I wasn’t asking for my inheritance back, or even asking to be loved.
I was asking someone to come.