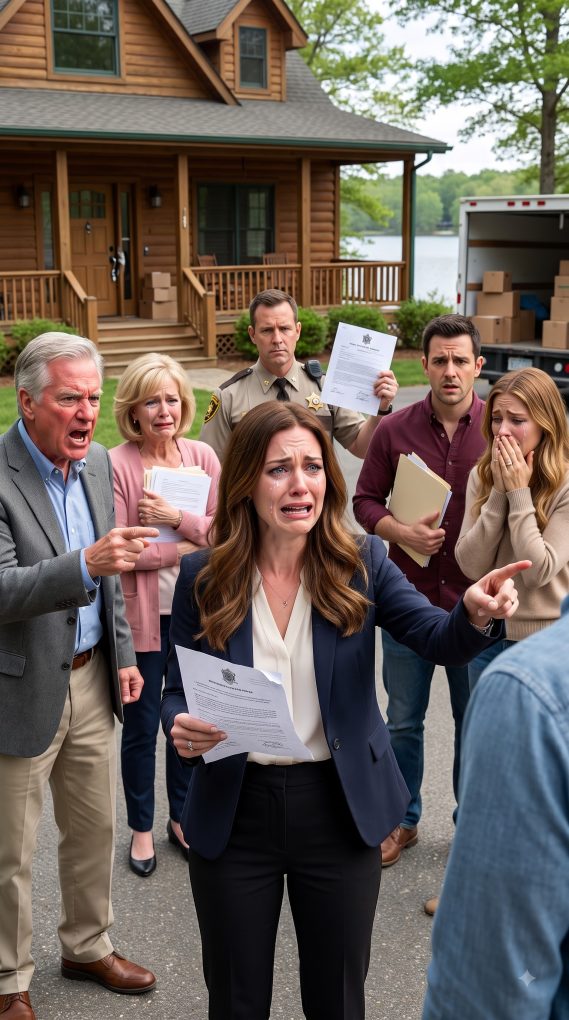
“Ma’am, Deputy Harris, Ottawa County Sheriff’s Office. I’m at your vacation house. Movers are in the driveway, and your father says you don’t own it.”
I gripped my phone. “He’s lying. I told him not to come.”
“Then I need you to explain why he’s changing the locks.”
Three months earlier, Dad handed Ryan a white-ribboned folder at his wedding. Inside was the deed to our childhood home. Everyone applauded. I’d paid $2,350 toward that mortgage every month for five years. Sixty payments. $141,000.
When Dad lost his job, he’d asked me to keep him and Mom from losing their home. I agreed because they were my parents, not because I expected a reward. But nobody had mentioned transferring the house to Ryan while I was still covering the loan.
“You gave him the house?” I’d asked. Dad shrugged. “It’s in my name.” Ryan smiled. “Don’t make my wedding about your money, Claire.”
I stopped the automatic transfers the next morning. Dad called me selfish. Mom said I was tearing the family apart. I didn’t argue. I just kept the receipts.
Last Thursday, Dad called again. Ryan and his wife, Tessa, planned to renovate the old house and rent it out. Dad and Mom needed somewhere to stay. They’d decided my Lake Erie cottage was perfect. Ryan and Tessa might join them.
“It’s only temporary,” Dad said.
“No,” I answered. “It’s my house, and nobody is moving in.”
I followed up by text. No permission to enter. No keys. No exceptions. Dad replied with a single sentence: You’ll regret treating family like strangers.
Now Deputy Harris was standing in my cottage, listening to my father shout in the background. I told the deputy about my refusal and forwarded the messages. He asked whether anyone had a key. I said the only spare was with my neighbor, who checked the pipes when I was away.
“Your neighbor is the one who called us,” he said. “She saw a locksmith force the back door.”
I grabbed my car keys. Before I’d even reached the highway, my screen flashed with missed calls from Dad, Mom, Ryan, and Tessa. They kept coming until the counter read forty-two.
Then Harris called again. His voice had changed.
“Claire, your father has produced a county-recorded deed. It says you transferred the cottage to your brother nine days ago.”
I pulled onto the shoulder. Nine days ago, I’d been at work, two hours away.
“Deputy,” I whispered, “I never signed that deed.”
“Then there’s something else you need to know,” he said. “It was notarized by your mother.”
For a moment, I couldn’t hear the traffic. My mother, Linda Morgan, had been a commissioned notary for years. Her seal certified that someone had signed a document in her presence. I hadn’t.
I hadn’t seen her in nine days.
“Please don’t let them move anything else inside,” I told Deputy Harris.
“We stopped the locksmith,” he said. “But with a recorded deed, this may become a court matter. You need an attorney immediately.”
Two moving trucks blocked the driveway. Dad stood beside them, supervising. Ryan carried a folder. Tessa sat on the steps, crying. The deputies photographed the damaged lock.
“There she is,” Dad snapped. “Tell the officers you agreed to this.”
“I didn’t. And you know it.”
Ryan thrust a photocopy toward me. My name appeared at the bottom of a quitclaim deed. The signature was shaped like mine, but the C had a sharp hook I’d stopped using years ago. It matched the signature on a lender authorization I’d sent Dad back then. My mother had stamped the deed anyway.
“We needed a place,” Ryan said. “You have two houses.”
“I have one house,” I said. “Dad gave you the other.”
His expression hardened. “You don’t understand what we’re facing.”
Tessa lifted her head. “Ryan told me Claire offered the cottage if we helped your parents. He said she just wanted it kept quiet until after the wedding.”
I showed her my text refusing entry. She read it twice, then stood up and stepped away from my brother.
Deputy Harris explained that he couldn’t decide ownership on the driveway. Since nobody had been living in the cottage and I’d reported a forced entry, he documented the incident and told everyone not to interfere with the property while the claims were investigated. Dad finally ordered the movers to leave.
I called Rebecca Sloan, a real-estate attorney a colleague recommended. Within an hour she had the recorded deed, the county filing details, my ownership records, and screenshots of Dad’s threats. She warned me that the forged transfer could be used to seek financing before we got a court order.
“Why would they need financing?” I asked.
Tessa answered before Rebecca could. “Ryan’s restaurant is drowning. The house your dad gave us already has a business loan against it. He promised another loan would save everything.”
Ryan turned pale. Rebecca asked Tessa to forward the papers she’d seen. On her phone was an application for a $286,000 loan from a private lender, with my cottage listed as collateral. The borrower was Ryan. The closing date was Friday.
“The house was never meant to be temporary shelter,” I said.
Dad looked straight at me. “Everything I built went to you kids. You owe us this.”
“I paid your mortgage for five years.”
“And I raised you for eighteen,” he shot back.
My mother finally spoke. “Claire, I told him the deed was wrong. But he said once the loan went through, he’d fix everything.”
Rebecca’s voice came sharply through my speaker. “Linda, did you actually witness Claire sign?”
Mom shook her head.
“Then we need that admission in writing,” Rebecca said. “And we need to stop Friday’s closing before your son borrows against a house he doesn’t own.”
Mom reached into her purse and pulled out a second envelope.
“There’s something your father hasn’t told either of you,” she said.
My mother held the envelope so tightly its edges bent. Dad took one step toward her, but Deputy Harris moved between them.
“Linda,” Dad warned, “don’t make this worse.”
She gave the envelope to me anyway. Inside was a payoff statement for the original mortgage on our old family home, dated twenty-one months earlier, and a stack of account summaries. I checked the address, the loan number, then the balance: zero.
For a moment, I thought she’d handed me the wrong papers. I’d continued sending Dad $2,350 a month for eighteen months after that mortgage was paid off. Eighteen extra payments totaled $42,300. I’d asked twice for statements; Dad always said the lender’s website was down or he would send them later.
“Where did that money go?” I asked.
Ryan stared at the documents. “What do you mean, paid off?”
Mom swallowed. “Your father refinanced the house years ago, then used an inheritance to clear the loan. He said Claire’s transfers were helping him repay other debts. I thought he would tell her.”
“You knew?” I asked.
She looked at the ground. That was my answer.
Dad lifted his chin. “It’s all family money. Ryan needed help opening the restaurant.”
“So you let me think I was keeping a roof over your heads,” I said, “then gave that roof to Ryan. And when I refused to give you mine, you forged my name.”
He didn’t deny it. He only said, “If you ruin this loan, you’ll ruin your brother.”
I looked at Ryan. His wedding suit had cost more than my first car. I’d watched him accept a house I’d helped save without once asking what it had cost me. Now his business was failing, and he wanted my cottage to absorb the loss too.
“You knew the signature wasn’t mine?” I asked.
His silence lasted too long. Finally, he said, “Dad told me you’d come around.”
That was when I stopped trying to convince anyone. I photographed the envelope for Rebecca, forwarded five years of bank transfers, and gave Deputy Harris a written statement. Tessa offered to share the loan application, her messages with Ryan, and the emails that said the cottage deed was already “handled.” For the first time that day, I wasn’t standing alone.
Rebecca sent a fraud notice to the prospective lender and filed an emergency court request to block any transaction involving the cottage. She also prepared a lawsuit to clear the forged deed from the title. The lender suspended the closing while it investigated. Ryan kept calling, but I stopped answering. His emergency wasn’t mine to finance.
The next few weeks were ugly. Dad left voicemails insisting he’d done what any father would do. Mom apologized, then asked if I could just sign a new deed so they could avoid criminal trouble. I told her no. She’d had a chance to say no before pressing her seal onto a document she knew was false.
The recorder’s office preserved the filing materials. Investigators compared the deed with my older authorization form and examined Mom’s notarial records. She admitted, through her attorney, that I hadn’t appeared before her and that she’d notarized a signature Dad supplied. Ryan admitted he knew I hadn’t agreed to transfer the cottage before he submitted the loan paperwork.
There was no magical courtroom speech that fixed everything overnight. The lender refused the loan. The court issued temporary protection against another transfer while the title case proceeded. Months later, after the admissions and evidence were presented, the forged deed was set aside. My name was restored as the sole owner. The damaged door and locks were repaired at Ryan’s expense under a settlement.
The separate fight over my payments took longer. Rebecca explained that helping my parents pay a mortgage hadn’t automatically made me an owner, and that proving an enforceable promise about the old house would be difficult. But the records showed Dad had continued requesting “mortgage money” after the loan had been paid in full. Facing a civil claim, he agreed to repay that $42,300 using proceeds from selling his RV, plus monthly installments. I didn’t recover every dollar I’d given him. I recovered the part he’d taken under a lie.
Mom surrendered her notary commission and paid a fine. Dad later pleaded guilty to an offense involving the forged filing and received probation. Ryan entered a plea agreement after cooperating with investigators. I let the lawyers handle it. I was finished protecting them from consequences.
Ryan eventually sold the old family house. The sale wasn’t the triumph Dad had imagined at the wedding. The proceeds went toward his business debts, legal costs, and getting him out of the mess he’d helped create. Tessa moved into her sister’s apartment and told me she was reconsidering the marriage. I didn’t celebrate. She’d been deceived too.
In late summer, I drove to the cottage for the first quiet weekend I’d had in months. My neighbor, Mrs. Collins, met me at the porch with a fresh spare key. She apologized for not stopping the movers herself. I hugged her and thanked her for calling the police. Without her, I might have learned about the forged deed only after the loan had closed.
I found one final voicemail from Dad while unpacking. “Claire, you’ll regret choosing a house over your family.”
I deleted it. He’d chosen a house over me long before I made a single choice. Actually, he’d chosen two houses: the one I helped pay for and the one he tried to steal.
That night, I sat at my own kitchen table and opened a new folder. It held the corrected deed, the repayment agreement, the police report, and the five years of bank statements I’d once been embarrassed to keep. I was no longer embarrassed. Those pages were proof that being generous had never made me weak.
My phone stayed silent. For the first time, the silence felt like peace.