The silver catering tray saved my stomach.
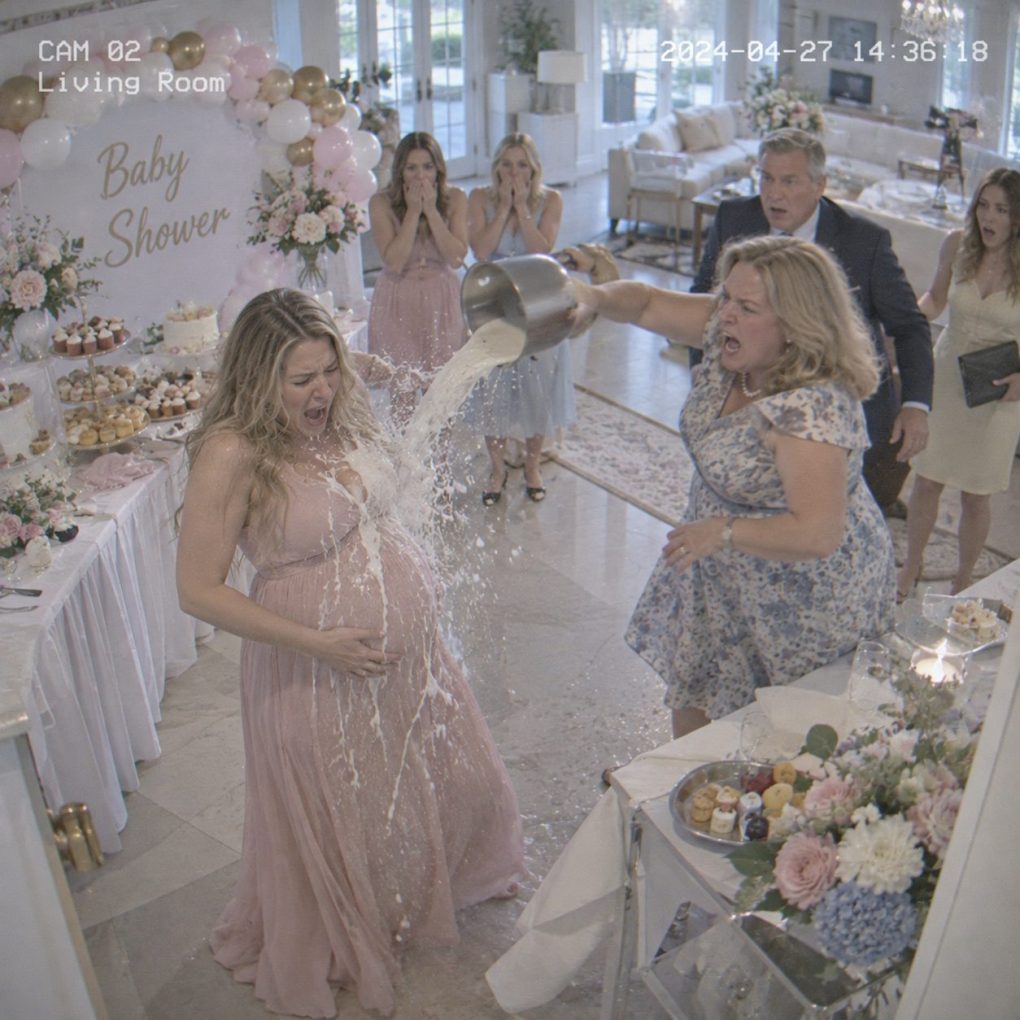
I had just lifted it from the baby-shower table when my mother grabbed the stainless-steel pitcher beside the coffee station and hurled scalding milk toward me.
The tray came up on instinct.
Liquid exploded across the metal, my dress, and the floor.
I screamed and stumbled backward.
Then I felt warmth running down my legs that had nothing to do with the milk.
My water had broken.
I was thirty-four weeks pregnant.
“Call 911!” someone shouted.
Mom did not move.
She stood three feet away, breathing hard, one hand still wrapped around the empty pitcher.
Then she hissed the words that silenced the entire room.
“Sign the loan agreement, or your baby loses everything.”
The papers were already on the gift table.
My father had brought them to my baby shower.
Their family furniture company was collapsing under nearly $600,000 in commercial debt. For months, Dad had been asking me to personally guarantee a restructuring loan using the equity in my townhouse and investment account.
I had refused.
The agreement in front of me would make me liable for up to $425,000 if their company defaulted.
“I said no yesterday,” I whispered.
Dad stepped toward me.
“Claire, stop making this harder than it is.”
My younger sister, Madison, suddenly grabbed the black hard wallet from beside my purse.
Not an ordinary wallet.
A locked travel case containing my banking security token, backup identification, and original copies of several financial documents I had brought because I planned to leave directly from the shower for a meeting with my attorney.
“Put that down.”
Madison backed toward the exit.
Mom said, “Just let her take it.”
That was when I understood.
They had not come hoping I would sign.
They had come prepared for the possibility that I wouldn’t.
Another contraction hit.
My friend Lauren caught me before I fell.
Guests were calling emergency services.
Dad shoved the guarantee toward me.
“Sign it now. We’ll handle everything else.”
I looked at the signature page.
Then at my mother.
Then at Madison disappearing through the side doors with my case.
And I laughed.
Dad stared at me.
“What is funny?”
I took out my phone.
The black case contained a tracker because I traveled frequently with sensitive documents.
A blue dot was already moving across the parking lot.
Dad watched the screen.
His face went pale.
“What is that?”
“My wallet.”
Madison’s dot stopped beside a gray SUV.
Then started moving again.
Lauren whispered, “Claire, the ambulance is here.”
I turned the screen toward Dad.
“You should probably call Madison.”
“Why?”
“Because she just took a tracked case containing a bank authentication device registered only to me.”
His mouth opened.
“And because,” I added, “the venue has cameras covering every exit.”
Dad reached for his phone.
Too late.
A security guard was already running toward the parking lot.
The paramedics rushed me out while Mom shouted that this was all a misunderstanding.
At the hospital, doctors confirmed my membranes had ruptured prematurely. They treated the splash burns, monitored my daughter, and carefully avoided claiming the confrontation alone had caused the rupture.
Then my attorney arrived.
He carried the loan agreement from the baby shower.
“Claire,” he said, “you need to see page nine.”
My parents had not merely wanted my signature.
Page nine already listed my townhouse as pledged collateral.
And beside the property description was a notarized consent dated three days earlier.
My name was signed at the bottom.
I had never signed it.
My attorney, Thomas Reed, immediately told me not to accuse anyone of forgery from a hospital bed. We preserved the loan packet, photographed every page, and contacted the lender so it could secure the original submission records. A suspicious signature was evidence to investigate, not permission to invent the rest of the story.
Madison never made it out of the venue parking lot with my case. Security intercepted her near the SUV after a witness reported seeing her take it from my table. She claimed Mom had told her to put it somewhere safe because I was “having a medical episode.” The security footage showed her leaving quickly while I shouted for her to stop.
The case was returned unopened. Inside were my bank authentication token, passport copy, townhouse deed file, and a sealed envelope containing updated power-of-attorney documents Thomas had prepared. Nothing had been accessed. That mattered because the token alone could not transfer money without my credentials and bank verification.
The lender froze my parents’ refinancing application as soon as Thomas disputed the guarantee. Their furniture company had been struggling for almost eighteen months after two large retail customers failed to pay invoices. The new loan was intended to refinance expensive debt and provide enough working capital to continue operating.
My parents had described me as a willing guarantor. Emails from Dad to the lender said I had “agreed in principle” because I would eventually inherit part of the family business. I had never agreed. In fact, my emails to Dad repeatedly said, I will not put my home behind the company debt.
The notary page raised the most serious question. It stated that I personally appeared three days before the baby shower and acknowledged the collateral consent. I had been attending a prenatal cardiology appointment at that exact time. Appointment records did not automatically prove document fraud, but they gave investigators a concrete inconsistency to examine.
The notary turned out to be someone Dad knew through the business. When contacted, she admitted Dad brought her a signed document and said I had executed it earlier. She had not actually watched me sign. Her notarization therefore did not establish that the signature was mine and created a separate problem for her.
Mom’s behavior at the shower was also documented independently. Several guests saw her throw the hot milk, and the venue preserved camera footage showing the confrontation from the side. The video could not perfectly show where every drop landed, but it captured the pitcher leaving her hand, my defensive movement with the tray, and the immediate chaos afterward.
My doctors treated the burns and monitored the pregnancy closely. They explained that premature rupture can have multiple causes and that assigning it to one stressful event would require caution. What they could say was that I arrived immediately after the confrontation with ruptured membranes and contractions requiring hospitalization.
Then Thomas brought me the lender’s email history. Two days before the shower, Dad had written, If Claire refuses in person, we may need another route. The security device she carries should solve the verification issue.
My stomach turned.
The black case had not been taken randomly.
They knew exactly what was inside.
And one hour later, the lender produced Dad’s follow-up message naming the person he expected to use it with him.
Madison.
Investigators separated the issues instead of treating one awful afternoon as a single giant offense. Mom’s physical conduct, Madison taking the case, the disputed guarantee, and the questionable notarization each required different evidence and different legal analysis.
The lender rejected the guarantee and removed my assets from the proposed collateral package. No lien had been recorded against my townhouse and no loan proceeds had been released based on my property. That prevented the financial damage from becoming much worse.
Without my guarantee, Dad’s company could not qualify for the restructuring loan on the same terms. He eventually sold one warehouse, reduced staff, and negotiated payment arrangements with several creditors. The business survived in a much smaller form instead of being rescued by my home.
The signature review concluded that the image on the collateral consent matched a signature taken from an older family-business document. Dad admitted directing an employee to prepare the packet but insisted he believed I would eventually ratify it. The lender and investigators treated that explanation according to the records, not according to his expectation.
Madison admitted she knew the black case contained my banking token. She claimed Dad told her I had already agreed to the loan and that taking the case would simply help complete paperwork while I was distracted by the baby shower. Her own messages showed she had doubts, including one asking Mom, What if Claire says no again?
Mom’s answer was preserved: Then we stop asking. We make her understand what happens if the company dies. The milk incident happened less than an hour later. Mom later accepted responsibility for her physical conduct and for escalating the confrontation. I stopped trying to make her explanation sound better than it was.
My daughter, Sophie, was born four days after the shower. She spent twelve days in the neonatal unit because she arrived early, but she was breathing on her own by the second day and steadily gained strength. Doctors never told me that Mom had “caused” her prematurity, and I never needed them to say it.
What mattered was that my family had chosen a moment when I was physically vulnerable to pressure me into assuming a debt I had rejected repeatedly. They believed pregnancy, fear, and family guilt would make my boundaries easier to break.
I changed every financial credential connected to the stolen case, replaced the hardware token, moved sensitive documents into secure storage, and revoked any old authorizations my parents might still possess. Thomas also made sure lenders and banks knew nobody in my family could speak for me.
Madison apologized almost a year later. She said, “I thought saving Dad’s company made everything else acceptable.” I answered, “That’s what all of you thought.” We eventually rebuilt limited contact, but she never again received access to my financial documents or accounts.
Mom took longer. The last time we discussed the shower, she said she had been terrified that Dad’s business failure would destroy the family. I told her the business had nearly failed anyway, and the family survived. What almost destroyed us was her belief that saving a company justified using my body, my fear, and my money as leverage.
The black case sits in my closet now, empty except for the tracker that exposed the plan. I kept it because it reminds me how close they came to making desperation sound like authority. They had documents, signatures, a notary page, a business emergency, and a story about family loyalty. What they never had was the one thing every one of those papers required to mean anything:
my consent.