At 12:03 a.m., Patricia Montgomery tried to buy a $6,800 handbag in Manhattan.
Her card declined.
At 12:07, she tried again.
Declined.
At 12:11, my ex-husband called me.
I let it ring.
Our divorce had been finalized less than six hours earlier.
For nine years, Patricia—my former mother-in-law—had carried a black luxury credit card linked to an account in my name. What began as an emergency card after her husband’s death gradually became her private lifestyle fund.
Spas.
Hotels.
Designer clothes.
Restaurants.
Last year alone, she charged more than $118,000.
Every time I objected, my husband, Nathan, said the same thing.
“She’s my mother. Stop counting pennies.”
They were very expensive pennies.
During our marriage, Nathan presented himself as the successful one. His family owned Montgomery Residential Group, a regional luxury-home developer outside Washington, D.C.
I supposedly ran a “small investment consultancy.”
Patricia called it my hobby.
Nathan once joked at dinner that I could stop working tomorrow and nobody would notice.
I never corrected them.
Because before I married Nathan, my grandfather left me controlling ownership of Ashford Capital Partners, a private investment firm he had built over four decades.
I did not manage daily operations.
Professional executives did.
My beneficial interests were protected under our prenup, disclosed appropriately during the divorce, and kept separate throughout the marriage.
Nathan knew I had family money.
He never bothered learning how much.
He also never knew one particularly important detail.
Five years earlier, when Montgomery Residential nearly collapsed after two projects stalled, the company received emergency financing from an investment vehicle called ACP Northbridge Fund III.
Nathan celebrated that deal for months.
He called Northbridge “the smartest institutional money in the market.”
He never realized ACP stood for Ashford Capital Partners.
My firm had quietly committed $4.6 million to keep his family company alive.
I had recused myself from the investment committee’s underwriting decision and never used the financing to control him personally. The loan was legitimate, documented, and managed by professionals.
But I knew.
And Patricia’s luxury card?
That came from a separate personal account.
The moment the divorce became final, my attorney confirmed there was no remaining reason for Patricia to remain an authorized user.
So I removed her.
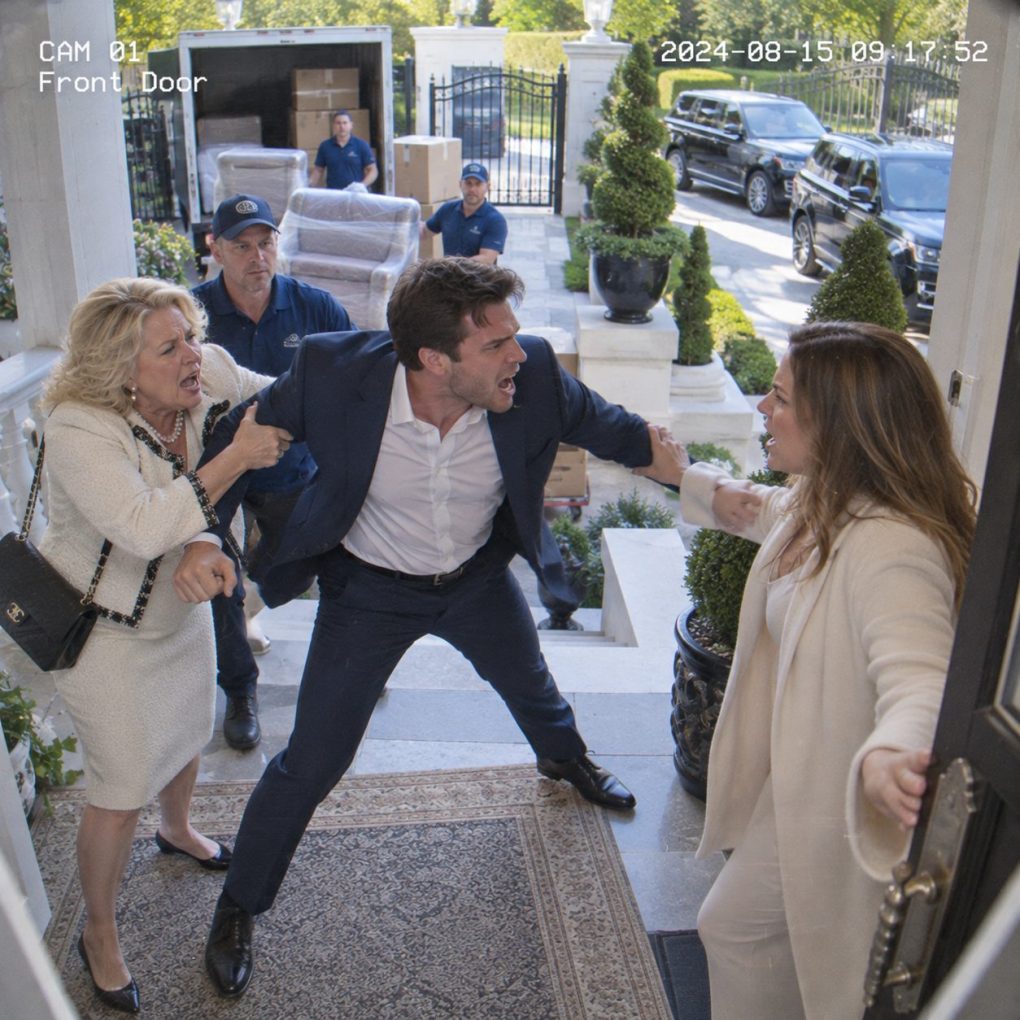
At 5:52 the next morning, someone hammered on my front door.
Nathan.
“Claire! Open this door!”
I checked the camera.
He looked furious.
Behind him, Patricia sat in an SUV wearing yesterday’s clothes.
“Turn Mom’s card back on!”
I opened the intercom.
“No.”
“She has hotel charges! Her reservations are attached to it!”
“She can use her own card.”
Nathan stepped toward the door.
“We’re not doing this. Open up.”
Then he tried the old keypad code.
It failed.
This townhouse had been mine before the marriage.
The divorce decree confirmed it remained mine afterward.
Nathan tried the handle anyway.
I called security.
Then another vehicle pulled up.
A black sedan.
Nathan turned.
Three people stepped out.
My attorney.
Ashford Capital’s general counsel.
And the managing director Nathan had spent five years calling “the man who saved our company.”
Nathan’s face changed instantly.
“Mr. Hale?”
Jonathan Hale looked at him.
Then at me.
“Good morning, Ms. Ashford.”
Nathan went completely still.
He had never heard anyone call me that professionally.
Jonathan opened a folder.
“Since you’re already here, Mr. Montgomery, there’s a separate matter regarding your company’s financing.”
Nathan stared at me.
“What financing?”
I folded my arms.
“The $4.6 million your family has been thanking Northbridge for since 2021.”
He laughed nervously.
“What does that have to do with you?”
Jonathan answered for me.
“Quite a lot.”
Then he handed Nathan a document showing the beneficial owner of the fund.
Nathan read the first line.
His face drained of color.
And for the first time in nine years, my ex-husband understood that the woman he had dismissed as financially irrelevant had quietly been standing behind the capital keeping his family business alive.
Nathan’s first accusation was that I had secretly controlled his family’s company. Jonathan corrected him immediately. Ashford Capital had provided secured financing, not purchased controlling ownership. Montgomery Residential remained owned by Nathan, his brother, and Patricia’s family trust. The loan gave my firm contractual lender rights, nothing more.
The financing had also been approved without my vote. When Montgomery Residential applied five years earlier, I disclosed the family relationship to Ashford’s investment committee and recused myself from the credit decision. Jonathan’s team underwrote the projects, collateral, cash flow, and repayment risk independently. I had hidden the connection socially, not manipulated the transaction.
Nathan demanded to know why I never told him. I asked why he never asked what Ashford Capital actually did. During our marriage, he had attended three dinners where Jonathan sat across from him. Nathan spent each one describing his own projects while assuming Jonathan was merely one of my grandfather’s old business friends.
Patricia finally stepped out of the SUV. Her first concern was still the credit card. “Claire, whatever happened between you and Nathan has nothing to do with me.” I reminded her that the account was mine, she had been an authorized user, and the authorization ended when I chose to end it. She had no contractual right to continued spending after the divorce.
Nathan then threatened to call the divorce judge and claim I had hidden assets. My attorney, Rebecca Sloan, handed him a copy of the confidential financial schedule his own lawyer received during discovery. Ashford Capital, my trust interests, and their separately owned status were all disclosed. The values were subject to protective treatment, but they had never been concealed from the legal process.
That embarrassed him more than the revelation itself. He had signed the settlement after his attorneys reviewed the disclosures. He simply had not paid much attention to assets the prenup clearly excluded from division. To him, “Claire’s family trust” had sounded abstract. He had never bothered connecting it to the investment firm whose managing director he admired.
Then Jonathan explained why he had come that morning. Montgomery Residential had missed two financial covenants during the previous quarter. Ashford’s team had been working with Nathan’s CFO on a waiver. Nothing had been accelerated, and no foreclosure was underway. But the company needed to provide updated financial statements before any waiver could be finalized.
Nathan immediately accused me of engineering the pressure because of the divorce. Jonathan’s expression hardened. “Ms. Ashford does not manage this credit.” He explained that the covenant issues predated the divorce filing and had been documented months earlier. My relationship with Nathan did not erase lender obligations his company had voluntarily signed.
The more serious problem involved Patricia. Company records showed Montgomery Residential had reimbursed several charges made on the luxury card I paid personally, labeling them “executive family hospitality.” I had never requested reimbursement. The total over three years exceeded $74,000.
Patricia insisted those were legitimate company expenses. Some probably were. Others included cosmetic treatments, a Mediterranean cruise, and jewelry purchases that appeared difficult to characterize as business development. Ashford had not discovered them because they were buried inside broader expense accounts below reporting thresholds.
Jonathan did not declare them fraud on my doorstep. He requested supporting records through ordinary lender-information rights because covenant compliance depended partly on accurate financial reporting. Nathan’s CFO would have the opportunity to explain every category.
Then Rebecca handed me one final statement from the divorce financial production. Nathan had personally authorized several of those reimbursements. Beside one $9,400 charge, he wrote: Claire pays the card anyway. Company can reimburse Mom and nobody loses anything.
I looked at him.
“Nobody?”
For the first time since arriving, Nathan had no answer.
The Ashford loan did not disappear because my marriage ended. Montgomery Residential remained responsible for the same financing agreement it had signed years earlier. Jonathan’s team continued dealing with the company through professional channels, and I stayed recused from decisions involving enforcement, waivers, or restructuring whenever my personal history with Nathan created a potential conflict.
The expense review took several months. Some reimbursements were supported as legitimate client dinners, event costs, and travel connected to company functions. Others were not. Patricia repaid amounts the company could not substantiate, while Nathan’s board adopted tighter expense controls and removed family reimbursements from informal approval.
The covenant problem was resolved through a formal amendment. Montgomery Residential sold one undeveloped parcel, reduced distributions to family owners, and agreed to additional reporting while it rebuilt liquidity. Ashford did not seize the company. Good lending was more valuable than revenge, and revenge had never been the reason the loan existed.
Patricia adjusted badly to losing the card. For almost a decade, she had confused my willingness to pay with a permanent benefit attached to being Nathan’s mother. She called twice asking whether I would at least cover existing annual memberships and travel commitments. I declined. Existing charges already properly incurred were paid according to the account terms; future lifestyle spending became her responsibility.
Nathan and I communicated only through attorneys for several months. His anger gradually shifted from the money itself to the humiliation of discovering how little he had understood about my life. He admitted during one mediation session that he had always assumed my quietness about finances meant there was nothing significant to discuss.
I told him, “You mistook not needing applause for not having anything.”
That was probably the closest we ever came to understanding each other after the divorce.
The townhouse remained mine. There was no dramatic fight over it because the prenup and title records were clear. Nathan had lived there during the marriage, but the divorce resolved occupancy properly. Once the decree became final, his old access codes were removed and his remaining belongings had already been collected through an agreed schedule.
My life did not suddenly become more luxurious after the secret came out. I still worked from the same office, drove the same car, and let Ashford’s professional team manage investments. The difference was that I stopped allowing people to interpret privacy as permission to invent their own version of me.
Patricia eventually apologized, though not elegantly. “I thought Nathan was the reason you had that lifestyle,” she said. I answered, “Even if he had been, the card would still have been mine to cancel.” Her face tightened, but she nodded. That distinction mattered more than whether she finally respected my wealth.
Nathan’s company survived. So did he. He was not ruined by learning who stood behind Northbridge. In fact, once the financial theatrics disappeared, Montgomery Residential became more disciplined. Nathan stepped away from several projects, brought in an independent CFO, and stopped treating family expenses like extensions of the business.
The morning after our divorce, he came to my door believing the emergency was his mother’s declined luxury card. Fifteen minutes later, he discovered the woman he had spent years dismissing had been tied to the capital his family credited with saving their company. But the real secret was never that I had millions. It was that for nine years I had been quietly contributing far more—to his mother, his household, and indirectly to the stability around his business—than anyone thought necessary to acknowledge. Once the marriage ended, so did the assumption that my resources would remain available simply because they always had been.