My mother called three days before Thanksgiving and said, “If you come Thursday, your father won’t open the door.”
I stopped in the middle of the grocery store parking lot. “What did you just say?”
“Brooke feels uncomfortable around you,” she replied. “Your sister has had a difficult year. We promised her a peaceful holiday.”
I asked what I had done. Mom sighed as though the question itself proved her point. Then Dad took the phone and said, “For once, Claire, stop making everything about what you’ve done for us.”
I was thirty-seven. Two years earlier, my parents had been eleven days from losing the Colorado house where I grew up. I paid $548,000 to clear their mortgage, $52,000 in overdue taxes and liens, and $80,000 for a failing roof and dangerous electrical repairs. Six hundred eighty thousand dollars. I sold an investment property and used nearly everything I had saved to keep their keys in their hands.
At my attorney’s insistence, we documented the money as a zero-interest family loan, secured by a recorded deed of trust. No monthly payments. Nothing due while they lived there, unless they sold, refinanced, or transferred the property. After the surviving parent died, the debt would be settled from the estate. I had never asked them for a dollar.
“You know I’ve never brought up the money at dinner,” I said.
Dad answered, “Brooke says you make her feel judged just by being there.”
In the background, I heard my sister laugh. Then Mom asked if I could still drop off the pecan pie I usually made.
That was the moment something in me went quiet.
“I won’t be coming,” I said.
Brooke grabbed the phone. “Good. And please don’t send one of your dramatic messages about everything you’ve paid for.”
I ended the call and sent one word to the family group chat.
“Noted.”
By evening, Brooke had posted a photograph of the Thanksgiving place cards. Mine was gone. Dad reacted with a heart. Mom wrote, “So grateful for family.”
I closed the app and went back to work.
At 9:12 the next morning, an unfamiliar number called. The woman introduced herself as Denise Harper from a Denver-area title company. She said she was reviewing documents for a transaction involving my parents’ address.
“Your $680,000 lien appears in the county records,” she explained. “That means we need to verify a release submitted yesterday.”
My hands went cold.
“Ms. Bennett,” Denise asked, “did you sign a document agreeing to erase that debt?”
“No,” I said. “And I want a copy sent directly to my attorney.”
Denise hesitated, then told me the request had come through a file handled for my sister, Brooke Bennett. She would not process the release without confirming it with me. Within twenty minutes, Rebecca Sloan, the lawyer who had drafted our family loan, was studying the suspicious signature.
“That isn’t yours,” she said.
“Of course it isn’t.”
“But whoever submitted it knew the exact loan amount and the recording number. They had access to your parents’ documents.”
Rebecca checked the county records while I called Dad. He answered on the third ring, already irritated.
“Claire, we told you Thursday was not up for discussion.”
“This isn’t about Thanksgiving. Did you transfer the house to Brooke?”
Silence.
Then he said, “We signed some estate-planning papers. Brooke said it would make things easier when we’re gone.”
“Did she tell you it transferred ownership immediately?”
Mom took the phone. “She said it was a way to avoid probate. She promised we could live here for the rest of our lives.”
Rebecca sent me a copy of a deed recorded two weeks earlier. It transferred the house outright to Brooke. There was no reserved life estate and no written promise that my parents could stay.
My stomach turned. They had signed away their home without understanding what the document actually did.
I asked Mom to forward every email Brooke had sent about the property. Three minutes later, eighteen pages arrived. Buried behind a folder labeled “Family planning” was a purchase contract. Brooke had agreed to sell the house to a cash buyer for $1.29 million, with closing scheduled for Monday.
The contract required vacant possession after a thirty-day period.
My parents had not even known the house was for sale.
I called Brooke. She picked up laughing. “What, did Mom finally tell you?”
“You told them they were signing estate papers.”
“They signed a deed, Claire. Nobody forced them.”
“You’re selling their home.”
“I’m unlocking what’s mine. They were always going to leave it to me.”
“And you tried to release my lien with a fake signature.”
Her voice hardened. “That loan was supposed to be a gift. You don’t need the money.”
“I have a signed note saying otherwise.”
“Well, congratulations. You can wave it around while our parents lose their buyer.”
Our parents, I thought. She still talked as though they were belongings we could fight over.
Then Mom called again. She had read the purchase contract for herself. I heard Dad asking Brooke why there was a moving deadline.
Brooke shouted from across their kitchen, “I found you a smaller place. You should be grateful!”
Mom began crying. “You said we could stay here until we died.”
“That was before I found a buyer,” Brooke snapped.
I put the call on speaker so Rebecca could hear everything. Then Brooke delivered her final warning.
“Sign the release, Claire, or I’ll have Mom and Dad out myself. My name is on the deed. This house belongs to me now.”
For a second, all I could hear was my mother crying. Then Rebecca leaned toward the phone.
“Brooke, a recorded deed of trust doesn’t disappear because you uploaded a piece of paper,” she said. “And your parents’ right to challenge that deed doesn’t disappear because you’re holding it.”
Brooke laughed. “You’re her lawyer. Of course you’d say that.”
“I’m also telling you that Claire has not authorized a release. The title company has been notified in writing. Nobody is getting clear title based on that signature.”
The laughter stopped.
I looked at the family group chat. A few hours earlier, my parents had been celebrating the Thanksgiving dinner I was forbidden to attend. Now they were sitting in the kitchen of a house that, on paper, belonged to the daughter preparing to sell it out from under them.
“Mom, Dad,” I said, “stay where you are. Don’t sign anything else. Rebecca will help you find your own attorney. And Brooke, every further conversation about that house goes through counsel.”
Brooke started yelling about how I had always wanted control. I ended the call before she finished.
That evening, Mom forwarded another message from Brooke, dated the day before the deed was signed. It read, “This just avoids probate. Nothing changes until both of you are gone. You’ll always have your home.”
Rebecca read it twice. “Keep the original email,” she said. “That promise matters.”
She explained what we could prove and what we could not. My parents had signed a real deed, so we could not simply declare it invalid. But Brooke’s written promise contradicted the immediate transfer, and the attempted release raised a separate, serious question. We had grounds to challenge both, without forcing my parents into the street.
The title company halted the Monday closing while it investigated the purported lien release. Rebecca notified the buyer’s attorney that my parents disputed the transfer. No one could pretend the $680,000 security interest had vanished.
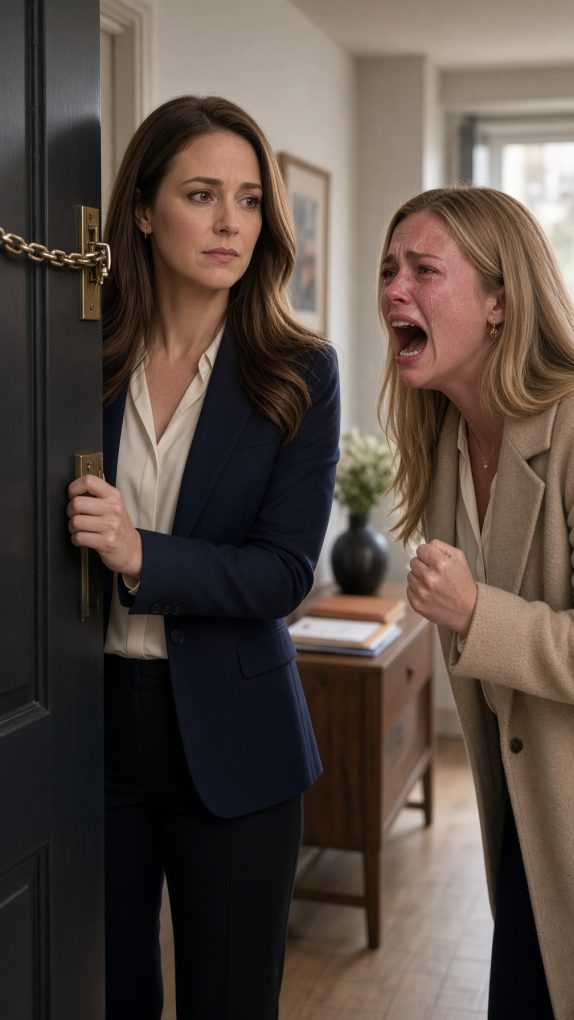
On Thanksgiving afternoon, Brooke came to my apartment uninvited. I opened the door but left the chain on.
“You’re ruining my life,” she said. Her perfect makeup couldn’t hide the panic in her eyes. “I owe money on the fitness studios. My investors want their money back. If this sale falls apart, I’m finished.”
“Then you should have told the truth.”
“I’ll give you a hundred thousand dollars when it closes. Sign the release and keep the rest of your loan between us.”
“You want me to surrender $680,000 so you can collect a sale price for a house you tricked our parents into giving you?”
She looked away. I closed the door.
Later, Dad called. “Brooke says you can make us homeless by demanding repayment.”
“The note allows me to demand payment after a transfer,” I told him. “But I’m not starting a foreclosure. I’m trying to stop the sale and get your title back.”
He was silent for a long time. Then he whispered, “We believed her because believing her was easier than listening to you.”
I had waited years for him to admit something like that. It did not make the pain vanish.
Monday morning, Rebecca filed a civil action challenging Brooke’s deed and seeking an order to prevent another transfer while the dispute was resolved. My parents gave sworn accounts of what Brooke had told them. The judge scheduled a hearing, and the buyer refused to proceed with the title dispute unresolved.
For the first time, Brooke had to answer questions instead of making demands.
Her attorney called ours two weeks later. The buyer had terminated the contract under its title contingency, and the deposit was being returned. The forged-looking release had been referred for investigation. Brooke wanted to settle before the civil case went further.
The settlement took another month. Brooke signed a properly prepared deed returning ownership to our parents. Their independent attorney reviewed it; the county recorded it. My original deed of trust remained in place, and Brooke agreed to repay certain legal and title expenses in installments. I did not agree to withdraw the report about the suspicious release. Whether anyone would face criminal charges was for investigators to decide.
There was no sudden hug, no miraculous reunion. Dad admitted that he had known Brooke wanted to use the house for money, though he claimed he never imagined she would sell it. Mom admitted she had excluded me because she was afraid Brooke would walk out if I attended Thanksgiving.
“I knew it would hurt you,” she said. “I just thought you would forgive us.”
“That’s what you always thought,” I answered.
My parents finally met with a financial counselor, set aside money for property taxes and insurance, and stopped asking me to cover surprise bills. They sent me a handwritten apology without a request attached. I kept it, but I did not pretend it erased everything.
The following Thanksgiving, they asked whether they could bring dinner to my apartment. I agreed on one condition: Brooke was not coming, and nobody would ask me to make peace for the sake of appearances.
Mom arrived carrying a pecan pie she had baked herself. Dad stood awkwardly beside her with three paper plates. For once, neither of them had asked me to provide something before they were willing to sit with me.
We ate at my small kitchen table. It wasn’t a perfect family dinner. It was the first one where I didn’t have to pay for my place.
I had spent $680,000 to save their home. I would not spend the rest of my life buying their respect.