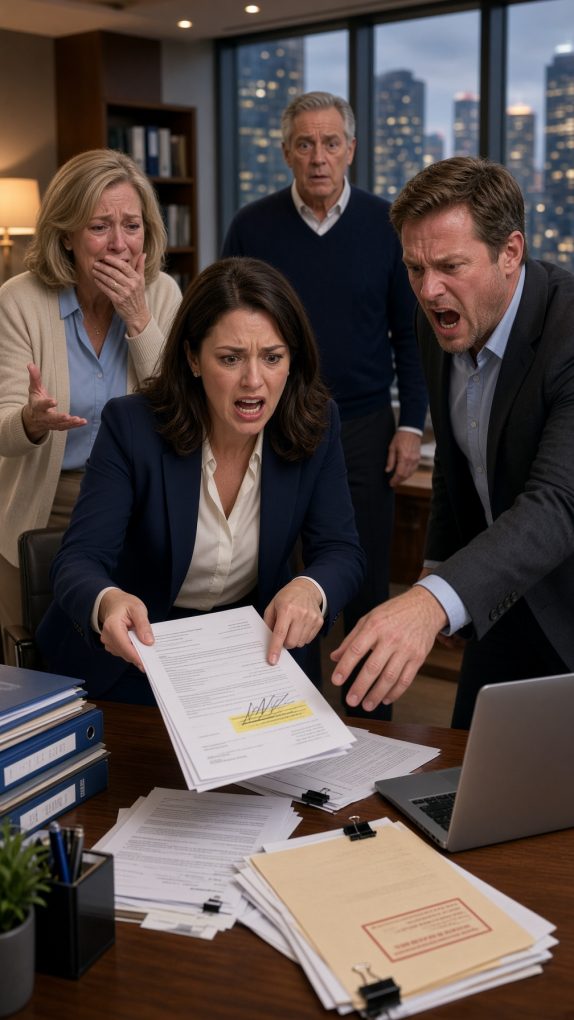
The foreclosure notice landed on my desk at 7:12 on a Tuesday night. My mother had driven forty minutes to my office and was crying so hard she couldn’t unfold it.
“They need seventy-four thousand dollars by Friday, Natalie,” she said. “If we don’t pay, the house goes to auction in twenty-six days.”
My father stood behind her, silent. My younger brother Ethan stood beside the door, scrolling his phone.
Two years earlier, my parents had handed Ethan $400,000 to launch NextNest, a “revolutionary” app that would supposedly change how Americans hired home-repair contractors. They called him a visionary. When I asked for a $15,000 loan to keep my tiny bookkeeping business afloat during its first winter, Dad told me, “You’re resourceful. Figure it out yourself.”
I did. I took weekend shifts, slept on an office couch, and eventually built a company with six employees. Ethan rented a glass-walled office, hired friends as executives, and announced growth milestones no one could explain.
Now NextNest was closed, and the debt had come home.
“We put $260,000 of that investment on our home equity line,” Dad admitted. “The rest came from retirement accounts. We fell behind after Ethan stopped helping with the payments.”
“You stopped paying?” I asked Ethan.
“The market changed,” he said. “What do you want me to do?”
Mom pushed a second document toward me. “Your company has savings. Just cover the seventy-four thousand. We can work out the rest later.”
“That’s payroll money,” I said. “Six families rely on it.”
“We’re your family,” Mom snapped.
I looked at Dad. “Are you asking me to risk their paychecks because you refused to tell Ethan no?”
His eyes filled, but he said nothing.
Ethan finally put his phone away. “You always make everything about how hard you worked. We get it.”
“This isn’t about hard work. It’s about whose name is on the debt.”
I pulled the documents closer. The home equity statement showed months of missed payments. Underneath it lay another packet, stamped NextNest Business Credit Agreement.
I almost slid it aside. Then I saw my address on page eleven.
Borrower: NextNest LLC.
Personal guarantor: Natalie Miller.
A signature sat beneath my printed name, dated sixteen months earlier.
I had never applied for that loan. Never spoken to that lender. Never signed a single paper for Ethan’s business.
I looked at my mother. “What is this?”
She went white. Ethan lunged across the desk to grab the packet.
I got there first.
At the bottom of the page was a witness signature.
It belonged to my mother.
Ethan pointed at the page as though I was the unreasonable one. “It was just a backup guarantee. The bank wanted someone with a steady income. I was going to pay everything back.”
“You signed my name?”
“I had someone sign it. It wasn’t supposed to matter.”
Dad turned toward Mom. “Susan, you knew about this?”
She gripped the edge of my desk. “Ethan said Natalie would understand once the company took off. I only witnessed the paperwork.”
“You witnessed a signature you never saw me make,” I said. “That’s not a misunderstanding.”
Ethan laughed nervously. “Are you seriously going to wreck this family over a form?”
“No. You may have done that sixteen months ago.”
He reached for the folder again. Dad stopped him, an act so small it almost broke my heart.
I photographed every page before handing the documents back to Dad. The business loan was for $115,000, separate from the home equity debt. I had never received a notice because Ethan had listed an email address that looked like mine but wasn’t.
Mom began crying harder. “Please, just make the house payment first. We can discuss the rest later.”
“That money pays my employees,” I said. “I won’t steal their security to hide what Ethan did.”
The next morning, I sat across from attorney Rebecca Sloan. She advised me to dispute the guarantee with the lender, freeze my credit, and file an identity-theft report. By noon, those steps were underway. The lender opened a fraud investigation, but Rebecca warned me that my parents’ foreclosure was a separate problem.
“Even if your signature is fraudulent,” she said, “their home equity loan is still real.”
I called Dad and asked for every financial report Ethan had provided about NextNest. He emailed me a folder containing investor updates, bank statements, and a spreadsheet labeled Final Expenses.
At first, the numbers looked like an ordinary failed startup: advertising, salaries, office rent, software subscriptions. Then three payments caught my eye.
Pine Ridge Creative LLC. Total: $186,000.
Ethan had described the payments as software integration fees, although his own reports said the app was already complete.
I searched the Arizona business registry. Pine Ridge Creative had one listed manager: Brooke Carter, Ethan’s fiancée. Brooke designed interiors. She had never mentioned running a software company.
Rebecca helped me check public property records. Brooke had purchased a townhouse in Scottsdale three weeks after the final NextNest payment. The recorded sale price was $635,000.
The transfers didn’t prove where every dollar went. But they made Ethan’s claim that all the investment money had vanished much harder to believe.
I called him with Dad on speakerphone.
“Did you pay Brooke’s company nearly two hundred thousand dollars?”
Silence.
“Ethan?” Dad said.
“That was a legitimate vendor,” my brother finally snapped. “You wouldn’t understand how startups work.”
“Then show us the contract and the work she delivered,” I replied.
Instead, he hung up.
Dad stared at the property record on my screen. His hands began trembling.
“That closing date,” he whispered. “Susan, that’s the weekend you told me Ethan was sleeping in his car.”
Mom said nothing. And this time, her silence answered everything.
Dad didn’t raise his voice. He simply turned toward Mom and said, “Tell me you didn’t know.”
She stared at the floor. “Ethan showed me pictures of the townhouse. He said Brooke’s father had helped them buy it. I didn’t want to upset you.”
“You let me believe our son was homeless,” Dad said. “I skipped payments on our house because you told me he had nothing.”
“He was under so much pressure,” Mom whispered.
“And I wasn’t?” I asked. “You stood beside him while he put my name on a debt. How much pressure would have made you warn me?”
She couldn’t answer.
That afternoon, I spread the loan statements across my table. Rebecca had confirmed that my parents still owned substantial equity, but only if they sold before the foreclosure sale. My parents were asking me to pay for the privilege of preserving a house they could no longer afford.
I gave them two choices. We could contact the loan servicer, get an accurate payoff, and ask for time to arrange a sale. Or they could keep waiting for Ethan to fix everything. Either way, my company’s money was not available.
Mom flinched. “You’d really let us lose the place where you grew up?”
“I asked you for fifteen thousand dollars once,” I said. “You told me to figure it out. I did. Now I’m offering to help you figure this out without destroying somebody else’s future.”
Dad picked up the phone and called the lender.
The next day, a real estate agent estimated the house could sell for $680,000. After the first mortgage, the home equity loan, accrued charges, and selling costs, my parents might walk away with more than $120,000. Not enough to restore their retirement, but enough to rent a smaller place and avoid a foreclosure on their records.
Ethan called the moment he heard about the listing.
“You’re making them sell their home?” he shouted.
“No. The loan is making them sell it.”
He told me I would regret reporting the forged guarantee. I saved the voicemail and sent it to Rebecca. She added it to the documentation already provided to the lender and investigators.
Two evenings later, Brooke appeared at my office carrying a laptop. She said she had broken up with Ethan after he told her to delete their business messages.
“I knew he was exaggerating what my company did,” she admitted. “I created a few promotional mockups, not a hundred and eighty-six thousand dollars of software. He told me the transfers were his investor distributions, and I let him put them through my business.”
She showed me invoices Ethan had prepared, along with messages instructing her to describe the payments as technology development. One message was worse: Ethan had written that the money would “cover the Scottsdale down payment before anyone checks the books.”
Brooke had benefited from the scheme, and Rebecca made clear that cooperating wouldn’t erase her responsibility. But she turned over copies of the records to the authorities and agreed to discuss restitution through her lawyer. She was putting the townhouse on the market.
When Dad read those messages, he sat down without speaking. Mom reached for his hand, but he pulled away.
“All those nights I worried about him,” Dad said. “He knew we were falling behind. He knew we’d lose the house. And he let me believe there was nothing left.”
For the first time, Mom didn’t defend Ethan.
Eleven days after the house was listed, a cash buyer made an offer. The lender agreed to postpone the auction while the documented sale proceeded. Rebecca reviewed the payoff figures, and the closing took place before the new deadline. My parents moved into a modest two-bedroom rental across town. They left with roughly $127,000 after the debts and costs were paid.
I helped Dad carry the last box to his car. He stopped at the doorway and looked back at the empty living room.
“I kept thinking the house meant I’d succeeded as a father,” he said.
“You don’t have to own it to be my dad,” I replied. “But you do have to stop asking me to pay for Ethan’s mistakes.”
He nodded. “I know.”
The investigation lasted months. Brooke’s records helped establish that NextNest money had been diverted, and the separate lender eventually removed the disputed guarantee from my credit record. Ethan was charged with fraud and forgery. He later pleaded guilty and was ordered to pay restitution; the sale of Brooke’s townhouse recovered only part of what had disappeared.
Mom had to answer questions about witnessing my signature. Her lawyer advised her to cooperate, and she did. Our relationship didn’t recover simply because the paperwork was resolved.
Nearly a year later, she asked to meet for coffee. She arrived with no request for money, no explanation about Ethan’s difficult childhood, and no promise that everyone could be a family again by Christmas.
“I gave your brother every chance,” she said. “Then I tried to make you responsible for the consequences. I called that love, but it wasn’t fair to you.”
I waited. For once, she didn’t fill the silence with excuses.
“I’m sorry I helped him use your name. And I’m sorry I didn’t believe you needed help when you were starting out.”
I couldn’t tell her everything was forgiven. Instead, I said, “If we rebuild this, it starts with the truth. No secrets. No money requests. No asking me to protect Ethan.”
She agreed.
That evening, I went back to my office. My six employees were finishing payroll, laughing over takeout at the conference table. Every one of their paychecks was funded. My business was intact. And for the first time in years, I wasn’t afraid that protecting my own life made me a bad daughter.
My parents had wanted me to save their house. What I saved was something they’d taught me to sacrifice: the right to say no.