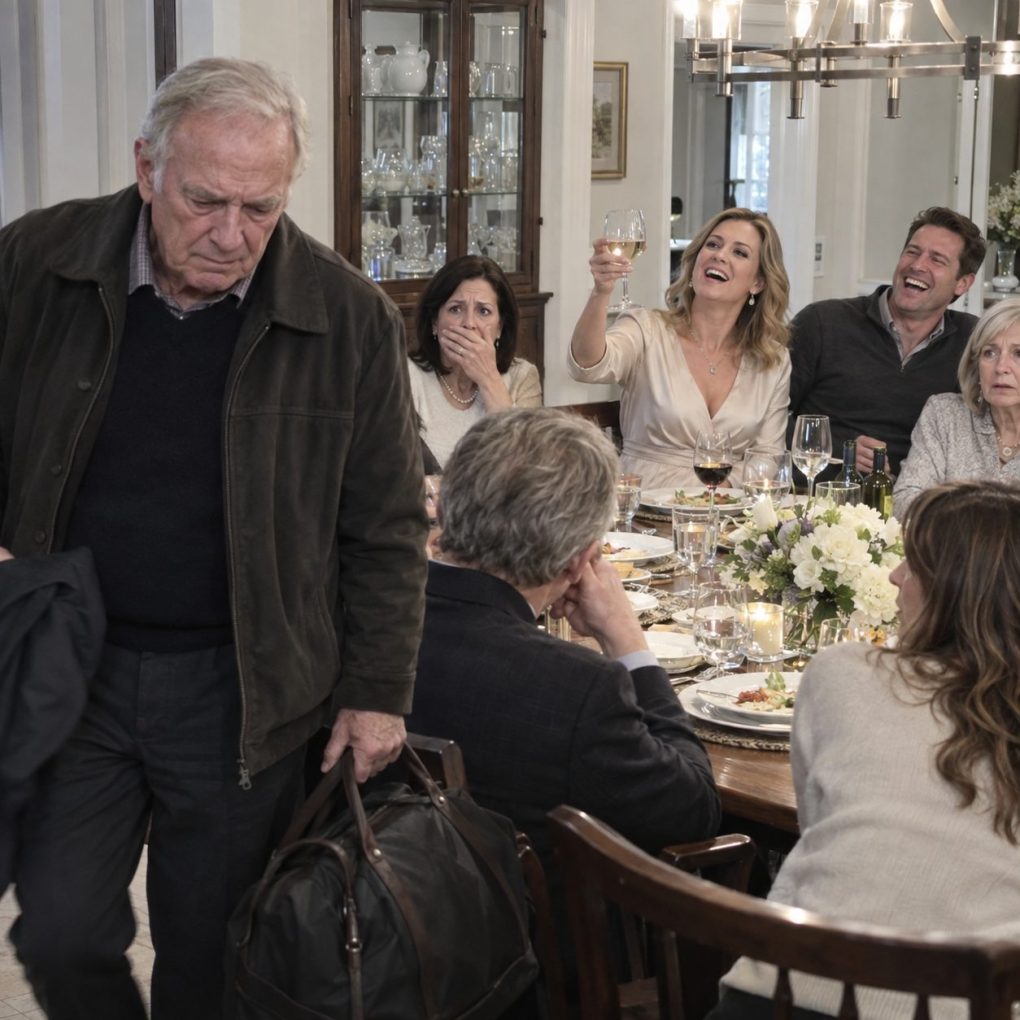
To the Bank of Dad, Kelsey announced, lifting her champagne glass. Always open, always paying! Twelve relatives burst into laughter. My son Brent laughed hardest, slapping the table. I was standing beside the birthday cake I’d bought for my granddaughter, with a mortgage receipt folded inside my jacket.
For eighteen months, I’d paid $1,850 directly to the lender on Brent and Kelsey’s house in Des Moines. Brent had told me his construction management job was unstable. I was sixty-eight, retired from an auto repair shop, and the payments were quietly consuming the savings my late wife and I had built.
Kelsey pointed at my faded blazer. Look at him. He won’t spend fifty bucks on himself, but he’ll fund our entire lifestyle! Brent raised his glass again. Dad loves feeling needed. My sister Marion stopped smiling. Across the room, nine-year-old Abby lowered her eyes.
I set down my untouched cake plate. I’m glad the joke was worth it, I said. Brent waved dismissively. Relax, Dad. We’re family. Nobody means anything by it. I smiled at Abby, kissed her forehead, and walked out without raising my voice.
At home, I opened eighteen bank confirmations. Thirty-three thousand three hundred dollars, every cent sent directly toward a mortgage that wasn’t mine. I’d postponed replacing my furnace and turned down a trip with old friends because Brent kept saying one more month would save his family.
At 10:06 p.m., he finally texted. Hey, mortgage is due Monday. Did you send the payment? I stared at the screen. No apology. No question about why I’d left. Just the usual expectation. I typed four words: The bank is closed.
His reply came immediately. Very funny. Seriously, Dad. Kelsey called twice, then left a voicemail saying I couldn’t punish Abby and her little brother, Owen, over a harmless toast. I didn’t answer. Their children deserved stability, but I wasn’t the person who’d agreed to borrow against that house.
An hour later, another message arrived, this one from my credit union. It asked me to complete identity verification for a $92,000 personal loan with Brent listed as the primary borrower. I had never applied for a loan, and I’d never agreed to cosign one.
I called the credit union’s fraud line and asked them to flag the application. The representative confirmed no loan had been funded and no signature from me had been accepted. She advised me to check my credit files and put a freeze in place.
As I ended the call, Brent sent a photograph of documents laid across his kitchen counter. Beneath it he wrote: We already paid the deposit on Kelsey’s new bakery. We need your signature by Tuesday. Don’t embarrass us again.
I slept badly, imagining my name attached to debt larger than I’d ever borrowed. The next morning, Marion arrived with coffee. When I showed her the loan request, she stopped stirring. They never asked you? I shook my head.
The credit union said the incomplete application was under review. I froze my credit with the three major bureaus and spoke with an attorney. She told me to preserve messages, dispute unauthorized inquiries, and sign nothing under pressure.
By noon, Brent arrived with Kelsey and a thick folder. He began with an apology so rehearsed I could hear the commas. Kelsey hadn’t meant the toast, he said. Then he slid the loan papers toward me and uncapped a pen.
I pushed it back. Why did you list me as a borrower before asking? Kelsey said their bakery had secured a storefront, and the lender needed someone with stronger credit. We already put down seven thousand dollars, she said. If you refuse, we lose the place.
I asked where the deposit had come from. Brent admitted he’d received a $19,000 work bonus. He’d been back on a full salary for nine months, he added, suddenly studying the floor. Nine months, I repeated. He’d requested nine mortgage payments while hiding that from me.
Kelsey folded her arms. Your money was just sitting there, she said. We’re trying to build something. I told her my savings weren’t idle simply because I wasn’t buying a business. They were for emergencies and the retirement I’d worked forty-four years to earn.
Brent snapped that I’d never supported his dreams. Marion stepped forward, but I raised my hand. I reminded him I’d paid for his trade-school tuition, helped with his first truck, and transferred $33,300 toward his mortgage. His face reddened. That’s what parents do, he muttered.
No, I replied. Parents teach their children how to stand, not keep paying for the ground beneath them. Brent demanded to know whether I wanted Abby and Owen to lose their home. I asked why he’d spent his bonus on a bakery deposit instead of protecting their mortgage.
Kelsey grabbed the folder and stormed toward the door. Brent stayed behind, looking shaken. Then he admitted he’d used an old copy of my identification from our family estate paperwork to start the application. He insisted he’d planned to obtain my signature later. I told him that didn’t make it acceptable.
My attorney sent the credit union a written notice that I had not authorized the application. That evening, Abby called on her tablet. Grandpa, Mom says we might have to move because you’re mad. I held my breath and answered carefully: Grown-ups made money decisions, sweetheart. None of this is your fault.
Brent kept calling to negotiate. He suggested half a mortgage payment, then three more months, then a loan. I said no each time. The mortgage was in his name. My help had been voluntary, and I couldn’t keep financing decisions he wouldn’t discuss.
The credit union closed the incomplete application after confirming I hadn’t authorized it. My attorney helped dispute the resulting credit inquiry and document the use of my identification. There was no instant punishment. I focused on protecting my accounts.
Kelsey lost part of the bakery deposit when the storefront agreement fell through. She kept her smaller home baking operation and began planning expansion around what she could afford. Brent sold a recreational ATV and adjusted their household budget. Their mortgage remained current, though money was tighter.
He came to my house in February carrying the eighteen payment confirmations I’d emailed him. He held them up: $33,300. He said, I kept calling it help. I never looked at what it cost you. Then he asked why I hadn’t told him to stop sooner.
Because you kept telling me you were nearly through the worst, I answered. And because I trusted you. His eyes filled, but I didn’t rush to comfort him. He needed to sit with the fact that he’d mistaken my silence for unlimited permission.
Kelsey apologized. At first she blamed the party atmosphere. I told her the toast wasn’t the only problem. She had publicly mocked a man whose retirement savings had kept her house afloat, then treated his signature like something she could collect afterward.
She called again two weeks later and apologized without mentioning the loan. I thanked her. Trust, I explained, would depend on what happened after the apology, not how moving it sounded. I still went to Abby’s school play, but I stopped discussing my finances with either parent.
I replaced my failing furnace and booked the fishing trip I’d postponed twice. I also set aside money for Abby and Owen’s education in accounts their parents couldn’t treat as operating cash. I wanted the children to have opportunities without growing up believing love was a monthly transfer.
Brent began visiting on Sunday afternoons to help repair my back fence. We talked about baseball and his work. Sometimes we talked about money, but never as a request. The first time he thanked me without adding a favor, I realized how long I’d waited to hear it.
At Abby’s next birthday, Kelsey raised a glass and started to propose a toast. The room went quiet. She simply thanked everyone for coming. I smiled at my granddaughter and passed her the cake. The Bank of Dad was closed. Her grandfather, with boundaries, was still there.