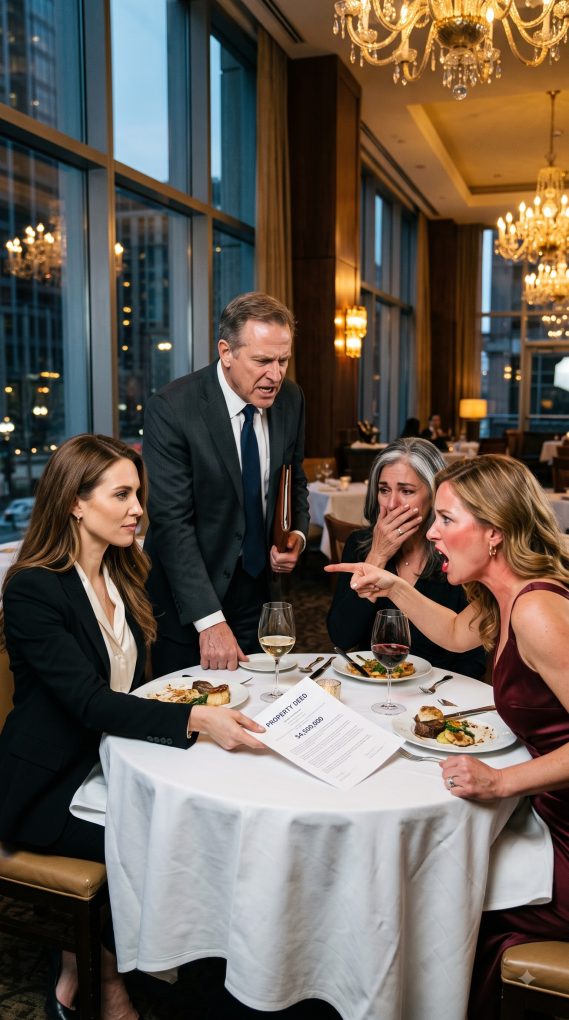
The bank investigator called ten minutes before I walked into the restaurant.
“Ms. Bennett, if anyone asks you to sign a business-loan document tonight, don’t,” he said. “We’re reviewing a guaranty that carries your name.”
My stomach tightened. My father had insisted on this dinner, calling it a family emergency. He wouldn’t explain why.
Inside, Dad sat with a leather folder beside his plate. Mom kept twisting her wedding ring. My older sister, Madison, was already sipping expensive wine.
“You’re late,” Madison said. “Some of us have actual careers.”
I sat down without taking off my coat.
Dad pushed the folder toward me. “Madison’s company needs a temporary extension on its credit line. There’s one acknowledgment the lender wants. Just a signature.”
“An acknowledgment of what?”
“Routine paperwork,” Mom said.
I opened it. The heading included the words PERSONAL GUARANTY. I closed it again.
“No.”
Madison laughed. “You haven’t even read it.”
“I read enough.”
She leaned forward, her gold bracelet sliding against the table. “Still doing that little computer thing? You’re acting like somebody’s asking you to finance a skyscraper.”
Ten years earlier, our parents had spent nearly $300,000 on her private university education and graduate degree. When I asked for help with community-college tuition, Dad told me money didn’t grow on trees. I worked night shifts in a hospital records department, lived on ramen, and learned to code on a secondhand laptop.
Mom had never once asked what the software actually did. Madison still called it an app, although several hospital systems depended on it to keep their overnight shifts staffed safely. To Madison, I was still the kid who couldn’t afford a decent winter coat.
“Why should I sign for your business?” I asked.
“Because family helps family,” Dad snapped.
I reached into my bag and placed one sheet of paper in front of Madison.
She squinted at the address. Then she noticed the purchase price.
$4.5 million.
It was the recorded deed to my Chicago penthouse, bought outright after I sold a controlling stake in the software company I had built.
Madison’s smile disappeared.
“You own that?” she whispered.
“Yes.”
“Why didn’t you tell us?!”
I laughed. Not because it was funny. Because for the first time in my life, they were upset that I had succeeded without asking their permission.
Dad grabbed the folder from between us.
“Put that deed away,” he said sharply. “The bank can’t see it.”
I looked at him. “Why?”
Mom’s face crumpled.
“Because,” she said, almost too quietly to hear, “you already signed the first guaranty.”
“I signed what?” I asked.
Mom stared at the linen tablecloth. Madison started gathering the papers, but I put my hand on the folder.
“Leave them.”
Dad lowered his voice. “Nora, this can still be handled privately.”
“Then tell me what you did.”
For nine months, it turned out, my name had been attached to a $780,000 business loan for Madison’s luxury-hospitality consulting firm. Dad had pledged the family house as security. I had supposedly guaranteed repayment if her company failed.
Only I had never seen the loan.
Madison reached for her wine. Her hand shook hard enough to rattle the glass.
“It was a short-term arrangement,” she said. “We expected a major hotel contract.”
“Who signed my name?”
Silence.
I dialed the investigator, Daniel Price, and put him on speaker. After verifying my identity, he confirmed that the lender was reviewing the guaranty because Madison had requested another payment extension. The number listed for the guarantor had stopped working, and an independent verification call had reached me instead.
“The electronic signature was completed on February twelfth,” he said. “We have a driver’s-license image and an audit trail.”
I remembered February twelfth. I’d been speaking at a healthcare technology conference in Seattle.
“Where was the verification code sent?”
Price hesitated. “I can discuss the full record with you through our secure process. But we have reason to question whether you personally authorized this.”
Mom started crying.
Madison hissed, “Hang up.”
Instead, I told Price I disputed the signature, asked for instructions to submit a written fraud report, and ended the call.
“Was my license in that file?” I asked Mom.
She nodded. “I kept a scan from when you helped your father with the insurance paperwork.”
I felt as though someone had pulled the floor out from under me.
“You used my identification?”
“Madison said you would approve once everything worked out,” Mom whispered.
“I didn’t ask whether Madison approved. I asked why you did it.”
Dad rubbed his forehead. “We didn’t think it would go this far.”
“Your house is collateral. My name is forged. How much further did you think it could go?”
Madison finally admitted that the hotel contract had collapsed, three employees had quit, and the loan was seriously overdue. Tomorrow was the deadline to cure the default before the lender could begin enforcing its rights against my parents’ house.
Then I noticed something on the company disclosure attached to Dad’s folder.
The ownership section listed Madison Bennett at forty percent.
Carol Bennett, my mother, held the other sixty.
I turned the paper around.
“You told me this was Madison’s business.”
Mom stopped crying.
“She needed a partner,” she said.
“No,” I replied. “She needed someone whose retirement savings and house she could risk.”
Dad stared at the page as if he’d never seen it.
Madison reached across the table. “Nora, please. If you don’t sign tonight, Mom loses everything.”
For the first time, I understood the dinner invitation.
They hadn’t brought me there to save my sister.
They had brought me there to take responsibility for my mother’s debt.
My mother’s debt.
I looked at the three people who had spent years treating my work like a hobby, then nine months treating my identity like an asset they could borrow.
“You forged my signature,” I said. “And you brought me here to make the forgery real.”
Before I stood, Madison explained the sixty percent. Her firm couldn’t qualify for financing alone, so Mom had invested her retirement savings and taken control. She expected Madison’s promised hotel contracts to make them both wealthy. Dad had agreed to risk the house without knowing his wife controlled the company.
Madison shook her head. “You’re rich now. You could pay this off without noticing.”
“That doesn’t make it yours.”
Mom reached for my wrist. “Nora, I carried you for nine months.”
“And I carried myself through college,” I said, pulling away. “You didn’t even pay for the textbooks.”
A waiter approached with our entrees. Nobody touched a plate.
I photographed every page in the folder, including the company disclosure, the loan number, and the acknowledgment they wanted me to sign. Dad tried to object.
“You gave me these papers,” I told him. “Now I’m keeping a record of them.”
Outside, I called my attorney, Rebecca Sloan. She listened without interrupting, then told me to preserve everything, communicate with the lender in writing, and report the suspected identity theft. She warned me not to promise payment, even to calm my parents down.
I followed her advice.
By morning, I had filed a police report, frozen my credit, and sent a formal dispute to the lender. Rebecca helped me submit conference registration records, hotel receipts, and employment emails showing where I had been on the day the guaranty was signed.
The lender’s investigators obtained the complete signing audit. The verification code had gone to Mom’s phone. The email address on the application was an old account I no longer used. The financial statement claiming I earned a salary from Madison’s company was fabricated.
It wasn’t one misunderstanding. It was a trail of deliberate choices.
Three days later, Madison showed up at the reception desk of my office building.
She looked around at the employees moving between conference rooms and the company logo on the wall.
“So this is your little computer thing,” she said.
It was the first time she’d ever visited.
She handed me a handwritten list of what she called our family’s sacrifices: birthday presents, dinners, rides to school, the years Mom and Dad had put a roof over my head.
At the bottom she had written: Amount requested to save the house: $742,000.
I handed it back.
“You’re trying to invoice me for having parents.”
Her cheeks turned red.
“You think that penthouse makes you better than us?”
“No. I thought you’d be happy I had a place of my own.”
She opened her mouth, but nothing came out.
I asked building security to escort her downstairs. Then I went back to work.
Over the following months, the lender completed its fraud review and released me from the disputed guaranty. My attorney also helped correct the credit information that had been reported under my name. The evidence was referred to prosecutors, and Madison and Mom eventually faced criminal charges over the false loan documents.
But clearing my name did not erase the legitimate debt.
My parents had pledged their house to secure the loan, and they had signed that obligation themselves. The lender still expected repayment. With Madison’s business collapsing and no realistic refinancing available, they sold the house before foreclosure proceedings could begin.
The place where Dad had once told me there wasn’t money for my tuition was gone.
They moved into a modest two-bedroom condo.
Madison’s business shut down. She sold her luxury SUV, surrendered her office lease, and took a regular salaried job. Months later, she and Mom entered plea agreements that included restitution obligations and court supervision. Neither was allowed to pretend my signature had been a harmless favor.
Dad called me after the move.
For once, he didn’t ask for money.
“I saw the report on your company,” he said. “The one about hospitals using your scheduling system.”
I said nothing.
“I remember you coming home from the night shift,” he continued. “You’d fall asleep over that laptop. I convinced myself you were fine because you never asked us for much.”
“I asked,” I said. “You told me to figure it out.”
His voice broke. “I know.”
That admission didn’t restore ten years. But it was the first honest thing he’d said about them.
A week later, I visited the hospital where I’d once worked nights. I met with its education coordinator and established a $300,000 fund for employees who wanted to earn technical certifications or finish their degrees. It would cover tuition gaps, exam fees, and equipment for people who were working while studying.
I remembered calculating whether I could afford both a bus pass and groceries. I wanted someone else to have one less calculation to make.
That evening, I stood at the windows of my penthouse, looking over Chicago. The deed sat in a drawer, no longer needed as evidence for anyone at a dinner table.
My phone lit up with a message from Dad.
I’m proud of what you built. I’m sorry I made you feel you had to build it alone.
I read it twice. Then I replied: Thank you for saying that. I need time.
I wasn’t ready to forgive them. I also wasn’t interested in spending another decade trying to make them understand my worth.
Madison had asked why I hadn’t told them about the penthouse.
The answer was simple.
I had spent years telling them who I was.
They only started listening when I showed them what I owned.