The bank’s fraud department called at 4:17 p.m., while I was still ten minutes from my parents’ house. “Someone just requested a $236,000 wire from a new device,” the woman said. “Did you authorize it?” “No,” I said. “And please don’t approve it.” “We haven’t. The request was rejected.” “Because of the security alert?” I asked. “Because the available balance is zero.”
I nearly laughed. I already knew. But the fact that someone had tried anyway turned my stomach. My parents had asked me over for an “urgent family conversation.” Now I knew what the conversation was supposed to accomplish. I had spent seven years saving that money, working weekend shifts and passing up vacations, while my brother Ryan kept asking for one more chance to turn his contracting company around.
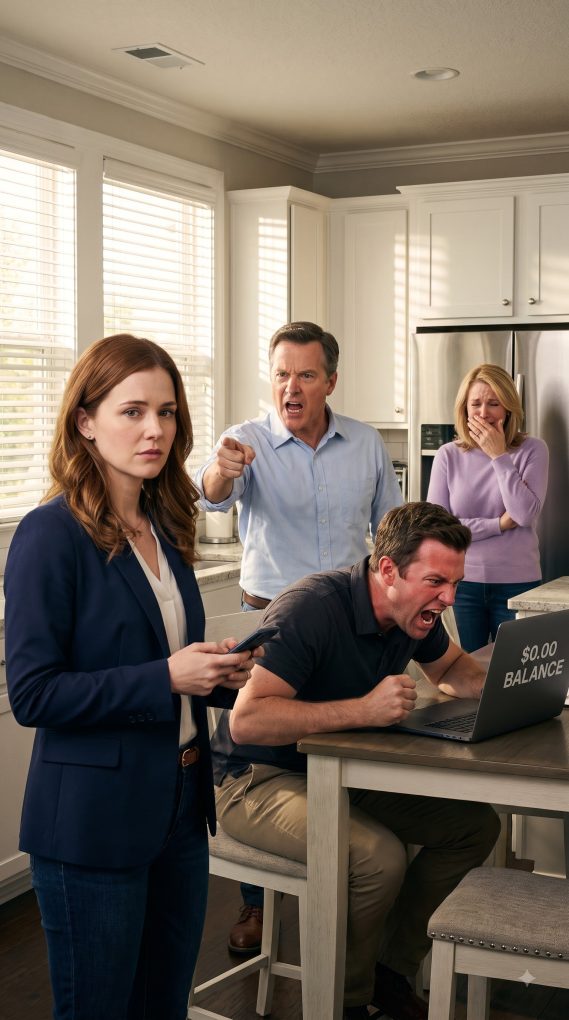
When I walked into their kitchen, Ryan sat at the table with my mother’s laptop. Dad stood behind him, one hand on the chair. Mom was beside the refrigerator, worrying the hem of her sweater. “You weren’t supposed to be here yet,” Ryan snapped. Then he refreshed the banking page. His grin died. $0.00.
“Where’s the money?” Dad demanded. “Somewhere you can’t reach it,” I answered. Ryan turned the screen toward me. “That was our emergency fund.” “No,” I said. “It was mine. Every deposit came from my paycheck.” Mom straightened. “I was on that account, Emma. I had the right to let your brother use it.”
She was right about one thing. When I was seventeen, she had helped me open the account and stayed on it as a joint owner. I had foolishly never removed her. Two days earlier, when she asked me for my login code “to check a bank notice,” I finally understood how dangerous that mistake was. I went straight to a branch and moved every dollar into a new account in my name alone.
Ryan slammed the laptop shut. “I promised someone that money by five.” “Then you made a promise with money that didn’t belong to you.” Dad stepped between us and the door. “You are not leaving until you fix this.” He wasn’t shouting. Somehow that made it worse.
My phone rang again. This time the caller identified herself as a loan officer at a different bank. “Ms. Bennett, we’re calling to verify the personal guarantee submitted under your name for your brother’s business.” I stared at Ryan. He stopped breathing for a second. “I haven’t guaranteed anything,” I said. The woman paused. “Then I need you to listen very carefully. The amount is four hundred and ten thousand dollars, and the document carries your signature.”
The loan officer was still on the line. “The form was submitted yesterday,” she said. “It identifies you as the personal guarantor and lists $236,000 in available savings.”
“I never signed it. Please mark the application as fraudulent.” She told me their review would be suspended while the bank investigated and gave me instructions for a written dispute. Ryan lunged for my phone. I stepped away, keeping the call connected. “Touch me or my phone,” I said, “and I’m calling 911.”
Dad pulled a folder from the kitchen drawer. “We were going to explain after everything settled.” Inside was a loan application for Bennett Custom Builds, Ryan’s contracting company. My birth date, income, and savings were typed into neat little boxes. Beneath a promise to personally repay up to $410,000 was a signature that looked enough like mine to fool a stranger.
Mom started crying. “He said you’d never have to pay anything. The loan would fix everything.”
“You gave him my bank account, my personal information, and a fake signature?”
Ryan slammed his fist against the table. “I have employees waiting for their checks. Do you want their families to go hungry?”
He was good at that. Turning his decisions into someone else’s cruelty. But the next page wasn’t a payroll summary. It was a demand letter from the lender on an older business loan, warning that the debt was being called due. The amount demanded was almost exactly what I’d saved. The deadline was that afternoon.
Then I saw the names on the original loan agreement.
Ryan Bennett. David Bennett.
My father.
I searched the attached business records. Dad owned forty percent of the company. He’d spent years telling me Ryan’s debts were Ryan’s problem. The documents said otherwise. Dad had pledged my parents’ house as collateral for the earlier loan. If the lender enforced its rights, the house could be lost.
“That’s what this is,” I whispered. “You aren’t protecting Ryan. You’re trying to save yourselves.”
Dad didn’t deny it. “We could lose everything.”
“So you decided I should lose everything instead?”
He said he expected me to transfer the savings as an emergency payment. The forged guarantee was supposed to secure new financing afterward. Mom insisted they would repay me when business improved, although nobody could explain how.
Ryan finally admitted the newer loan hadn’t been approved. The lender had questioned the contact information on the application and insisted on speaking to me directly. That was the one part of their plan Ryan couldn’t control. He had my Social Security number and an imitation of my signature, but he couldn’t make me say yes.
I photographed the documents and forwarded the images to my email before Ryan snatched the folder back. Then I walked toward the door. Dad moved aside, but his face had changed.
“Your mother was an owner of that account,” he said quietly. “Think carefully before you accuse anyone of stealing.”
Two hours later, while I sat in my apartment searching for an attorney, a detective called. A theft complaint had been filed against me over the missing $236,000. The complainant wasn’t Ryan.
It was my mother.
And she’d given the police a written statement saying the savings belonged to her.
I asked the detective to repeat himself. “My mother says I stole her retirement money?”
“That’s the allegation,” he replied. “I’d like to hear your account of what happened.”
I told him the account was jointly titled and that I had transferred the money myself, in person, two days before the attempted wire. He didn’t promise me anything. He just asked me to preserve the bank records and arrange a time to give a statement. Ryan had tried to take my savings. My parents had tried to make me responsible for his debts. Somehow, my mother accusing me of theft hurt most.
The next morning, I met attorney Rebecca Sloan. She listened without interrupting, then spread my documents across her desk: seven years of payroll deposits, the transfer receipt, the account agreement showing both my mother and me as joint owners, photographs of the forged guarantee, and the lender’s fraud-report confirmation.
“The account was set up in a way that gave your mother withdrawal rights,” Rebecca said. “That was risky. But having access doesn’t make Ryan entitled to your money, and nobody gets to sign a guarantee in your name without permission. We need to keep the account dispute separate from the forgery.”
With Rebecca’s help, I submitted a formal statement to the detective, disputed the loan application in writing, and placed fraud alerts on my credit files. The lender confirmed that no loan had been funded and suspended the application. My bank documented the attempted wire, reviewed access to the old account, and helped me end the joint arrangement under its procedures. The $236,000 stayed in my individual account. I changed every password my parents might have known.
But money wasn’t the only thing they were trying to take.
By Sunday, Dad had told relatives that I’d drained Mom’s retirement savings and left my parents facing foreclosure. An aunt sent me a screenshot of the family group chat. Beneath Dad’s accusation, Ryan had written, “She cares more about money than people.”
The same brother who had tried to put a $410,000 debt under my name was lecturing everyone about loyalty.
Rebecca advised me to let the investigation proceed instead. So I sent one message to the relatives who contacted me: “The money came from my earnings. I never agreed to give it away or guarantee Ryan’s loans. The authorities have the records.” Then I stopped responding.
That night, Mom called seventeen times. On the eighteenth, I answered.
“If you help us with just eighty thousand,” she whispered, “your father will tell the police this was a misunderstanding.”
I gripped the edge of the counter. “You want me to pay you to correct a false accusation?”
“It’s our home, Emma.”
“And this is my life.”
There was a pause. Then Mom said the thing that ended any hope I’d been holding on to: “We thought you’d be easier to convince after the police called.”
I ended the conversation and wrote down her words immediately. Then I forwarded Rebecca a voicemail Mom left minutes later, again offering to withdraw the complaint if I provided the money.
At the police interview, I handed over everything. I answered questions about the account’s history, the source of the deposits, and why I’d moved the balance. Rebecca sat beside me. The detective made no dramatic announcement, but he asked for the lender’s contact information and copies of the business documents I’d photographed.
Over the following weeks, investigators compared the submitted guarantee with my verified signatures and obtained records relating to its electronic submission. Ryan had used my personal information, and the application had originated from my parents’ home. Those facts alone didn’t establish who typed my name, but Mom eventually admitted that she’d watched Ryan submit it. Dad had supplied the financial figures. She also acknowledged that the theft complaint misrepresented whose earnings had funded the account.
The detective later told Rebecca that the evidence did not support criminal charges against me. The lender sent written confirmation that the disputed guarantee had not become an enforceable obligation. Its fraud team referred the forged application to law enforcement.
Then came the last family meeting.
Mom requested it. I agreed only if Rebecca was present. We sat in her conference room, with my parents on one side of the table and me on the other. Ryan didn’t come. His attorney had told him not to.
Dad looked smaller than I remembered. “We made mistakes,” he began.
“Which one?” I asked. “Giving Ryan your password? Signing my name? Or telling the police I stole the money I earned?”
He stared at the table.
Mom pushed a signed correction to her police statement toward Rebecca. She had formally withdrawn her claim that the money was solely hers. She was crying, but I couldn’t tell what she regretted.
“We’re going to have to sell the house,” Dad said.
“I know.”
“You’re really not going to help us?”
I took a breath. “I spent years helping this family. I just didn’t know the price was supposed to be my future.”
Three months later, my parents sold their house to address the business debt. Ryan faced forgery and identity-theft charges arising from the loan application. I didn’t celebrate any of it. I also didn’t rescue them.
That fall, I signed the papers for a small townhouse with a bright kitchen and a front door nobody in my family had a key to. At closing, I paid the down payment from the savings account that belonged to me alone.
I remembered Ryan refreshing the laptop, waiting for my $236,000 to appear, and the exact moment his smile vanished.
The balance he’d seen was $0.00.
For him, it meant there was nothing left to take.
For me, it was the first sign that I finally had something they couldn’t reach: a future I was allowed to keep.