She Thought Her Son’s Divorce Meant She’d Keep Living On My Dime. One Call From A Luxury Spa Made Her Realize Her Black Card Was Cut Off.
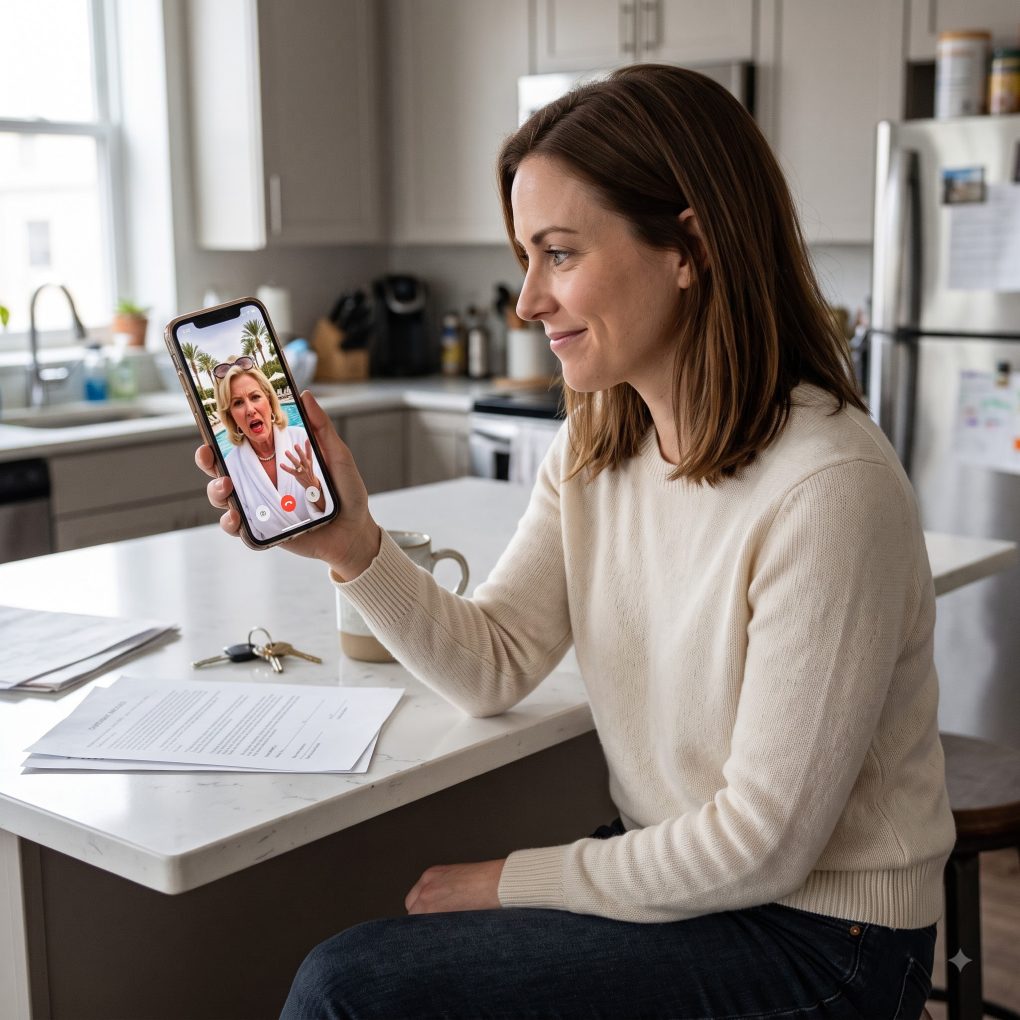
Four days after my divorce became final, my former mother-in-law called me from a luxury spa resort in Arizona, screaming so loudly I had to pull the phone away from my ear.
“HEY, YOU IDIOT! WHY DID MY CARD SUDDENLY STOP WORKING?”
I was sitting at my kitchen counter in Denver, Colorado, drinking coffee in the peaceful apartment I had rented after leaving her son.
I smiled coldly.
“I’m sorry… who is this?”
Silence.
Then came the explosion.
“DON’T YOU DARE PLAY STUPID WITH ME! I KNOW YOU’RE BEHIND THIS!”
Her name was Patricia Whitmore. For six years, she had treated me like an unpaid personal assistant while reminding everyone that her son, Brandon, deserved better than a wife who worked too much.
What she never told her friends was that the luxury credit card she carried everywhere wasn’t actually hers.
It was an authorized-user card attached to my account.
I’d added her three years earlier, after Brandon begged me to help his mother during a difficult financial period. She promised she’d use it only for emergencies.
Apparently, a $9,000 spa weekend counted as one.
“Listen carefully,” Patricia snapped. “I’m at the front desk, surrounded by people, and they’re telling me my card has been declined. Fix it immediately!”
“That’s unfortunate,” I replied. “Have you tried calling the bank?”
“YOU ARE THE BANK!”
I almost laughed.
“No, Patricia. I’m the person who used to pay the bill.”
My phone buzzed with another incoming call. Brandon.
Then another. His sister.
I ignored them.
Patricia lowered her voice, suddenly dangerous. “Your divorce agreement says you owe this family certain financial courtesies.”
“No, it doesn’t.”
“You signed documents!”
“I signed divorce documents. I didn’t sign up to finance your vacations forever.”
Her breathing grew sharp.
“You’ll regret humiliating me.”
Then she said something that made my smile disappear.
“Brandon told me you wouldn’t dare cancel the card because we have copies of your financial records. If you cut us off, everyone will learn what you’ve been hiding.”
Before I could respond, a text arrived from Brandon.
PUT HER CARD BACK ON. RIGHT NOW. YOU HAVE NO IDEA WHAT MOM JUST FOUND.
Then he sent me a photograph.
It showed a bank statement with my name on it—and a transaction I had never authorized.
$184,000.
And beneath it, someone had written three words in red ink.
SHE KNOWS EVERYTHING.
I thought the worst part of my marriage was finally behind me. I was wrong. My former mother-in-law wasn’t just angry about losing her luxury credit card. Someone had been using my name for something far more dangerous, and the people who claimed to love me were suddenly terrified I’d discover the truth.
I stared at the photograph until the numbers blurred.
$184,000.
The statement carried my name, the last four digits of an account I recognized, and a transfer dated six weeks earlier. But I had never approved that payment.
I called Brandon.
He answered on the first ring.
“Finally! Turn Mom’s card back on.”
“Explain the $184,000.”
He went quiet.
“It’s a business matter.”
“What business?”
“Don’t start interrogating me, Rachel. You’re not my wife anymore.”
“Then you shouldn’t be asking me to pay your mother’s bills.”
He exhaled sharply. “Mom made a mistake. The card got frozen. That’s all.”
“Why does her mistake involve a bank statement with my name on it?”
“Because you don’t understand how these things work.”
That sentence had followed me throughout our marriage. Whenever Brandon wanted money, he called it a temporary arrangement. Whenever his mother wanted something, he called it family responsibility. And whenever I questioned a charge, they accused me of being selfish.
I ended the call and contacted my bank’s fraud department.
The representative confirmed that my personal credit card had been frozen after an unusual transaction triggered a security review. The $184,000 transfer shown in the photograph, however, was not a charge on that card.
It was connected to a separate business account.
An account I had opened for the small consulting company I founded before marrying Brandon.
The representative couldn’t discuss every detail over the phone, but she recommended that I contact the bank’s business-fraud team immediately.
I did.
Within an hour, I learned that someone had submitted a request to change the account’s authorized contacts and initiate a transfer. The request had been flagged because the supporting documents contained inconsistencies.
No money had been released.
Yet.
I called my attorney, Megan Ellis, who had handled my divorce.
“Don’t confront them again,” she warned. “Save every message. And don’t assume that because your name appears on a document, you know who submitted it.”
That afternoon, Patricia called from the resort again.
Her voice was suddenly sweet.
“Rachel, darling, let’s not make this ugly.”
“You threatened me twenty minutes ago.”
“I was upset.”
“Then be upset without using my money.”
She sighed theatrically. “Brandon explained everything. The transfer was supposed to help us settle a family investment. Your husband was handling the paperwork.”
“Former husband.”
“Details.”
I asked her one question.
“What investment?”
She hesitated.
Then she said, “The one your father-in-law left behind.”
My father-in-law, Robert, had died two years earlier. Before his death, he had established a modest investment account for Brandon and his sister. I had never been named as a beneficiary.
“Why would his inheritance involve my business account?” I asked.
Patricia stopped pretending to be friendly.
“Because Brandon said you agreed to help.”
“I didn’t.”
“You signed something.”
“Show me.”
She hung up.
Ten minutes later, Megan forwarded a document the bank had provided during its investigation.
It was a scanned authorization form bearing my signature.
At the bottom was a clause assigning temporary management authority over my business account to a company called Whitmore Holdings.
I had never heard of it.
Megan enlarged the signature.
“Rachel,” she said carefully, “this might be a forgery. But I need you to look at the witness section.”
I looked.
The witness was Brandon’s sister, Olivia.
And the date beside her name was three days after Brandon had filed for divorce.
That wasn’t the biggest problem.
The document claimed I had signed it in person at a downtown Denver office.
I had been in Seattle that day, presenting a proposal to a client. I had the flight confirmation, hotel receipt, and meeting records to prove it.
Then Megan opened the attachment’s final page.
It contained a handwritten note from Patricia.
Once the transfer clears, pay off the resort balance and the private loan. Rachel won’t fight us after the divorce. She’ll be too embarrassed.
My stomach tightened.
“What private loan?” I whispered.
Megan didn’t answer immediately.
She was reading a second document.
Then she looked at me.
“Rachel, Whitmore Holdings isn’t just your mother-in-law’s company. Its registered manager is your ex-husband.”
She turned the screen toward me.
The company had borrowed $250,000 from a lender.
And the collateral listed in the loan paperwork was my consulting firm’s future receivables.
The loan had been approved using financial projections and client contracts I had never authorized anyone to submit.
If the lender believed the documents were valid, my company could be dragged into a debt it had never agreed to assume.
I felt the room tilt—not from fear of losing money, but from the realization that my own family had apparently planned around my silence.
Then my phone rang.
It was Olivia.
I answered on speaker.
“Rachel,” she said, her voice trembling, “please don’t let Mom know I called.”
“What did you witness?”
A long pause.
“Nothing,” she whispered. “I didn’t witness anything. I wasn’t even there.”
“Then why is your name on the form?”
“Because Brandon told me it was just paperwork to help Mom keep the resort reservation. He said you’d already approved it.”
“Did you see me sign?”
“No.”
“Did you know about the loan?”
“I found out yesterday.”
Her voice cracked.
“Rachel, there’s something else. Mom doesn’t just want the money. She thinks she can force you to pay the loan because of a clause in your old business agreement with Brandon.”
“What clause?”
“I don’t know the exact wording. But Brandon told her the divorce wouldn’t protect you.”
Before I could ask another question, I heard a man’s voice in the background.
Brandon.
Olivia gasped.
“Please, Rachel. Don’t trust either of them.”
The call ended.
Megan immediately told me not to assume the worst without evidence. The supposed agreement might be invalid, the loan might never have been properly secured, and the transfer had not cleared.
But one thing was certain.
Someone had tried to move $184,000 using paperwork that appeared to connect my business to a company I didn’t control.
And Patricia was sitting at a luxury resort, furious that the credit card I had canceled no longer worked.
That evening, Megan received a call from the bank’s investigator.
The investigator had found another document attached to the transfer request.
It wasn’t a financial statement.
It was a copy of my divorce settlement.
A yellow highlight marked one sentence about the division of marital property.
Beside it, someone had written:
SHE THINKS THIS ENDS EVERYTHING. IT DOESN’T.
Megan read it twice.
Then she said, “We need to find out who wrote this—and what they think they can still take from you.”
The next morning, I met Megan in her office with a folder full of documents and the exhausted feeling of someone who had finally stopped pretending a problem would disappear if she ignored it.
She placed three items on the table: the disputed authorization, the loan application, and my divorce settlement.
“Here’s what we know,” she said. “Someone submitted a request to transfer money from your business account. The bank flagged it. No transfer occurred. Separately, a lender issued a loan to Whitmore Holdings, and your company’s financial information appears in the supporting paperwork.”
“Can they take my business?”
“Not simply because your name appears in a file. We need to determine what you actually signed, what the lender relied on, and whether any legitimate agreement exists.”
I nodded, trying to keep my emotions out of the conversation.
For six years, I had confused being a good wife with being endlessly available. I had paid bills to avoid arguments, approved purchases because Brandon said his mother was struggling, and allowed Patricia to treat my professional success as a family resource.
I had never imagined they might use my company documents to support a loan I knew nothing about.
Megan tapped the disputed signature.
“You have a strong reason to challenge this. Your travel records put you in Seattle on the date listed here. We’ll preserve the originals and ask the bank to retain its submission records.”
“What happens if they prove it was forged?”
“Then the people responsible may face serious consequences. But we don’t need to decide that today. Our first priority is protecting your accounts and making sure nobody moves money or binds your company without your authorization.”
I signed the forms necessary to restrict changes to my business account, revoke any legitimate permissions I no longer wanted in place, and dispute the questionable authorization.
The bank confirmed that the attempted $184,000 transfer remained blocked.
My business attorney contacted the lender to formally dispute the use of my company’s financial information. We provided the travel records, the client contract history, and the original electronic files available to us.
The lender opened its own review.
For the first time since the divorce, I felt I had done something more useful than arguing with Brandon.
I had stopped arguing and started documenting.
That afternoon, Patricia arrived at my apartment.
I hadn’t given her the address, but Brandon had known it from the weeks when we were still negotiating the divorce. I saw her through the peephole, holding a designer handbag and wearing oversized sunglasses.
I didn’t open the door.
She pounded on it.
“Rachel! We need to talk!”
I called Megan, who advised me not to engage. I also asked Patricia to leave through the doorbell camera’s two-way audio.
Instead, she leaned toward the camera.
“You’ve made your point. My card is useless. Brandon is furious. Now fix this before you destroy the whole family.”
I spoke through the speaker.
“Your card was canceled because it was attached to my account. That’s all. If you have questions about the loan, contact your attorney.”
“My attorney?” She gave a disbelieving laugh. “I’m your family!”
“Not anymore.”
Her expression changed.
“You ungrateful little—”
“I’ve saved the recording, Patricia. Please leave.”
She stared at the camera for several seconds before turning away.
That evening, Brandon sent me a long email.
He claimed the loan was a misunderstanding. He said he had expected me to help his mother because I had done so in the past. He insisted the signature on the authorization was probably copied from an old document by mistake.
Then came the sentence that mattered most:
You know how Mom gets when she panics. If you would just release the transfer, we could repay everything before anyone has to make this formal.
I forwarded the email to Megan.
She replied with one line:
Do not release anything.
Two days later, Olivia agreed to meet us at Megan’s office.
She looked like she hadn’t slept.
“I need to tell you the truth,” she said.
Megan explained that Olivia wasn’t there to sign a confession or make accusations without evidence. She could share what she personally knew, and the attorneys would preserve any relevant information appropriately.
Olivia folded her hands.
“Mom wanted the resort trip because she’d promised her friends she’d celebrate Brandon’s fresh start. She said the divorce meant you wouldn’t be able to interfere with family finances anymore.”
I stared at her.
“Why did she think that?”
“Brandon told her you were going to keep paying some of his expenses until the business loan was settled.”
“I never agreed to that.”
“I know.” Olivia’s eyes filled. “I should have asked you before signing the form. But Brandon said you’d approved it and that Mom needed the money immediately. I signed as a witness without being present. I thought it was just a form confirming the account information.”
“Did you know what the form actually authorized?”
“No. Not then.”
Megan asked Olivia to describe exactly when she had learned about the loan.
Olivia explained that Brandon had shown her a spreadsheet while asking her to help organize documents for Whitmore Holdings. She noticed that my consulting company’s projected revenue had been included in the lender’s calculations. When she questioned him, he told her I had agreed to let the company use those figures.
She believed him at first.
Then she saw the authorization form and realized the date was impossible.
“I asked him why he had put my name on it,” she said. “He told me it didn’t matter because nobody would check.”
The room went quiet.
“Did you tell Patricia?” I asked.
“Yes. She said I should stop being dramatic. She told me you owed Brandon after everything he’d sacrificed for you.”
I almost laughed at the absurdity of it.
Brandon had sacrificed very little. I had built my consulting firm before our marriage, and its income had helped cover our shared expenses for years. During the last two years, I had also paid several of his mother’s bills because he promised they were temporary.
I had never demanded repayment.
I had never even kept a complete list.
Apparently, they had mistaken my generosity for an agreement they could expand indefinitely.
Olivia slid a flash drive across the table.
“These are the files Brandon sent me. I didn’t change anything. I saved them because I was scared he’d delete them.”
Megan did not immediately plug it into her computer. She arranged for the files to be reviewed safely and preserved with their original metadata where available.
Several days later, the review uncovered something important.
The disputed authorization had been assembled from a digital copy of my signature on an old business document. The file history showed that the authorization had been created on Brandon’s laptop, not at the office listed on the form.
That finding did not, by itself, establish every detail of who had directed the submission. But it seriously undermined the claim that I had personally signed the document.
The lender also confirmed that the loan to Whitmore Holdings was separate from my personal accounts. It had been issued to Brandon’s company, and my consulting firm had not guaranteed it through any agreement I had authorized.
The lender began reviewing the application and its supporting documents. It restricted further changes while the dispute was investigated and asked Whitmore Holdings to explain how my company’s records had been obtained.
Most importantly, the $184,000 transfer never went through.
The next call came from Patricia.
This time, she didn’t scream.
“Rachel, darling,” she said softly, “I think there’s been a terrible misunderstanding.”
“There has.”
“Brandon is under enormous pressure. The lender is asking questions, and Olivia is making everything worse. You could clear this up by confirming that you agreed to help.”
“I didn’t agree.”
“You’ve helped us before.”
“Helping you pay a bill is not the same as guaranteeing your son’s business loan.”
“But you know we intended to repay it!”
“Then Brandon can explain the paperwork to the lender.”
She inhaled sharply.
“You’re going to ruin his future over a little signature?”
“No. I’m refusing to put my future at risk to protect him from the consequences of his choices.”
Her voice turned cold.
“You always thought you were better than us because you had your little business.”
I looked around my quiet apartment. No one was yelling. No one was demanding money. No one was telling me that my boundaries were an insult.
“I never thought I was better than you,” I said. “I thought family meant we could trust each other.”
Then I ended the call.
The investigation continued for several weeks.
The lender ultimately determined that the documents submitted on behalf of Whitmore Holdings did not establish a valid guarantee from my consulting firm. It removed my company from the disputed collateral records and continued pursuing repayment from the borrower under its own loan agreement.
The bank completed its review of the attempted transfer and maintained the restrictions necessary to protect my account. The questionable authorization was not accepted as proof of my consent.
Megan advised me that any further allegations about fraud would depend on the evidence and the decisions of the relevant institutions. I didn’t need to make public accusations or threaten anyone online. The documents and the formal investigation could speak for themselves.
Meanwhile, Brandon’s business faced the consequences of a loan it couldn’t comfortably repay.
He sold a vehicle, closed an expensive office, and negotiated a repayment arrangement with the lender. Patricia canceled the remainder of her resort stay after discovering that her own available funds wouldn’t cover the charges she’d accumulated.
The luxury vacation she had expected me to finance ended with a bill she had to pay herself.
I heard about it from Olivia, who apologized again.
“I should have questioned them,” she said.
“Yes,” I answered. “You should have.”
She looked down.
“Can you ever forgive me?”
“I don’t know yet. But I appreciate that you’re finally telling the truth.”
It wasn’t a dramatic reconciliation. She didn’t become my closest friend overnight, and I didn’t pretend that one honest conversation erased what had happened. We agreed to keep communication open while I took the time I needed.
Brandon tried one last time to reach me.
He showed up outside my office and waited until I finished a meeting.
“Rachel, please,” he said. “We were married for six years. You can’t just cut me off like I’m nobody.”
“I didn’t cut you off. We divorced.”
“You know what I mean.”
“I do.”
He looked tired. His expensive jacket was creased, and the confidence he once carried into every room had faded.
“Mom says you’re doing this to punish us.”
“Your mother is free to believe whatever she wants.”
“You could have helped us.”
“I did help you. For years. But I never agreed to let you use my name on a loan.”
He rubbed his forehead.
“I thought you’d understand.”
“That was the problem, Brandon. You thought I would understand anything you did, as long as you called it family.”
He had no answer.
For a moment, I remembered the man I’d married: charming, funny, full of plans. I had once believed that if I supported him long enough, he would eventually learn to stand beside me instead of behind me, waiting for me to pay for the next step.
But loving someone didn’t mean I had to keep financing the person he refused to become.
“I hope you figure things out,” I told him. “But you won’t figure them out with my money.”
Then I walked inside.
Months later, the divorce paperwork was safely filed away, my business accounts were secure, and my company had moved forward with two new clients. I no longer received calls about Patricia’s shopping, Brandon’s emergencies, or expenses that somehow became my responsibility without my consent.
I also removed every authorized user from my personal accounts and changed the passwords on my business systems. It was a simple administrative task, but it felt like closing a door that had been left open for years.
One afternoon, while sorting old paperwork, I found the original receipt for Patricia’s first emergency purchase on my card.
It had been a few hundred dollars.
I remembered how grateful she’d sounded when I offered to help. She had called me the daughter she’d always wanted.
I had held on to that memory through years of demands because I wanted to believe the gratitude had been real.
Maybe it had been, for a moment.
But gratitude that turns into entitlement is no longer gratitude. And love that depends on unlimited access to someone else’s money is not the kind of love I wanted to keep.
I never called Patricia to gloat about her canceled card. I didn’t post the documents online or try to humiliate Brandon in front of his friends. I simply refused to take responsibility for debts I hadn’t agreed to carry.
A week after the lender closed its review of my company’s involvement, I received one final text from Patricia.
I hope you’re happy. You have your money. We have nothing.
I read it twice.
Then I replied:
I hope you learn the difference between losing access to my money and losing a family member. Those were your choices, not mine.
I blocked the number.
For the first time in six years, I didn’t feel the need to explain myself to anyone.
Four days after my divorce, Patricia had called from a luxury spa resort and demanded to know why her card had stopped working.
She expected an apology.
She expected panic.
She expected me to rescue her, just as I had rescued her son, over and over again.
Instead, she heard a question.
“I’m sorry… who is this?”
It wasn’t that I had forgotten her name.
It was that I had finally stopped accepting the role she’d assigned me.
I was no longer Brandon’s wife, Patricia’s emergency fund, or the person expected to make every family crisis disappear.
I was Rachel Bennett, a woman with her own business, her own future, and the right to decide where her money went.
And the most satisfying part wasn’t watching their plans fall apart.
It was waking up the next morning and realizing that their problems no longer automatically belonged to me.
Because sometimes, the strongest response isn’t revenge.
It’s closing the account, keeping the evidence, and refusing to pay for a life that was never yours to support.