My husband pulled off Interstate 95 at 11:43 p.m., opened my door, and told me to walk because I wouldn’t give him the password to my salary account. Eight years of marriage ended with his taillights disappearing around a bend. By morning, I would have forty-one missed calls from him. I thought he’d finally realized what he’d done.
I was wrong.
We’d been driving home from his mother’s birthday dinner in Connecticut. Evan had waited until we were alone to bring up our finances.
“Married people don’t hide money,” he said.
“We have a joint account for bills,” I reminded him. “My paycheck goes into my account. We agreed on that.”
“That was before my business needed help.”
Evan owned a small custom-cabinet shop. For months, he’d blamed late invoices for everything: missed dinners, his temper, the way he checked my phone whenever it buzzed. He wanted my banking login, not just another contribution toward the mortgage.
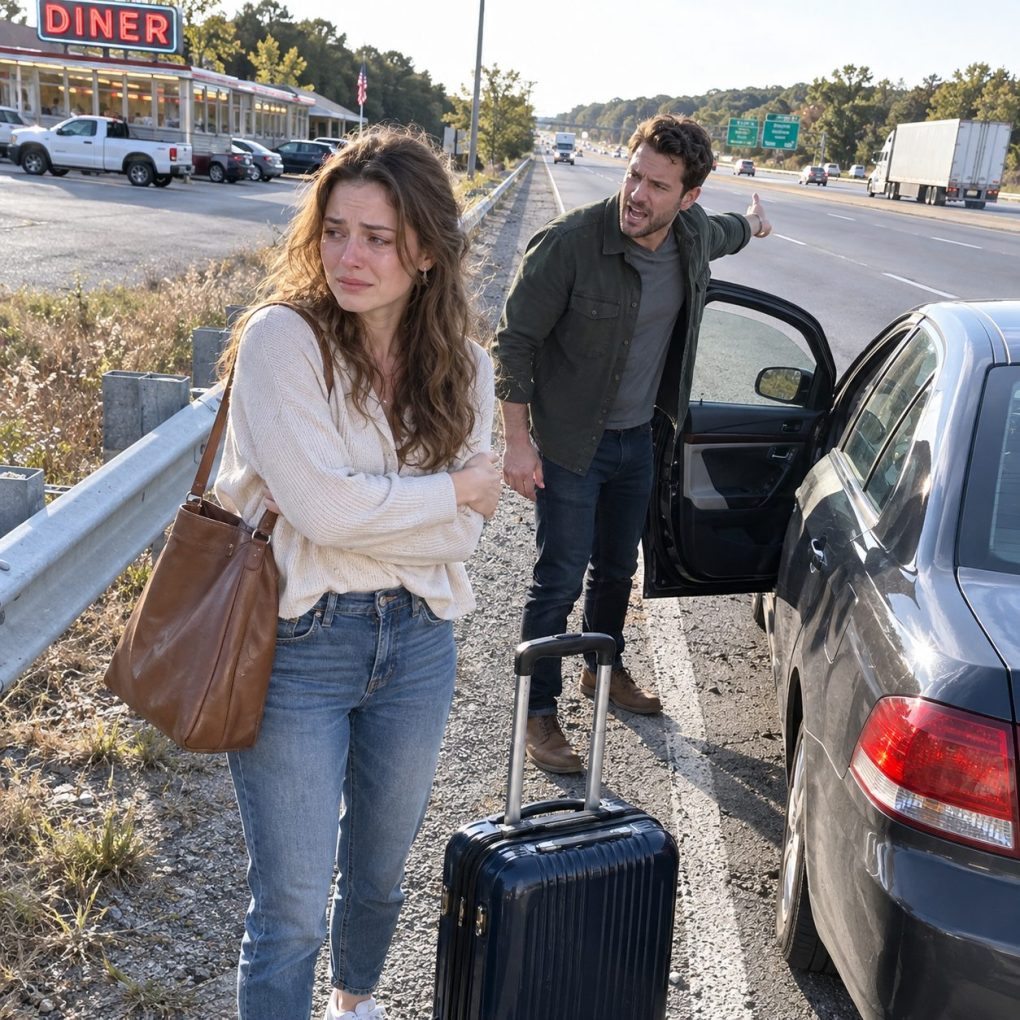
When I refused, he took the next exit, stopped beside a dark service road, and reached across me to open the passenger door.
“Get out. Maybe a night on your own will teach you what marriage means.”
I actually waited for him to smile. This was the man who once drove across town in a thunderstorm because I’d forgotten my inhaler at work. Surely he wouldn’t leave me here.
He did.
My suitcase was still in his trunk. I had my purse, my phone, and shoes that pinched my heels. I walked toward a neon DINER sign beyond the overpass, flinching every time a truck passed.
Inside, a waitress named June noticed me hovering beside the door.
“Coffee?” she asked.
I nodded because if I tried to explain, I was afraid I’d cry.
She set a mug in front of me and quietly slid a phone charger across the counter. Nobody asked why I kept staring at the empty booth opposite mine.
At 8:12 a.m., I woke with my cheek against my folded coat.
Forty-one missed calls. All Evan.
My thumb hovered over his name. Part of me wanted to hear him say he was sorry. Another part wanted to hear him ask whether I was safe.
Instead, there was a voicemail from a credit union I’d never used.
“Mrs. Parker, we need to verify your authorization on a pending home-equity application. Please call our lending department before any funds are released.”
I owned our house with Evan.
I had never applied for a home-equity loan.
I called the credit union from June’s booth, with my untouched breakfast cooling between my hands. The loan officer verified my identity and carefully explained what had been submitted: a $186,000 home-equity line of credit against the house Evan and I owned together. My name appeared as a co-borrower.
“That’s impossible,” I said. “I never signed anything.”
“I’m placing a fraud alert on the application,” she replied. “Nothing has been funded. Our verification team already had concerns.”
“About what?”
“The employment and bank information didn’t match the records provided.”
Suddenly, his obsession with my salary account made sense. Evan needed my actual income verified, and he wanted access to the money behind it. If I had handed over my login, he could have tried to connect my account to the lender’s portal—or take money himself.
I called him.
He answered before the first ring finished.
“Finally! Tell them you authorized the loan.”
“You forged my name?”
“Don’t use that word.”
I gripped the coffee mug until my fingertips hurt.
“Where did you sleep last night, Evan?” I asked.
“What?”
“Because I slept in a diner. You left me on the highway.”
“I knew you’d find somewhere. Stop twisting this into a tragedy.”
He was furious that I remembered what he’d done.
Later, I opened our joint checking history. Over four months, he’d transferred $34,600 into his cabinet company while telling me we barely had enough for the mortgage. As a joint owner, he’d been able to move those funds. I’d simply trusted him not to.
My mother-in-law called next.
“Evan says you walked out during an argument,” she said. “You know how stressed he is.”
“He put me out of the car.”
A pause.
“Well, you can be stubborn.”
I looked through the diner window at the trucks sliding past in daylight. June was wiping down the counter. Every few minutes, she glanced toward me without asking for an explanation.
I had been married for eight years, yet the person checking whether I was okay was a waitress who didn’t know my last name.
That afternoon, my friend Tessa picked me up. She sat beside me while I changed passwords and made an appointment with an attorney. Two days later, the credit union provided copies of the disputed documents through its secure portal.
The e-signature record showed my approval at 12:18 a.m., from the computer in our house.
I found the diner receipt in my pocket: 12:06 a.m., one coffee. I laid it beside the screen, suddenly grateful for that little piece of paper.
Under the confirmation box, someone had checked: Both borrowers are present and consent.
At 12:18, I’d been sitting beneath a flickering diner sign.
And Evan had been home, signing for me.
When Tessa drove me back to the house, Evan’s car was in the driveway. I could see my overnight bag through the rear window, exactly where I’d left it before his mother’s dinner.
For some reason, that hurt. He’d remembered to bring my things home. He hadn’t remembered to bring me.
I didn’t go inside alone. Tessa waited while I collected my work laptop, clothes, and the folder containing our mortgage statements. Then I stayed at her apartment.
My attorney helped me notify the credit union in writing, preserve Evan’s messages, and file a police report about the forged application. I moved my paychecks into a new account only I controlled. I didn’t secretly empty our joint account or stop paying my share of the mortgage; we arranged temporary household payments while the divorce began.
Evan showed up at my attorney’s office a week later.
“You’re really going to end eight years over one bad night?” he asked.
I remembered standing beneath the overpass, my feet aching, turning around every time headlights came toward me.
“One bad night?” I repeated.
“I was angry. I expected you to call.”
“I did call you, Evan. Before I reached the diner. You declined it.”
He looked down.
Then he said, “If the loan doesn’t go through, I lose the shop.”
That was the first honest thing he’d told me in months.
He admitted that two major contracts had fallen through and he’d used money from our joint bills account to cover overdue business expenses. He’d hoped the home-equity loan would keep everything afloat. He knew I would refuse, so he signed in my name and planned to persuade me afterward.
“And leaving me on the road?” I asked.
He rubbed his forehead. “I thought you’d come around.”
I waited for an apology. What I got was, “Can you at least tell the bank we talked about it?”
“No.”
He stared at me as if I’d become a stranger.
Over the next several months, the credit union confirmed the application was unauthorized, canceled it, and released no funds. No new lien was placed on our house. The disputed documents were referred for investigation; I couldn’t control whether prosecutors would pursue charges.
Our divorce settlement accounted for the transfers from our joint account. We sold the house, divided the proceeds under the agreement, and Evan kept the struggling cabinet business and its remaining debts. I rented a small apartment near my work.
I grieved more than the marriage. Sometimes I remembered the man who’d driven through a storm to bring me medicine. I didn’t know exactly when love had become a demand for access, but I knew I could no longer live inside that demand.
One Saturday, almost a year after the night on the highway, I drove back to June’s diner.
She recognized me before I ordered.
“Coffee?” she asked.
I smiled. “And breakfast this time.”
She brought me a mug and set a charger beside it, just in case.
I sat by the window watching cars pass the exit, and realized I wasn’t waiting for any of them to turn around.
I could drive myself home.