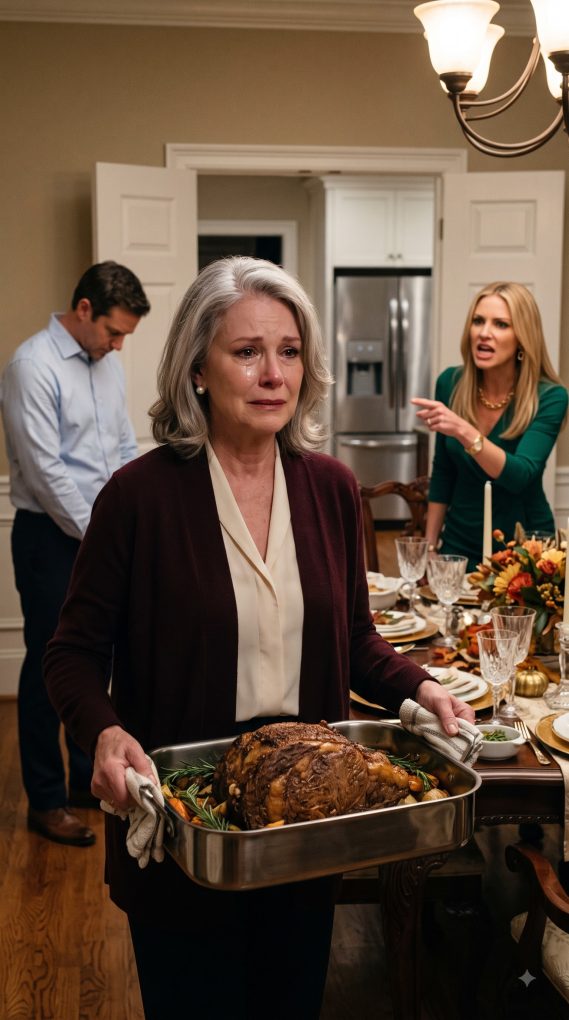
“That’s for my family, Audra. Find something in the refrigerator.” Those were my daughter-in-law’s words after I’d spent four years paying their household expenses. I quietly took my prime rib home and canceled every scheduled payment. When my son called four days later, he was terrified by what he’d discovered.
“Do NOT put that roast on my table, Audra. This dinner is for my family.”
My daughter-in-law, Lauren, said it loudly enough for all twelve guests to hear.
I stood in her kitchen holding a roasting pan filled with the $186 prime rib I’d spent five hours preparing.
My son, Michael, was standing beside the refrigerator.
“Michael?” I asked quietly.
He stared at the floor.
Lauren folded her arms.
“You can help yourself to whatever’s left in the refrigerator. But don’t embarrass me in front of my guests.”
Her mother smirked from the dining room.
I looked at the beautifully decorated table, the expensive wine, and the matching chairs I’d helped pay for.
Then I smiled.
“Of course, Lauren.”
I picked up my roasting pan, walked past twelve stunned faces, and carried dinner back to my car.
Nobody stopped me.
Not even my son.
That evening, I opened my laptop and examined four years of bank statements.
Mortgage assistance. Electricity. Car insurance. Groceries. Preschool tuition.
Every month, I’d quietly transferred money because Michael insisted they were struggling.
I’d sacrificed vacations, postponed replacing my aging car, and spent $147,000 helping them maintain a lifestyle I couldn’t afford myself.
At 68, I finally understood something.
They didn’t consider me family.
They considered me a bank account.
I canceled every scheduled transfer and every household payment I wasn’t legally obligated to make.
Four days later, my phone rang.
Lauren was screaming.
“What did you DO? The bank just called!”
Before I could answer, Michael grabbed the phone.
“Mom, please. There’s something about this house Lauren never told you.”
And then he said a number that made my blood run cold.
I had always believed my son was struggling to support his family. But the amount Michael mentioned didn’t match anything I’d ever given them. As I searched through my banking records again, I began to suspect that the dinner humiliation had exposed something far bigger than Lauren’s cruelty.
“Forty-eight thousand dollars,” Michael whispered.
I gripped my phone.
“What are you talking about?”
“The bank says we’re forty-eight thousand dollars short of what Lauren told me we had saved.”
Behind him, Lauren shouted, “Don’t tell her our business!”
I sat at my kitchen table, staring at the spreadsheet I’d created the night before.
For four years, I’d sent Michael and Lauren an average of $3,000 every month.
They claimed the money was necessary to keep their house, cars, and children’s expenses covered.
But apparently, they’d also been saving for something.
“Michael, what exactly did Lauren tell you about the money I sent?”
Silence.
Then he answered.
“She said you only helped occasionally. Maybe a few hundred dollars when things got tight.”
My heart sank.
“Michael, I’ve sent you more than $140,000.”
“What?”
“Check your banking records.”
I heard frantic tapping.
Then his breathing changed.
“Mom, those deposits were labeled household assistance.”
“Because that’s what they were.”
Lauren snatched the phone.
“You had no right to interfere with our finances!”
“Your finances?” I replied. “Lauren, I’ve been paying your electric bill since your oldest daughter was born.”
“That was your choice!”
“Yes. And stopping was my choice too.”
She hung up.
Twenty minutes later, Michael appeared at my front door.
He looked exhausted.
“Mom, I need to show you something.”
He opened his laptop.
There was a spreadsheet showing monthly transfers into a savings account Lauren controlled.
The total was $48,600.
Michael explained that Lauren had told him the savings came from bonuses at her marketing job.
But when he called the bank, he discovered something different.
The account had been nearly emptied three weeks earlier.
A large payment had gone to a real estate company in Florida.
“Lauren says it’s an investment,” he whispered.
“What kind of investment?”
He turned the screen toward me.
A waterfront vacation condominium.
Purchase agreement. Deposit receipt. Closing documents.
And there, beneath Lauren’s name, was another buyer.
Her mother, Patricia.
I stared.
“Your mother-in-law?”
Michael nodded.
“They’re buying it together.”
I remembered Patricia’s expensive jewelry, her luxury vacations, and the way she’d smiled while Lauren humiliated me.
For years, Patricia had insisted that her daughter deserved a better life.
Apparently, I’d been financing it.
“Does Lauren know you found this?”
“She does.”
“And?”
“She said the condo was supposed to be a surprise.”
“A surprise for whom?”
Michael couldn’t answer.
Then he opened another document.
It was an email Lauren had sent Patricia two months earlier.
The subject line read: Our Exit Plan.
My stomach tightened.
Michael scrolled down.
Lauren had written that once the Florida property was secured, she would stop relying on his mother’s money.
Then came a sentence that made him look physically ill.
“Michael doesn’t need to know how much we’ve put away. He’ll only feel obligated to tell Audra.”
I covered my mouth.
But the next paragraph was worse.
Lauren had promised Patricia that Michael would eventually refinance their family home to pay for the remaining condominium expenses.
He hadn’t agreed to anything.
He hadn’t even known about the purchase.
Suddenly, Michael’s phone buzzed.
A message from Lauren.
“If your mother doesn’t fix what she canceled, I’m telling everyone what she did to us.”
Then another message appeared.
“And Michael, don’t forget whose name is on the deed.”
Michael went completely pale.
“Mom,” he whispered, “I think Lauren has already made arrangements to sell our house.”
I stared at him.
“Without telling you?”
He nodded.
And when he showed me the listing agreement, I recognized the signature at the bottom.
It was supposed to be his.
But it wasn’t his handwriting.
“Michael, are you absolutely certain you didn’t sign this?”
My son stared at the document.
“I’ve never seen it before.”
The listing agreement carried an electronic signature beside his name.
The date was eleven days earlier.
I asked Michael to forward everything to my attorney, Rebecca Sloan.
By noon, Rebecca had reviewed the paperwork.
“The house is titled jointly,” she explained during our conference call. “Lauren can’t simply transfer Michael’s ownership without his authorization. And an electronic signature doesn’t prove he personally signed.”
Michael rubbed his forehead.
“What should I do?”
“Contact the listing brokerage, dispute the signature in writing, and preserve every document.”
For the first time in four years, I watched my son take responsibility instead of asking me to solve everything.
He called the brokerage while Rebecca listened.
The agent sounded genuinely surprised.
“Mrs. Carter told us both owners had approved the listing. She handled the electronic paperwork.”
Michael closed his eyes.
“I never approved anything.”
The brokerage immediately placed the listing on hold pending verification.
Then Rebecca asked another question.
“Michael, where is Lauren now?”
“At her mother’s house.”
“Have you checked your joint accounts?”
He went silent.
An hour later, we discovered another $12,400 had been withdrawn from their shared savings over the previous six months.
The statements showed transfers to Patricia.
When Michael confronted Lauren, she finally admitted she’d been financing the condominium with money she considered hers.
“My mother has done more for me than yours ever did!” Lauren shouted over speakerphone.
I almost laughed.
Instead, I asked one question.
“Lauren, who paid your mortgage when Michael lost his job?”
Silence.
“Who paid for Emma’s preschool? Who covered your car insurance? Who bought groceries when you said your credit cards were maxed out?”
“You offered!”
“I did. Because I thought my family needed help.”
“You’re punishing us over a stupid dinner!”
“No,” I said calmly. “That dinner showed me how little you respected the person keeping your household afloat.”
Michael interrupted.
“Lauren, did you sign my name?”
She hesitated.
Then she whispered, “I used your email because I knew you’d overreact.”
Michael stared at the phone.
“You were trying to sell our home.”
“We could have moved somewhere better!”
“Without discussing it with me?”
Patricia suddenly joined the call.
“Audra, this is all your fault. A decent grandmother wouldn’t abandon her family over money.”
I looked at the framed photograph of my late husband beside my desk.
For thirty-eight years, Walter and I had saved carefully, never spending what we didn’t have.
After he died, I’d used those savings to help Michael build a secure future.
And now Patricia was calling me selfish.
“Patricia,” I replied, “you attended Thanksgiving in a house I helped keep running, ate food I purchased, and watched your daughter humiliate me. You said nothing.”
“That doesn’t give you the right—”
“It gives me every right to decide how I spend my retirement.”
I ended the call.
Over the following weeks, the truth emerged.
Lauren and Patricia had planned to purchase the condominium, rent it to vacationers, and use the income to build their own business.
The idea itself wasn’t illegal.
The deception was what destroyed Michael’s trust.
With advice from independent attorneys, Michael disputed the unauthorized signature, separated his personal finances from their joint accounts, and began divorce proceedings.
The brokerage withdrew the listing after the ownership dispute was documented.
Lauren’s condominium purchase eventually collapsed when she couldn’t produce the remaining funds.
Patricia blamed me.
Lauren blamed Michael.
Neither apologized.
Three months later, Michael visited with my two grandchildren.
He brought groceries.
Not because I’d asked him to.
Because he finally understood that love shouldn’t flow in only one direction.
“Mom,” he said as we prepared dinner, “I should’ve defended you that day.”
“Yes,” I answered. “You should have.”
His eyes filled with tears.
“I was afraid of making Lauren angry.”
“And you decided hurting me was easier.”
He lowered his head.
“I’m sorry.”
I believed him.
But I didn’t immediately offer financial help again.
Instead, Michael found a smaller rental home, created a realistic budget, and arranged affordable childcare around his work schedule.
He stopped treating me like an emergency fund.
I stopped treating sacrifice as proof of love.
Six months after that terrible Thanksgiving, Michael invited me to Sunday dinner.
When I arrived, he was standing in the kitchen wearing an apron.
A beautiful prime rib sat in the center of the table.
Emma, my eight-year-old granddaughter, ran toward me.
“Grandma, Daddy made your favorite!”
Michael pulled out a chair.
“Mom, this seat is yours.”
I looked at the table.
There were no expensive decorations, no designer dishes, and no people pretending my generosity was invisible.
Just my son, my grandchildren, and a meal prepared with love.
Michael raised his glass.
“To Mom. Who taught me that family isn’t about who pays the bills. It’s about who shows up with respect.”
I wiped away a tear.
Then I smiled.
“Actually, Michael, there’s something else I learned.”
He looked concerned.
“What?”
I reached for my fork.
“Never bring a $186 prime rib to someone who thinks you belong in the refrigerator.”
We all burst out laughing.
And for the first time in years, I enjoyed dinner without worrying about the price.
Because I’d finally learned the difference between helping my family and allowing them to use me.
I hadn’t lost my family by setting boundaries.
I’d given us the chance to become a real one.