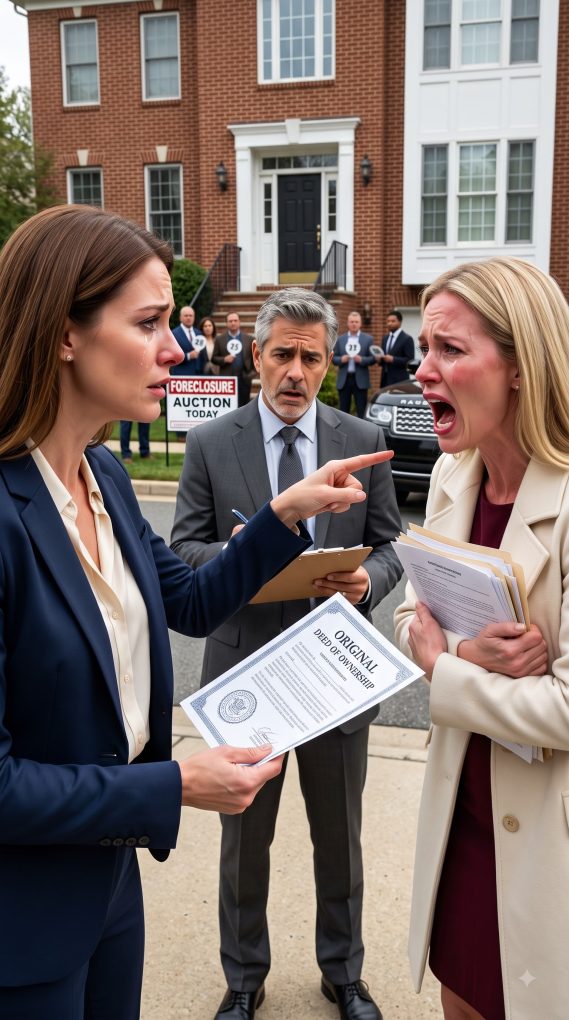
The man hammering an auction sign into my front lawn stopped when I pulled into the driveway. The sign read FORECLOSURE SALE. TUESDAY. 10 A.M.
After six months in Boston, I had been home five minutes. And the townhouse I had paid for in cash five years earlier was apparently being sold by a bank.
“Take that down,” I told him.
He lowered his hammer. “Ma’am, I’m contracted by Alden Bank. The sale is at the county courthouse tomorrow.”
“There is no mortgage on this property.”
He checked his clipboard. “Eight-hundred-thousand-dollar loan. Four months in default. You need to call the lender.”
My phone nearly slipped out of my hand. Then my front door opened, and my younger sister, Megan, stepped outside carrying a mug from my kitchen.
“Oh,” she said. “You’re early.”
I stared at the keys hanging from her fingers. I had given her one key to check on the house while I worked in Boston. I had not given her permission to live there.
“What did you do?”
Megan glanced at the sign, then shrugged. “I borrowed money against the house. I thought my business would take off before you got back.”
“Against whose house?”
She gave me a small, ugly smile. “Yours. Technically.”
I called the number on the notice. A bank representative emailed me a copy of the loan package while Megan stood on the porch, watching. There was my name on an $800,000 promissory note. There was my signature on a security deed. There was even a notary’s stamp.
None of it was mine.
“You forged my signature.”
“Lower your voice,” Megan snapped. “The neighbors are watching.”
“Where is the money?”
“Gone. I invested most of it. The rest covered debts.”
My mother arrived before I could answer. Megan had called her. She climbed out of her car and said, “Claire, this family doesn’t need a scandal. You can afford to start over.”
For one second, the betrayal hurt worse than the sign.
I called my attorney, Rebecca Sloan, and forwarded the papers. She asked me to read the name listed as the grantor on the security deed. I read it aloud: “Claire Bennett, individually.”
Then Rebecca asked one question.
“Claire, who actually owns the townhouse according to the latest recorded deed?”
I opened the property records on my phone. The screen showed a document Megan had apparently never seen.
Rebecca went silent. Then she said, “Your sister made a serious mistake. But somebody filed another document to cover it up, and I need you to see whose signature is on that one.”
“My mother’s?” I whispered.
Rebecca didn’t answer immediately. She was reading the document line by line while I sat in my car, staring at the front door of the home I had worked twelve years to own.
The document was called a Certification of Trust. It claimed I was medically incapacitated and that Megan had become the acting trustee of the Claire Bennett Revocable Trust. Attached was a letter supposedly written by a physician in Boston. My mother had signed as a witness.
I had never been incapacitated. I had never seen that doctor. And Megan had never been my successor trustee.
Three years earlier, after my divorce, I had transferred the townhouse into my living trust. The county’s current deed named me as trustee, not as an individual owner. Megan had copied the older deed from a file cabinet and forged my individual signature on the bank’s security deed. Even the fake trust certificate couldn’t make that security deed a genuine act of the property owner.
“Then stop the auction,” I said.
“We’re filing for an emergency order,” Rebecca replied. “But the lender is relying on notarized documents, and the sale is less than twenty hours away. We need proof of how they got there.”
I walked back to the porch. “Mom. Did you sign a document saying I couldn’t make decisions for myself?”
Her face drained. Megan stepped in front of her.
“It was temporary,” Megan insisted. “I was going to pay everything back.”
“By selling my home?”
“The bank wouldn’t approve the loan without proof I could act for the trust,” she said, then stopped, realizing what she had admitted.
I looked at Mom. “You helped her.”
“She was going to lose her boutique,” Mom whispered. “I thought you would forgive her once she got back on her feet.”
Rebecca called again. The closing statement showed that $190,000 had gone straight to settle a debt in our mother’s name. The rest had been wired into Megan’s business account. Megan admitted she’d burned through it on unpaid vendors, credit cards, and cash withdrawals.
Mom began crying. Megan didn’t.
“I can still fix this,” Megan said. “Sign a new loan agreement. Tell the bank you authorized it. Nobody has to go to jail.”
“You’re asking me to commit fraud for you.”
“I’m asking you to act like a sister.”
I stepped away and called the police nonemergency line to make a report, then sent Rebecca my original trust, the recorded deed, and the emails showing I had been working in Boston on the day of the supposed signing. Rebecca arranged an emergency hearing for the next morning, before the courthouse sale.
Just after midnight, a message arrived from the bank’s lawyer. The lender intended to oppose the injunction. It had a notarized statement from someone claiming to have witnessed me sign the loan documents in person.
I opened the attachment.
My mother had sworn under penalty of perjury that she watched me sign in our kitchen.
At 8:30 the next morning, she would have to repeat that story in front of a judge.
At 8:26 a.m., my mother walked into the courthouse beside Megan. Megan wore a navy blazer, as if looking professional could legitimize stolen money.
Rebecca and I had spent the night gathering evidence, not arguing with my family.
The judge called our case shortly after 8:30. Rebecca explained that the bank was auctioning trust property over a forged individual signature. She placed the two recorded deeds side by side. One showed my original purchase; the other, recorded three years earlier, transferred title to me as trustee.
“The bank’s security deed identifies the wrong grantor,” Rebecca said. “And our client denies signing it at all.”
The bank’s attorney stood. He said the lender had received a trust certificate authorizing Megan to act. He also had a notarized witness statement supporting the closing. He wasn’t accusing me of lying, he said, but the bank had a recorded security deed and a foreclosure date it had lawfully noticed based on the information in its file.
Then my mother took the witness chair.
“I was there,” she said, staring at her hands. “Claire signed the papers in her kitchen.”
“On May ninth?” Rebecca asked.
“Yes.”
“At two fourteen in the afternoon?”
Mom hesitated. “I think so.”
Rebecca showed her a photograph of me speaking at a client presentation in Boston that afternoon. Rebecca backed it with attendance records, a building access log, and a sworn declaration from the director beside me that day.
“You understand that Ms. Bennett could not have been signing papers in her Atlanta kitchen at the same time?” Rebecca asked.
Mom’s face crumpled. “Megan said it was only a formality.”
The room went quiet.
The bank’s attorney requested a recess. During it, he called the lender’s fraud department. I watched him return with a different expression. Whatever he had learned, he no longer looked eager to proceed with the sale.
When court resumed, Rebecca introduced the original trust agreement. It named my aunt Evelyn, not Megan, as successor trustee if I could no longer serve. The supposed physician’s letter had no matching record from the named medical practice, according to the response its office had sent us that morning. Even if Megan had somehow been authorized to act, the security deed had still been executed in my personal name, not by a trustee acting for the trust.
The judge granted a temporary restraining order stopping the foreclosure sale. She wasn’t deciding the fraud allegations yet, she said. But the disputed documents were enough to stop the sale pending further proceedings.
I heard the words “sale restrained” and finally felt my shoulders loosen.
Outside the courtroom, Megan grabbed my sleeve.
“You humiliated Mom.”
I pulled away. “She lied under oath to take my house.”
“She was trying to help me.”
“No. She helped you hurt me.”
Megan’s composure cracked. She began talking so quickly her words tangled. Her boutique had been failing for a year. She owed vendors, a landlord, and a private investor who had threatened to sue. She had convinced herself she could borrow against my townhouse, rebuild the business, and repay the loan before I returned. When questions arose about the trust, she fabricated the certificate and found a closing agent willing to process documents without ever seeing me.
“And the eight hundred thousand?” I asked.
“It’s gone.”
I already knew that. I had just needed to hear her say it without pretending I was the problem.
The police investigation took months. The closing agent was investigated for the false notarization, the bank reviewed its title and identity checks, and Megan and Mom were questioned about their statements and the money transfers. Rebecca filed a civil action to clear the fraudulent security deed from the property’s title. We did not pretend that a temporary court order had magically erased the loan.
Alden Bank ultimately agreed to release its claimed lien as part of a settlement resolving my title action. It pursued recovery from the people involved in the fraud instead. Megan pleaded guilty to fraud and forgery charges and received a sentence that included restitution and supervised probation. Mom accepted a separate plea agreement for her part in the false documents and was ordered to repay the money traced to her debt.
The first time Mom called after sentencing, she asked whether we could “put all this behind us.”
“You had a choice,” I told her. “You could have called me. You could have said no. Instead, you put your signature beside a lie about your own daughter.”
She cried and told me she loved me. I believed she felt something she called love. I also knew I could not build my life on it anymore.
I changed the locks, ended Megan’s access to my accounts, and arranged for a professional service to handle the house whenever I traveled. On the afternoon the bank recorded its lien release, I stood in my kitchen holding the confirmation from Rebecca. No auction sign waited outside. No stranger had a claim to my front door.
I put the paper in a folder beside the real deed.
Megan thought stealing my signature made her debt mine. But the deed she copied no longer controlled ownership of my home. Her mistake exposed the scheme. The evidence finished it.
I had spent six months away earning a living. I came back to find my family trying to sell the life I had built.
They lost the house they thought they could take. I kept mine, and I finally stopped mistaking their demands for love.