“She’ll sign eventually,” my mother said.
My father’s laughter came through my phone so clearly that I nearly dropped it. “Of course she will. Claire was stupid enough to let us into a $980,000 house without asking a single question.”
I sat in my car, still connected to a call my mother thought she’d ended. She’d called about an insurance folder. I heard goodbye, then her phone scrape against my kitchen counter. She hadn’t hung up.
I stopped reaching for my keys.
“What if she reads the last page?” my father asked.
“She won’t. I’ll tell her it’s a routine update to her homeowners policy. She’s signed things for me before.”
“And the four hundred and twelve thousand?”
“The lender is set to wire it Friday. I want her to sign tomorrow so she can’t dispute the transfer.”
Nineteen days earlier, I’d welcomed my parents into my home after they claimed a burst pipe had flooded their house. I’d given them the guest suite, a garage remote, and the spare front-door key. My mother had hugged me and called me her lifesaver. Now I could hear her planning something with my father at my own kitchen table.
My house was the one thing I’d never allowed them to control. I’d bought it after selling my small software business, and the deed was in my name alone. I owed no mortgage. They’d called it extravagant, but clearly they’d calculated its value.
“If she refuses, tell her Logan is going to lose everything,” my father said.
Logan was my younger brother. Our parents had used his struggling contracting company to ask me for money three times that year. Each time, I’d offered to pay for financial counseling. Each time, they’d demanded cash instead.
“She might call a lawyer,” Dad muttered.
Mom gave a short laugh. “Not before Friday. She trusts me.”
Paper slid across the counter. A pen tapped wood.
“What did Martin notarize?” Dad asked.
“The transfer.”
“But Claire was in Chicago that day.”
My hands went numb. I’d been in Chicago for a work conference, hundreds of miles from the home they were sitting in.
“Evelyn,” Dad said, his voice suddenly thin, “tell me you didn’t file that thing without her.”
My mother paused, then answered with the same gentle voice she’d used to sing me to sleep as a child.
“She doesn’t have to sign to lose the house, Frank. Her signature is already on the deed.”
I stared at the call timer, still moving, and understood that whatever they’d done wasn’t a plan anymore. It had already begun.
My father swore. “You said Martin would meet her in person.”
“Martin stamped the transfer after I brought him the signature I’d copied from her old tax documents,” Mom said. “He knows us. He didn’t ask questions.”
“That’s forgery.”
“It’s family,” she snapped. “And tomorrow she’ll sign the ratification. Once that’s done, nobody will care how the first document got filed.”
“What if she doesn’t?”
“Then we get the money first and deal with her afterward.”
For another minute, they argued about an escrow officer, a private lender, and Friday’s deadline. My father said the loan proceeds would go directly to a company account. My mother warned him not to mention any of it to Logan. Then I heard her gasp.
“Frank. My phone is still on.”
The line went dead.
I wrote down every sentence I could remember before my hands stopped shaking. Then I searched the county recorder’s online index. A quitclaim deed had been recorded two days earlier, supposedly transferring my home from Claire Bennett to Bennett Property Partners LLC. My signature was on the scanned document. Underneath it was a notarial certificate signed by Martin Vale, my parents’ longtime friend.
The date was the same day I’d been at a conference in Chicago. My boarding pass was still in my email.
I called Rebecca Sloan, the attorney who had handled my home purchase. She told me a recorded deed did not make a forged transfer legitimate, but it could cloud my title and put the property at risk while the fraud was challenged. She asked for the recording information, my travel records, and the call history. She immediately contacted the lender’s escrow office, filed a written fraud report, and began preparing an emergency court request.
“Whatever happens tonight,” Rebecca said, “don’t sign a single page. And don’t confront them alone.”
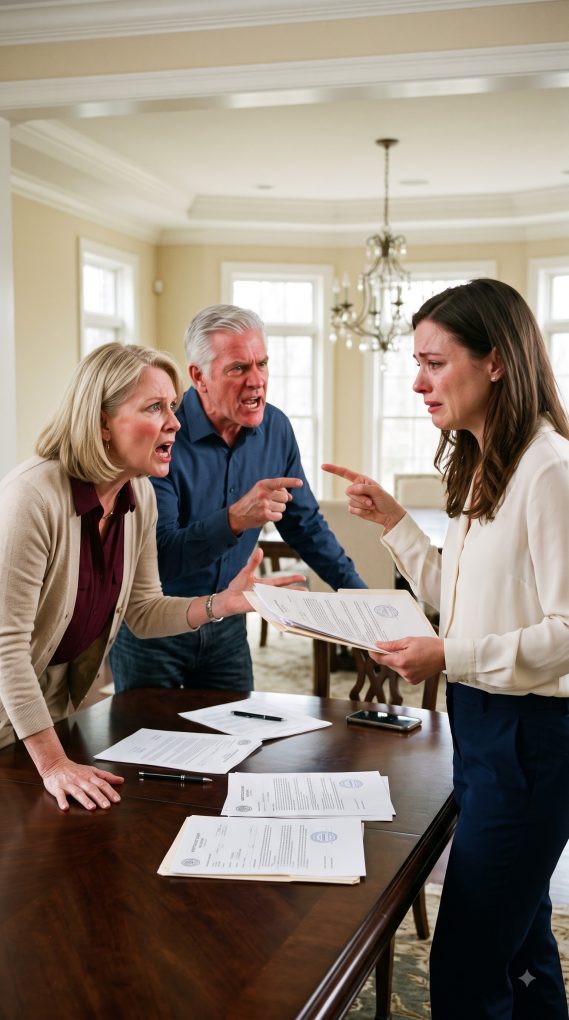
At six, I walked into my own dining room with Rebecca on a video call and my phone in my hand. My parents were waiting beside a neat stack of papers.
Mom pushed the folder toward me. “Just a few insurance corrections, sweetheart.”
I turned to the third page. Beneath the words “Confirmation of Prior Transfer” was the name of their LLC.
“Why does an insurance form say I gave away my house?” I asked.
My father’s face turned red. “Because family helps family. You live alone in a place this big while we’re drowning.”
“You’re not borrowing a bedroom,” I said. “You’re trying to borrow against my home.”
Mom stopped pretending to smile. “We raised you. Don’t make this ugly.”
My phone buzzed with a message from Logan: Don’t sign anything. My construction company closed four months ago. I don’t owe anybody that money. Ask Dad about the investor lawsuit.
Before I could speak, Rebecca sent another message. She’d obtained the lender’s preliminary closing package. Attached to the forged deed was a separate document bearing another fake signature of mine.
It was a personal guarantee for the entire $412,000 loan.
They weren’t simply trying to take my home. They were trying to leave me responsible for the debt, too.
“Rebecca,” I said into my phone, “tell me that document doesn’t count.”
“A signature someone forged doesn’t make you a willing guarantor, Claire. But we need to stop that loan from funding before it creates an even bigger legal mess.”
My mother lunged across the table and tried to close the folder. I pulled it out of her reach.
“You’re making a mistake,” she said.
“No. My mistake was giving you a key.”
Dad pointed toward the hallway. “Turn that phone off. We can settle this privately.”
Rebecca spoke before I could. “Mr. Bennett, the lender’s attorney has received written notice that Claire disputes both her signature and the transfer. No money has been released. You should preserve every document related to this transaction.”
For the first time, my father looked frightened.
Then the doorbell rang. Logan stood outside carrying a battered file folder. I let him in, and he looked from the papers on the table to our parents’ faces.
“You actually did it,” he whispered.
Dad barked his name like a warning, but Logan walked straight to me. His folder held a lawsuit against Dad’s investment partnership. Dad had borrowed from three investors to buy a commercial property that never closed, then spent much of the money on old debts. He had until Friday to repay $412,000 under a settlement agreement.
“My company wasn’t involved,” Logan told me. “They used my name because they knew you’d do anything to keep me from losing my business.”
“And their flooded house?” I asked.
Logan shook his head. “It was never flooded. Dad had already mortgaged it to the limit. They couldn’t borrow against it anymore.”
Mom reached for his arm. “We were trying to protect this family.”
He stepped away. “You told Claire I was desperate. You told me Claire had offered her house as security. You lied to both of us.”
My father sank into a chair. Mother didn’t. She lifted her chin and said, “If she’d just signed, we could have paid the loan back once the investment recovered.”
“What investment?” I asked. “The one that never closed?”
She stared at me with the stubborn fury of someone who had run out of stories.
“You have a beautiful home,” she said finally. “Your father and I sacrificed for you. We deserve something in return.”
I thought about the birthday cakes, the school pickups, the years I’d mistaken every act of parenting for a debt I would someday have to repay. My throat tightened, but I didn’t lower my eyes.
“You deserved to be treated with love,” I said. “You weren’t entitled to forge my name.”
I photographed the packet, took it with me, and drove to the police station with Logan. Rebecca received the originals the next morning. I spent that night at a friend’s apartment rather than sleep under the same roof as them.
By nine the following morning, the lender confirmed in writing that it had stopped the closing and would not advance the funds. The escrow officer sent Rebecca the application package and the identification records that had been used to represent me. They included a photocopy of an expired driver’s license that had disappeared from my desk drawer.
I was in Chicago on the date the notarized deed claimed I’d appeared before Martin Vale. My airline itinerary, hotel receipt, conference check-in, and work photographs established where I had been. My own doorbell footage showed Martin entering the house that morning and leaving eight minutes later. I wasn’t home at all.
A detective took formal statements from Logan and me. When investigators later questioned Martin, he acknowledged that he hadn’t witnessed me sign the deed. Rebecca told me the criminal investigation could take time, and that my ownership still needed to be established in the civil record.
My parents called seventeen times that weekend. The first messages were furious. The next pleaded for mercy. By Sunday night, Mom was crying into my voicemail.
“If your father loses everything, it will be because you wouldn’t help.”
I listened once. Then I saved it with the others.
Rebecca sent formal notice requiring them to leave under the applicable procedures. They could have forced us into another legal fight by staying. Instead, after the lender canceled the loan, they packed and moved out voluntarily. Logan witnessed the return of the garage remote and every key. Only then did I change the locks and security codes.
Over the next several months, Rebecca brought the evidence before a judge. The court declared the forged deed void and ordered the property records corrected. Because the lender had never funded its loan, no new loan lien attached to my home, and I owed none of the $412,000. Prosecutors eventually filed forgery-related charges against my parents and Martin. Their financial trouble remained theirs to answer for.
Logan apologized for staying quiet about the lawsuit when he first heard about it. I told him silence had helped them, even if he hadn’t understood the plan. He didn’t argue. We began rebuilding a relationship without allowing our parents to be the people who defined it.
The hardest part wasn’t the paperwork or the court hearing. It was realizing my mother had listened to me talk about how safe I finally felt in that house while knowing she was arranging to take it away.
Months later, she mailed me a letter. It contained no apology, only a question: Was a house really worth losing my family over?
I wrote one sentence on a sheet of paper, then decided not to send it.
I hadn’t lost my family over a house. I’d discovered what some of them were willing to do for one.
That evening, I sat at the kitchen table where they’d planned everything. My deed was secure, my name was mine again, and the spare key they had abused no longer opened the door. For the first time since they’d moved in, the silence felt like peace.