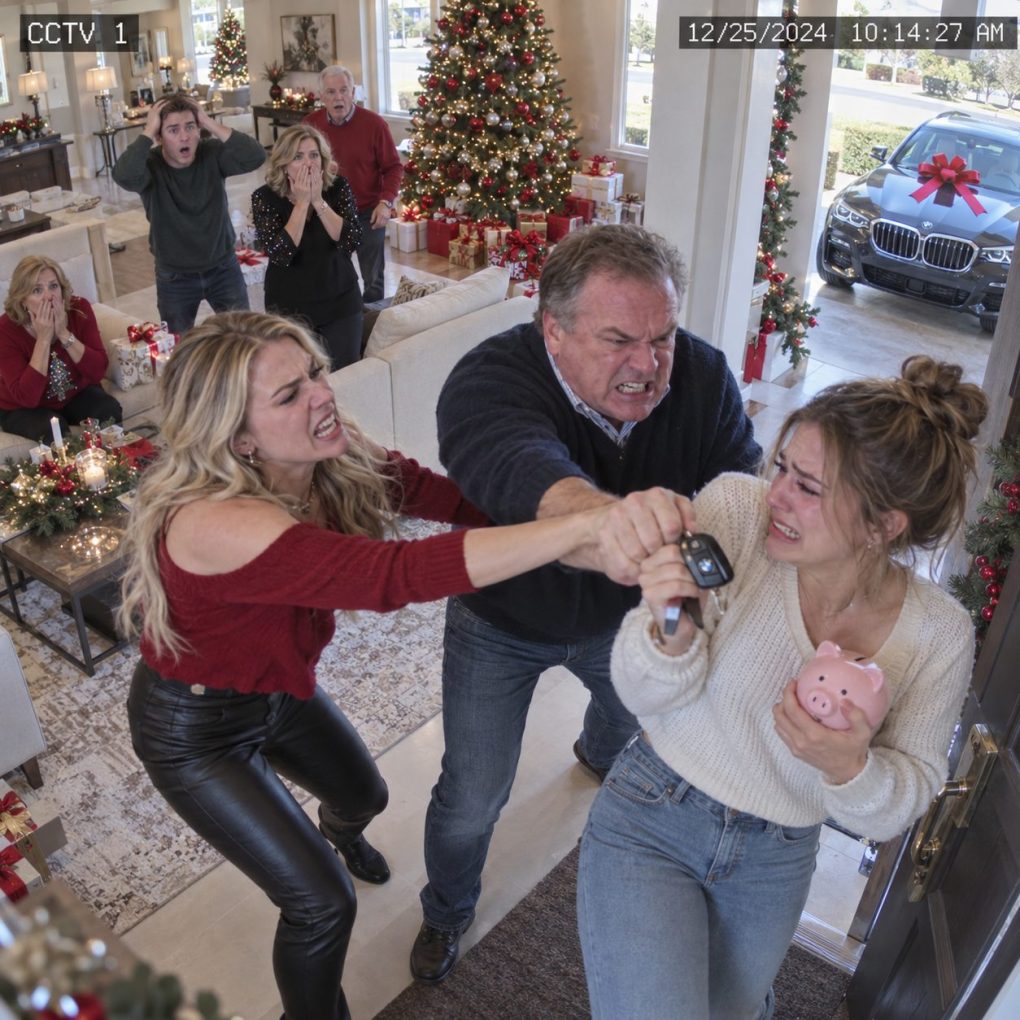
The BMW was parked in my parents’ driveway with a red bow wider than the windshield.
My sister, Brianna, screamed before Dad even finished saying, “Merry Christmas.”
Everyone rushed outside.
Mom cried.
Brianna jumped into Dad’s arms.
My uncle started filming while she ran her hands over the hood of the brand-new metallic-blue SUV.
“Sixty thousand dollars?” she gasped.
Dad smiled like he had just handed her the moon.
“Close enough.”
Then Mom turned to me.
“And we didn’t forget you, Claire.”
She reached beneath the Christmas tree and handed me a box small enough to fit in one hand.
Inside was a plastic pink piggy bank.
The price sticker was still attached.
$2.00.
Brianna laughed so hard she nearly spilled her champagne.
Mom smiled.
“You’re the saver in the family. It seemed appropriate.”
Twenty-nine years old.
I had paid part of my parents’ property taxes twice.
Covered Brianna’s rent for three months after she lost her job.
And six weeks earlier, Dad had called asking for my help with what he described as a “temporary credit problem.”
He said he needed my information to qualify for a better vehicle loan.
Not for Brianna.
For himself.
“I’m replacing the Tahoe,” he told me.
I refused to co-sign.
Dad called back the next day.
He said the dealership could structure things differently if I simply purchased the vehicle and he reimbursed me each month.
Again, I said no.
Then he became oddly quiet.
Now I was staring at a brand-new BMW.
Something about the license paperwork taped inside the windshield caught my attention.
I walked closer.
Brianna was still posing for photographs.
The temporary registration showed:
REGISTERED OWNER: CLAIRE MORGAN.
My heart stopped.
I opened the driver’s door.
“Hey!” Brianna snapped. “That’s mine.”
I pulled the paperwork from the glove compartment.
Retail installment contract.
Purchase agreement.
Insurance binder.
Every page carried my full legal name.
The financing balance was $58,740.
I had never signed any of it.
Dad came outside.
His smile disappeared when he saw the papers.
“What are you doing?”
“Why is this car in my name?”
Mom stepped between us.
“Don’t ruin Christmas.”
I looked at Dad.
“Did you buy Brianna a car using my credit?”
“It’s complicated.”
“No. It isn’t.”
Brianna grabbed the keys from the console.
“Dad bought it for me.”
I took them back.
“The title says otherwise.”
She stared at me.
“You wouldn’t.”
I already was.
I got into the BMW.
Dad slapped his palm against the window.
“Claire!”
I lowered it two inches.
“If this is my car, I’m taking it.”
Mom shouted that I was jealous.
Brianna called me insane.
I drove away.
Forty minutes later, Dad left a voicemail.
“Return the car tonight or we’ll report it stolen.”
I played it twice.
Then forwarded it to my attorney.
She called me immediately.
“Claire, do not hide the vehicle. Bring it somewhere secure and preserve every document.”
“Why?”
“Because if the registration is genuine, they may have created a loan in your name.”
My stomach dropped.
Then she asked one more question.
“Did your father ever have access to a copy of your driver’s license?”
I remembered the mortgage paperwork I had helped my parents with the previous spring.
“Yes.”
Silence.
Then she said:
“Check your credit report now.”
I did.
The BMW was not the only account I found.
There was another loan.
$41,600.
Opened three months earlier.
And the borrower was supposedly me.
The second account was a personal loan from an online lender. I had never applied for it. My attorney, Rachel Kim, told me to freeze my credit immediately, dispute both accounts formally, and avoid accusing anyone of identity theft until the lenders preserved their application records.
The BMW dealership confirmed the purchase had been completed four days earlier. According to its file, I had bought the vehicle myself and authorized Brianna as an additional driver. Dad had handled most of the communication, claiming I was working out of town and wanted the car delivered to the family home as a Christmas surprise.
The signatures looked like mine because they had been copied from older documents. One came from the property-tax authorization I signed when helping my parents the previous spring. Another matched a scanned signature from a family insurance form. The dealership had accepted electronic execution after receiving identification images bearing my name.
The temporary registration was genuine. The vehicle had been titled to me because the financing was supposedly mine. Brianna had no ownership interest at all. Dad had given her a sixty-thousand-dollar Christmas gift that legally and financially belonged to someone else.
The personal loan was worse. Its proceeds had been deposited into a joint checking account held by Mom and Dad. Bank records later showed most of the money went toward credit-card balances, overdue property taxes, and a $12,000 transfer to Brianna.
When Rachel asked whether I had ever authorized that loan, my answer was simple: no. The lender’s login records showed the application originated from my parents’ home internet connection while I was attending a conference in Denver. My travel records placed me more than a thousand miles away.
Mom called constantly. Her first argument was that Dad intended to make every BMW payment. Her second was that I had “better credit than everyone else” and therefore nobody was really hurt. Rachel told me not to argue. Intent to repay did not equal permission to borrow in someone else’s name.
Brianna reacted differently. She accused me of stealing her Christmas present. I sent her one photograph of the registration showing my name. She replied, Dad said you agreed to this months ago. For the first time, I wondered whether she had been lied to too.
That possibility did not last long. The dealership produced a text exchange from Dad’s phone. Brianna had written, Will Claire see the loan before Christmas? Dad answered, Not unless she checks her credit. She never does. Brianna replied with three laughing emojis.
I stopped feeling sorry for her.
The dealership placed the vehicle in secure storage while the financing dispute was investigated. I did not keep driving a sixty-thousand-dollar car I never wanted. The lender suspended collection activity connected to the disputed loan while reviewing the documentation.
Then Rachel obtained the full application package for the $41,600 personal loan. Attached to it was a document labeled Borrower Income Verification showing my salary, employer, and direct-deposit history.
The salary was correct.
The employer was correct.
The bank deposits were correct.
Someone had uploaded three months of my actual pay stubs.
Only two people besides me had ever seen those documents.
My mortgage broker.
And my mother.
Mom admitted first that she had provided my pay stubs. She claimed Dad told her I had agreed to help refinance family debt and that the documents were needed only for preliminary qualification. That explanation became harder to maintain once investigators showed her the completed loan application bearing my copied signature.
Dad eventually admitted arranging both loans. His defense was not that I had signed them. He said he believed I would forgive him once I understood how desperate the family finances had become. He had turned anticipated forgiveness into advance permission.
The BMW financing was unwound after the lender concluded the application was unauthorized. The vehicle went back through the dealer and finance process rather than becoming my surprise Christmas prize. I did not receive a free car, and Brianna did not keep one purchased through a disputed loan.
The personal loan required more work because much of the money had already been spent. The lender pursued recovery through the appropriate channels while my attorney helped correct the account on my credit file. I preserved every document and cooperated instead of trying to negotiate privately with my parents.
Brianna eventually admitted she knew Dad was using my identity for the BMW application. She said she believed it was “basically okay” because he planned to make the payments and because I earned more than she did. I asked her whether she would have signed if the loan had been placed in her name for my Christmas gift. She did not answer.
My parents’ finances were worse than anyone had realized. Years of credit-card debt, tax arrears, and refinancing had left them with almost no flexibility. Dad had reached the point where my credit looked less like mine and more like a family resource he felt entitled to use.
That Christmas ended our old relationship. I did not cut them off forever, but I froze every financial connection. No shared passwords. No access to statements. No copies of identification. No “temporary” help that required handing over documents they could reuse later.
The legal consequences were handled through the lenders, attorneys, and authorities involved. I stopped fantasizing about dramatic punishment. What mattered to me was restoring my credit, separating my identity from their debt, and making sure no new account could be opened without my direct approval.
Months later, Mom mailed me the pink piggy bank. No note. Just the same two-dollar sticker still underneath. I almost threw it away. Instead, I put it on a shelf in my office.
It reminds me of the exact moment my family revealed how they saw me. Brianna deserved a sixty-thousand-dollar BMW because she wanted one. I deserved a plastic joke because I was “good with money.” And being good with money apparently meant my name, salary, and credit were available whenever the family needed them.
Dad thought his voicemail would scare me into returning the car.
“Return it or we’ll report it stolen.”
He had forgotten one small problem.
The car was legally registered to me because he had put my name on every document.
And once I looked closely enough to see that, I found the much bigger truth underneath:
the BMW had never been the gift.
My identity was.
They had simply been giving pieces of it away without asking.