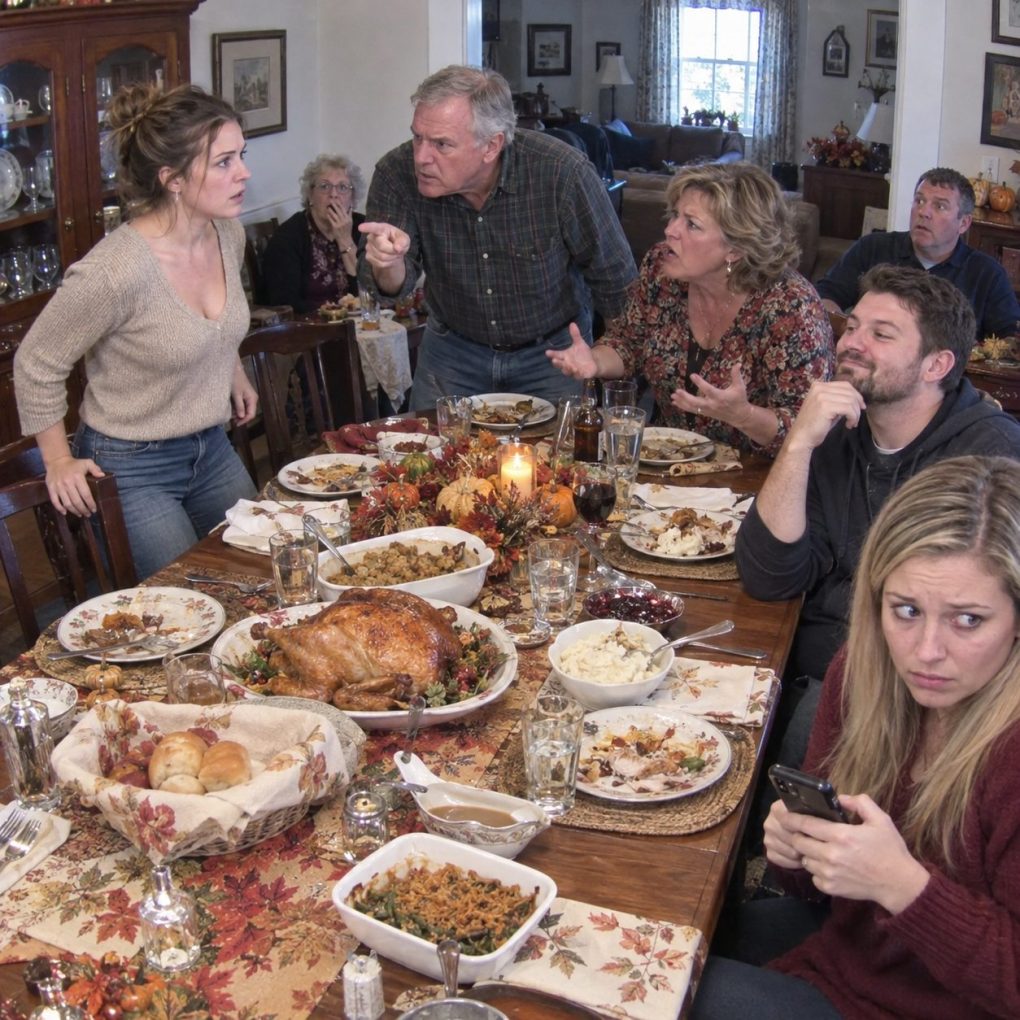
You’re thirty-two. It’s time to move out, Dad announced halfway through Thanksgiving dinner. My unemployed thirty-five-year-old brother, Ryan, smirked over his turkey. I set down my fork. All right, I said. Then Mom leaned forward. You’ll still pay our $1,845 mortgage, right? I told her no. Nobody touched dessert.
My name is Samantha Blake, and I’m a respiratory therapist in Columbus, Ohio. Three years earlier, Dad said his reduced work hours had put the family home at risk. I agreed to cover the mortgage directly while living there, expecting him to resume payments when his finances improved.
Thirty-six payments came to $66,420. I also bought groceries and handled most utility bills. Whenever I asked about Dad’s finances, Mom said the household was barely surviving. Meanwhile, Ryan lived upstairs without contributing, sleeping until noon and announcing a new business idea every month.
At Thanksgiving, he wanted my room for a recording studio. Dad said I needed to become independent, while Ryan needed a place to pursue his dreams. I asked why independence applied only to me. Dad banged his fist on the table and ordered me out before New Year’s.
Mom followed me to the hallway. You can’t abandon us now, she hissed. I reminded her she was the one asking me to leave. She said the house would go into foreclosure without my paycheck. I said she’d have to make another plan.
I spent the night at my friend Kate’s apartment. The next morning, my younger sister, Lily, sent me a photograph. She’d stopped by to retrieve a suitcase and found a folder open on Dad’s desk. I enlarged the image until the figures became clear.
Eight months earlier, my parents had taken a home-equity loan against the house, receiving $112,400 after closing costs. Beneath the closing statement lay a bank confirmation showing $96,000 transferred to Ryan. The memo read: Down payment, Brookside duplex.
I called Lily. She said Ryan had purchased a rental duplex in his name but kept living at home. One unit was occupied; the other was advertised online. Mom had told Lily not to mention it because I might become jealous.
Jealous wasn’t the word. I’d skipped vacations, postponed buying an apartment, and worked extra hospital shifts because Mom cried about losing the house. Yet they’d borrowed against its equity to help Ryan acquire property while demanding I keep paying the mortgage.
Then Lily sent a second photograph: a handwritten budget taped inside the same folder. Beside the next six mortgage due dates, Dad had written Samantha pays. At the bottom was Ryan’s new studio budget. They hadn’t forgotten my sacrifice. They’d built their future around it.
I didn’t storm back into the house. First, I checked the county property records. Ryan’s name appeared on the Brookside duplex deed, dated eight months earlier. The online rental advertisement matched its address. My parents hadn’t merely discussed helping him; they’d already helped him buy property.
I confirmed with the mortgage servicer that I wasn’t a borrower. My automatic payments hadn’t made the mortgage mine, and I had never signed a guarantee or promised to keep paying after I left. I canceled future transfers and downloaded dated receipts for every payment I’d made.
A housing attorney explained that my payments might be viewed as contributions toward living expenses rather than a recoverable loan. There was no written promise to reimburse me or give me ownership. It hurt, but I preferred the truth to family fantasies.
I sent my parents a brief message saying I’d collect my things that weekend and wouldn’t pay another installment. Dad called within a minute. He said a responsible daughter wouldn’t abandon them. I asked why a responsible father had concealed their home-equity loan.
Silence followed. Then Mom admitted they had used the money to help Ryan buy the duplex. It was an investment for the family, she insisted. I asked whether I owned any part of it. No, she answered. Would Ryan be making their mortgage payment instead? Another silence.
On Saturday, Kate and Lily helped me pack. Ryan lounged in the kitchen, complaining that I was being dramatic. He claimed the duplex hardly made a profit after repairs. I wished him success, but refused to finance him. He stopped smiling when I mentioned his two rental units.
Dad appeared with a spreadsheet showing how badly they needed my salary. He’d resumed full-time work the previous year, something he had never mentioned. Their budget included Ryan’s car insurance, his streaming subscriptions, and monthly transfers labeled investment support. My name appeared only beside the mortgage.
I asked Dad why he hadn’t told me his hours had returned. He said he feared I’d stop helping. That admission hurt worse than his Thanksgiving announcement. For three years, he’d let me believe their only protection against foreclosure was my exhaustion.
Mom offered to let me stay another six months if I continued paying. I refused. She accused me of throwing away our relationship over money. I told her the money revealed how she’d valued me. I loaded my final suitcase into Kate’s car and left my key on the table.
A week later, Ryan said their next mortgage payment hadn’t arrived. I forwarded it to Dad and reminded Ryan that he owned income-producing property. Then I opened a savings account labeled My Home and made my first deposit without apologizing to anyone.
The first month was difficult. Kate let me stay while I searched for a rental. I’d spent years organizing my shifts around their bills. Now nobody asked me for money. But I slept better.
Mom called whenever a mortgage notice arrived. I didn’t ignore genuine emergencies, but I stopped treating her monthly bill as mine. I suggested calling the servicer and a housing counselor. She called that cold. I called it necessary, especially after she asked whether I could at least cover the next installment.
Ryan refused to contribute at first. Then Dad showed him the household budget and asked him to use some rental income toward their expenses. They argued for days, and I was relieved not to be in the middle of it. The duplex needed repairs and had its own mortgage; profits were modest.
Dad finally admitted he’d been chasing a plan in which Ryan became a property investor while I quietly paid the family home’s bills. He thought I’d eventually marry and leave, so he wanted Ryan financially secure. I asked where my future fit.
I received no satisfying answer. Instead, Dad began reviewing his expenses and met with a nonprofit housing counselor. My parents sold a second vehicle, reduced household spending, and started making their own mortgage payments. The bank didn’t erase their problems, but no foreclosure notice appeared during those months.
I moved into a modest one-bedroom apartment near the hospital. Rent and utilities cost less than what I’d been paying at home. Finally, my checking account grew. I bought a secondhand sofa and enrolled in a postponed certification course.
Lily visited with pizza and helped assemble a bookshelf. She apologized for not speaking sooner. I told her she wasn’t responsible for our parents’ choices. She’d told me the truth without asking for anything. That was enough, and I knew she’d taken a risk by speaking up.
At Christmas, Mom asked if I’d come for dinner. I said yes, provided we wouldn’t discuss my money or the mortgage. She agreed. The meal was awkward, and Ryan barely spoke. But Dad thanked me for the years I’d helped without suggesting I owed him another payment.
I didn’t forget the Thanksgiving table or the handwritten budget listing my name beside six future bills. I also didn’t demand instant forgiveness. My parents could rebuild our relationship by respecting my boundaries while I rebuilt my savings.
Six months later, I toured a small condominium with a sunny kitchen. I hadn’t saved enough for a down payment yet, but for once the possibility felt real. Dad had told me to grow up and move out. He’d meant it as punishment. I finally understood it was freedom.