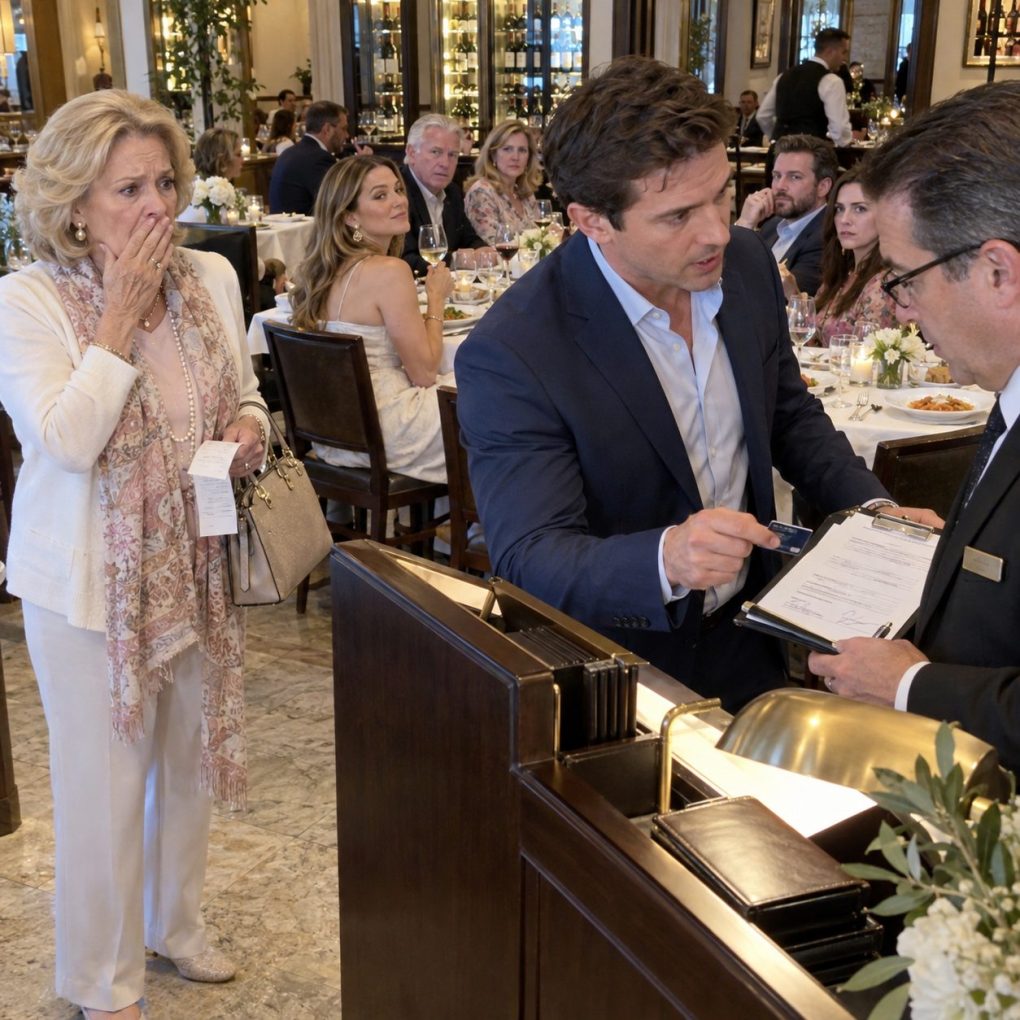
My son forgot Mother’s Day until I heard him at the manager’s desk, giving out my private membership number. Colin, thirty-nine, had brought his wife’s entire family to Bellavista, Boston’s most expensive Italian restaurant. He was charging $38,000 to my account. Then I saw the authorization form: ACCOUNT HOLDER MEDICALLY INCAPACITATED.
I was standing behind him, holding the receipt for the lasagna I’d eaten alone. The form bore my name, an imitation of my signature, and a document claiming Colin had power of attorney over my finances. It even listed a doctor’s opinion that I’d developed dementia.
I’m Margaret Hale, sixty-five, a retired librarian. After my husband, Thomas, died, Bellavista converted the deposit for his canceled retirement celebration into $43,000 in transferable event credits. The balance remained mine, reserved for a scholarship dinner in his memory.
Colin knew about the credits because he’d helped me cancel the celebration. I’d invited him to lunch that morning, but he hadn’t answered my calls. Now his in-laws occupied the private dining room while he arranged a $4,000 banquet and $34,000 in prepaid future events for them.
I leaned toward the manager. Please stop this transaction, I said. I’m Margaret Hale, and I authorized none of it. Colin turned so sharply he knocked his pen to the floor. His wife, Brianna, appeared behind him, still holding a champagne flute.
Mom, Colin whispered, you’re supposed to be home. I asked why his paperwork said I couldn’t make decisions for myself. He insisted it was a temporary administrative shortcut. The manager withdrew the unsigned restaurant charge slip and said the account would be restricted pending verification.
I asked to see the attached power of attorney. It carried a notary’s seal dated six weeks earlier, when I had been volunteering at the public library. I had never signed it. Worse, its broad language covered bank accounts, real estate, and investments, not merely restaurant reservations.
Brianna glanced at the pages. Colin told me you’d appointed him to handle everything since your diagnosis, she said. There is no diagnosis, I answered. Her expression collapsed. Behind her, relatives began rising from their dinner table, sensing something was wrong.
The manager gave me copies and agreed to preserve transaction records. I stepped outside and called my attorney before contacting my bank. Colin followed, begging me not to make a scene. He said his business was drowning, and his in-laws had already invited guests to expensive celebrations.
Then I noticed a handwritten note clipped to the forged document: Present this same authorization to the bank on Monday. My knees weakened. The $38,000 wasn’t the end of Colin’s plan. It was his test run.
My attorney, Elaine Brooks, asked me to preserve every page and not confront Colin alone. She contacted Bellavista’s compliance manager, who confirmed the $38,000 charge had never been completed. The club froze account transfers until it could verify my identity in person.
I called my bank’s fraud department and explained that someone was presenting a power of attorney I had never signed. The bank recorded my warning and reviewed any attempted transactions. Elaine helped me file a police report and arrange monitoring of my property records.
The doctor’s letter was the easiest part to disprove. My primary-care physician confirmed she’d never diagnosed me with dementia or issued the letter. The supposed notary’s office later reported that the certificate number and stamp details didn’t match its records. Investigators asked for the originals.
Three days later, an employee at my credit union called about an incomplete application for a $95,000 line of credit secured against my house. Colin’s name appeared as my purported financial agent. No loan had closed, but copies of the same suspicious authorization were attached.
I remembered how often he’d offered to handle my paperwork after Thomas died. I’d mistaken his persistence for concern. During my grief, I’d shared statements and account information with him. Knowing my private details had helped him sound believable to strangers. I changed my online passwords and stopped sharing financial statements with relatives.
Brianna requested a meeting at Elaine’s office. She brought messages in which Colin claimed I was declining mentally and wanted him to manage the family money. He’d also told her my savings were abundant and that spending the dining credits would make no difference.
She admitted she’d enjoyed the extravagant Mother’s Day lunch without wondering why I wasn’t there. I told her the humiliation mattered, but the fraudulent paperwork mattered more. She nodded and handed over screenshots showing Colin planned to transfer restaurant credits into event bookings for her relatives.
Colin called that evening, angry that Brianna had spoken to me. He said a good mother would help her son avoid bankruptcy. I told him he could ask for financial help, but he couldn’t invent a medical condition and sign my name to get it.
Police interviewed the restaurant manager and sought records from the credit union. Elaine notified relevant institutions in writing that I disputed the purported authority. We also reviewed whether any legitimate document needed revoking. There was no instant legal button to undo the damage to my trust.
One week later, Colin appeared at my door with flowers. He said he’d been afraid I’d say no. I looked at him through the glass and answered, That’s exactly why you needed to ask. I didn’t open the door.
The investigation continued for months. Detectives compared the questioned signatures with authentic examples and traced the false doctor’s letter and loan application. Prosecutors eventually charged Colin with forgery and attempted financial fraud. He was presumed innocent while the case proceeded.
Bellavista restored full access to my account after verifying my identity and confirming the disputed charge had never posted. The credit union rejected the incomplete loan application. I paid for legal advice and additional account safeguards, but neither the house nor the event credits had changed ownership.
Brianna moved temporarily to her sister’s apartment. She told me Colin had concealed mounting business debts and promised her parents a lavish anniversary celebration. She hadn’t known the authorization was forged. I accepted her explanation cautiously; she still had choices about what she’d believed.
Colin eventually pleaded guilty to forgery under an agreement reviewed by the court. He received probation, financial monitoring conditions, and an order to reimburse documented losses. The case didn’t give me back the son I thought I’d raised, and it didn’t turn me into a vindictive mother.
I stopped speaking with him directly for a time. Through counsel, I made clear he couldn’t access my accounts, represent himself as my agent, or contact financial institutions on my behalf. I updated my estate documents, not because I wanted revenge, but because my decisions had to remain mine.
That autumn, I booked a smaller scholarship dinner at Bellavista in Thomas’s memory. I invited former colleagues, neighbors, and young people studying library science. I used some of the credits and retained the rest. The event was thoughtful and affordable.
When the manager asked whether anyone else was authorized to sign, I answered no. He apologized again for allowing Colin’s documents to reach the approval stage. I thanked him for preserving them instead of quietly deleting the records when I challenged the transaction.
During the dinner, I spoke about Thomas, who’d taught our son to repair bicycles and return borrowed books. I didn’t mention the criminal case. I wanted the evening to be about what my husband valued: honesty, curiosity, and helping someone without expecting repayment.
Colin wrote me a letter afterward. He said he finally understood that inventing my illness was crueler than taking money. I read it twice and placed it in a drawer. Perhaps someday we’d talk with professional help. An apology alone couldn’t rebuild trust.
On Mother’s Day, I’d eaten alone while my son celebrated someone else’s family using my name. I had thought the worst part was being forgotten. But the terrifying form revealed something worse: he’d decided my voice no longer mattered. The life I’d built was still mine, and I would speak for myself.