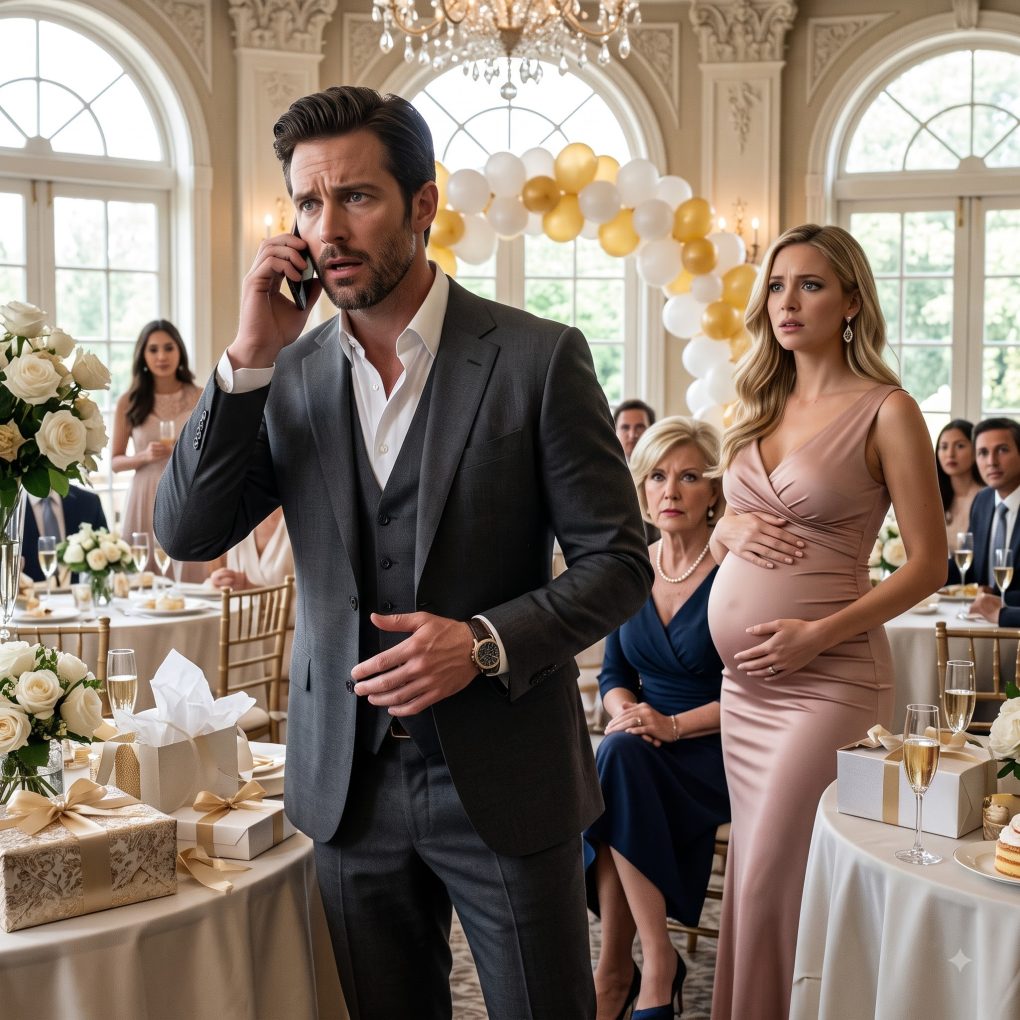
The bank called my husband in the middle of his mistress’s lavish baby shower, and within thirty seconds, his entire life began to collapse.
I wasn’t there to witness it, but one of the guests sent me a video later. My husband, Michael Anderson, stood beneath a balloon arch in a rented country club ballroom, holding a glass of champagne while his pregnant mistress, Vanessa Cole, opened designer baby gifts. His mother, Patricia, sat beside her, smiling as if the woman who had destroyed my marriage were already part of the family.
Then Michael’s phone rang.
He glanced at the screen and frowned. “It’s the bank. This can wait.”
He declined the call.
It rang again.Vanessa laughed and waved toward the guests. “Answer it, sweetheart. Maybe they’re calling to congratulate you on becoming a father.”
Michael stepped away from the table and answered impatiently. Within seconds, his expression changed. The smile disappeared. His face drained of color, and his hand tightened around the phone.
“What do you mean the account is frozen?” he demanded.
Across the room, Vanessa stopped unwrapping a silver-plated baby rattle.
I knew exactly why the bank was calling. I had been waiting for that moment for three days.
Michael had filed for divorce six weeks earlier. He did it on a Tuesday morning, leaving the papers on our kitchen island beside his coffee cup. He told me he wanted a fresh start and claimed our marriage had become an obstacle to his happiness.
What he didn’t mention was Vanessa, his twenty-nine-year-old assistant, who was already five months pregnant.
He also didn’t mention that he expected me to keep paying his mother’s monthly allowance, maintain the house he planned to leave behind, and quietly accept the financial obligations he had grown accustomed to enjoying.
For seven years, I had transferred $4,000 every month to Patricia. Michael insisted she needed it, although she lived in a paid-off condominium and received retirement benefits. I had also covered most of our household expenses because my consulting business earned more than his salary as a regional sales director.
When he filed for divorce, he assumed nothing would change.
He was wrong.
The house was legally mine. I had purchased it before our marriage, and my attorney confirmed that the title and the separate-property records were in order. Once Michael moved out, I listed it, completed the sale, and transferred my funds into an account he could not access.
I also canceled Patricia’s allowance.
I wasn’t trying to punish an elderly woman. I was ending a financial arrangement that Michael had treated as his permanent entitlement.
But the bank call had nothing to do with the house sale itself. Three days earlier, my attorney had discovered something in the financial disclosures Michael submitted during the divorce.
Something he had forgotten I knew how to investigate.
At the baby shower, Michael listened to the banker for nearly a minute before whispering, “No. That can’t be right. My wife doesn’t have the authority to do that.”
Then the banker apparently corrected him.
I could tell from the video because Michael suddenly looked toward Vanessa, who was staring at him with growing alarm.
And when he finally spoke again, his words made everyone nearby go silent.
“Wait—you’re saying the loan was secured by the house?”
I smiled when I heard that question.
Because the house he thought he still had a claim to was only the beginning.Michael left the baby shower before Vanessa had finished opening her presents. According to the woman who sent me the video, he didn’t explain anything to the guests. He simply shoved his phone into his pocket, grabbed his jacket, and walked out while Vanessa followed him in tears.
By that evening, my phone had received seventeen missed calls from him.
I didn’t answer.
Instead, I sat across from my attorney, Lauren Mitchell, in her downtown Chicago office while she reviewed the documents that had triggered the bank’s call.
“Your husband has a serious problem,” Lauren said, sliding a folder across the desk. “But I want you to understand exactly what it is before you decide how to respond.”
Michael had been working on a small real-estate investment project with two business partners. Months before filing for divorce, he had borrowed $280,000 through a private commercial lender, claiming the money would finance a property renovation.
The loan application included financial statements that overstated his income and listed assets he did not own outright. Worse, the lender’s file contained a document suggesting that the loan was secured by the equity in our marital residence.
There was just one problem.
I had never signed a mortgage, guarantee, or authorization for that loan.
And the house was not an asset Michael could pledge without my participation.
“He may have submitted inaccurate information,” Lauren explained. “We’re not going to accuse him of fraud until we know who prepared these documents and what the lender relied on. But the bank has now flagged the file for review.”
“Why did they call him during the shower?”
“The lender attempted to verify the collateral after receiving information that the property had been sold. The sale itself was lawful. The issue is why your husband represented that the house was available as security.”
I stared at the paperwork.
Michael had always been careless with money, but I had never imagined he would use my property to support a business deal without telling me.
For years, I had trusted him to manage our joint expenses. I paid the mortgage, property taxes, insurance, and most of our daily bills. He handled certain investment accounts and insisted he was building something for our future.
Apparently, he had been building something for himself.
When I finally listened to his first voicemail, he sounded furious.
“You need to call me back immediately. Whatever you told the bank, fix it. You sold the house without considering the consequences for me. My mother is already upset because you cut her off, and now this lender is threatening legal action. We’re still married until the divorce is finalized, and you can’t just destroy everything because you’re angry.”
I replayed the message twice.
Not once did he ask whether I was safe, whether I had somewhere to live, or whether I understood what had happened. He spoke as though my only purpose was to repair the consequences of his decisions.
I returned his call that afternoon, with Lauren listening on the other line.
“I didn’t contact the lender to make trouble for you,” I said. “They contacted you because they discovered the property had been sold and needed to verify the collateral.”
“You knew about the loan!”
“I knew you were investing in a renovation project. I didn’t know you were using my house as security.”
“You’re my wife!”
“Your divorce petition says you want to stop being my husband.”
He went silent.
Then he lowered his voice. “Vanessa is pregnant. I need stability right now. You can’t do this to my child.”
I felt a cold, familiar anger rise in my chest.
“You filed for divorce because you wanted a different life. You don’t get to keep my house, my money, and my monthly payments just because your new life has become expensive.”
“You’re making this personal.”
“You made it personal when you lied to me.”
He hung up.Over the following days, the consequences spread. The lender suspended further funding for Michael’s project pending a document review. His business partners demanded an explanation. Patricia called me repeatedly, accusing me of abandoning the family and insisting that her monthly allowance had been promised to her.
When I asked whether Michael had told her about the loan, she suddenly changed the subject.
That reaction bothered me.
Lauren agreed it was worth noting, but she warned me not to jump to conclusions. We were collecting records, not inventing a story to fit our suspicions.
Then Vanessa sent me a message.
It arrived just after midnight.
“I think you should know what Michael told me about the house. He said you had already agreed to help with the loan, and that you were only selling because you wanted to punish him. He also said the money from the house would be available to him after the divorce.”
I read it carefully before responding.
“I never agreed to the loan. If you have documents showing otherwise, send them to my attorney.”
A minute later, she sent a photograph of a printed email.
It appeared to show Michael telling his business partner that I had approved the arrangement months earlier. The message included my name and a description of our property.
But the email address wasn’t mine.
The signature at the bottom looked familiar, though—not because I had written it, but because I had seen it on documents Michael kept in his office.
Lauren examined the photograph the next morning.
“This could be important,” she said. “But we need the original email and its metadata. A screenshot alone doesn’t prove who sent it or whether it was altered.”
Before we could request the original, Michael’s attorney contacted Lauren with a proposal. Michael wanted to settle the divorce quickly. He would give up any claim to the house proceeds if I agreed not to pursue the disputed loan documents or discuss the matter with his business partners.
Lauren read the proposal twice.
“He’s trying to make the financial issue disappear inside the divorce settlement,” she said. “We should not agree to conceal anything that a lender or investigator may have a legitimate right to examine.”
I declined the offer.
That evening, Michael showed up outside my temporary apartment, looking exhausted and furious.
“You’re going to ruin my life over a piece of paper,” he said.
“No,” I replied. “I’m asking you to explain why your loan documents claim I agreed to something I never signed.”
He stepped closer, then stopped when he noticed Lauren’s car pulling into the parking lot.
For the first time since filing for divorce, he looked genuinely afraid.
And before he left, he said something that made me realize the loan might not have been his only secret.
“You don’t know what my mother did,” he whispered.For two days, I couldn’t stop thinking about Michael’s final words.
“You don’t know what my mother did.”
I wanted to call Patricia and demand an explanation, but Lauren advised me to wait. If she had information relevant to the disputed loan, an angry phone call could give her an opportunity to coordinate her story with Michael’s.
Instead, we requested the original loan application, the supporting financial statements, and every document that supposedly connected the loan to my house. Lauren also asked Vanessa to preserve the email she had received from Michael and provide the original message rather than a screenshot.
Three days later, the lender’s compliance officer agreed to a formal meeting.
I attended with Lauren. Michael arrived with his attorney, looking considerably less confident than he had at the baby shower.
The compliance officer placed several documents on the table.
“The loan was approved based on representations about the borrower’s income, available assets, and collateral,” she explained. “After the property sale, we discovered inconsistencies that required further review. We are not making a final determination today, but we need clear answers.”
Michael’s attorney immediately objected to questions about the divorce.
Lauren responded calmly. “The documents refer to property owned by my client. She did not authorize the use of that property as collateral. This is directly relevant.”
The compliance officer turned to Michael.
“Did your wife sign this authorization?”
Michael studied the page.
“I believed she had agreed to support the project.”
“That is not what I asked,” the officer said. “Did she sign it?”
He hesitated.
“No.”
A silence settled over the room.
Then the officer produced a second document: an email from Michael to his business partner, sent months before the divorce filing. It stated that I had approved the use of the house and that the necessary paperwork would be provided later.
Michael claimed the email referred to a conversation we had never had.
Lauren asked him to identify the authorization attached to the original application.
He couldn’t.
The lender’s review found that the signature attributed to me did not match my verified signatures on the property records. Investigators also found that several financial figures in the application required independent verification. The lender referred the questionable documents for further review and suspended the project’s financing.
No one declared Michael guilty of a crime in that meeting. That decision would depend on the evidence and the appropriate authorities. But the lender made one thing clear: I would not be responsible for a loan I had never authorized, and Michael could no longer rely on the house as collateral.
I thought that was the end of the mystery.
I was wrong.
Two weeks later, Vanessa contacted Lauren again. This time, she had original emails and bank statements that she said Michael had left in a shared cloud folder.
The documents revealed why he had been so desperate to settle the divorce quietly.
For nearly a year, Michael had been transferring money from an account associated with his investment project to cover expenses for Vanessa. Some payments were described as business travel or consulting costs. Others were payments to vendors for furniture, event deposits, and purchases unrelated to the renovation.
The money did not prove that every expense was improper, but it contradicted Michael’s repeated claim that the project had failed only because I sold the house.
More troubling was a message between Michael and Patricia.
In it, he discussed the loan and asked his mother to confirm that I had verbally approved using the property as collateral if anyone questioned him. Patricia replied that she would “support the family story,” but warned him not to send her anything in writing.
Lauren read the exchange without comment.
I felt sick.Patricia had spent years telling me I was the daughter she never had. I had paid for her dental work, helped replace her broken furnace, and transferred $4,000 each month because Michael insisted she could not manage without us. When I canceled those payments, she had accused me of cruelty.
Now I understood why Michael had warned me about her.
She had apparently known about the arrangement and had been prepared to support his version of events, although we still needed to establish exactly what she understood and whether she had participated in anything unlawful.
Vanessa also explained why she had sent me the email. Michael had told her the house sale would be temporary, that I would eventually agree to transfer part of the proceeds, and that he would use the money to secure a larger home for her and the baby. When the lender called during the shower, she realized his promises might never have been based on reality.
She had not contacted me out of kindness alone. She was frightened about the future of her child and wanted to know whether Michael had lied to her, too.
I didn’t blame her for asking questions. But I wasn’t going to rescue her financially.
“I’m sorry he misled you,” I told her during our meeting with Lauren. “But the baby is not my responsibility, and neither is the life he promised you.”
Vanessa lowered her eyes.
“I know.”
The divorce became more complicated, but not in the way Michael had expected. His attempt to negotiate away the loan dispute failed. The court process focused on the actual marital assets, documented contributions, and applicable law—not his claim that I owed him a comfortable landing after he chose to leave.
Because the house had been purchased before the marriage and my attorney had preserved the records showing its separate ownership, Michael had no automatic right to the sale proceeds. The final settlement addressed the limited marital financial issues that were supported by the evidence. I kept the house proceeds, while each party remained responsible for obligations legally attributable to them.
The lender continued its own review of Michael’s application. I never received a dramatic courtroom confession or a public announcement that solved everything overnight. Instead, there were requests for documents, formal interviews, legal bills, and months of uncertainty. That was how real consequences worked: slowly, carefully, and through evidence.
Patricia stopped calling after Lauren sent her a formal request to preserve any records related to the loan. Her monthly allowance never resumed.
Michael eventually lost his position after his employer learned that the financing dispute had affected a project he had represented as financially secure. His employer did not tell me every detail, and I did not need to know. I was no longer responsible for managing his reputation.
Vanessa gave birth to a healthy baby girl. She and Michael attempted to make their relationship work, but the trust between them had been damaged by the same pattern of promises and omissions that had destroyed our marriage. I heard they eventually moved into a modest rental and began working out their own financial arrangements.
I wished the child well. She had done nothing wrong.
As for me, I bought a smaller home near the lake, expanded my consulting business, and stopped confusing loyalty with an obligation to pay for everyone else’s choices.
Months after the divorce was finalized, Michael sent one last message.
“I never thought you would actually walk away.”
I read it once and set my phone down.
That was the truth of our marriage. He had mistaken my patience for weakness, my generosity for permanent permission, and my silence for agreement. He believed filing for divorce would free him from his responsibilities while leaving every benefit of our life together within reach.
He was wrong.
Selling the house had not been revenge. Canceling Patricia’s allowance had not been revenge. Refusing to accept responsibility for a loan I never signed was not revenge, either.
I had simply stopped protecting him from the consequences of his own decisions.
And the most satisfying part was not watching his world unravel at a baby shower.
It was realizing that, for the first time in years, I could build a future without asking whether my husband—or his mother—would approve.