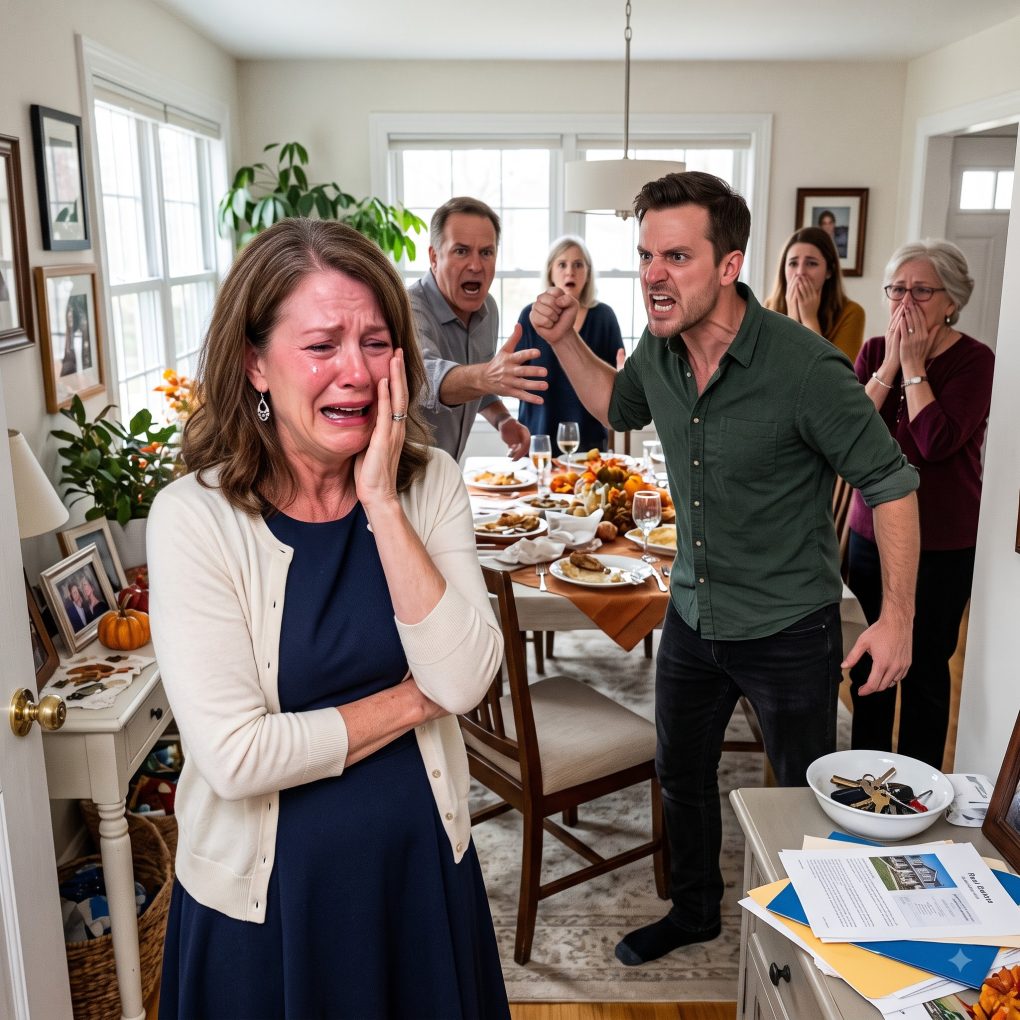
The first slap came so fast I thought Ethan had only brushed my face.
The second knocked my glasses onto my sister’s dining-room floor.
By the fifth, nobody was speaking.
By the twentieth, my left cheek was swollen, my lip was bleeding, and twelve members of my family were staring at my thirty-two-year-old son as if they no longer knew him.
It happened on Thanksgiving afternoon in Columbus, Ohio.
Ethan had been drinking since lunch. He was furious because I had refused to lend him another $18,000 for a business idea he could barely explain. When I told him I was done rescuing him, he laughed, called me a “controlling old woman,” and struck me again.
My brother Daniel finally dragged him away.
Ethan pointed at me from across the room.
“You’d have nothing without me,” he said.
That sentence stayed with me all night.
Because the truth was exactly the opposite.
Three years earlier, when Ethan’s credit collapsed after a failed restaurant venture, I had bought the little two-story house on Hawthorne Avenue for him. I paid the down payment, qualified for the mortgage, and kept the title in my name because the bank would not approve him. Ethan paid me monthly “rent,” though he told everyone the house was his.
The next morning, while he was at work, I called Martin Hale, a real-estate agent I had known for fifteen years.
“I want to sell Hawthorne,” I said.
He went silent. “Does Ethan know?”
“No.”
“Linda, he lives there.”
“I know.”
Martin warned me that selling an occupied property would be complicated. I told him I already had a cash buyer: a local investor who had once offered to purchase it as-is. By noon, documents were moving. By Monday, the investor increased his offer in exchange for a fast closing and taking responsibility for removing the occupant legally.
I signed.
At 4:17 p.m. on Friday, $186,430.12 landed in my bank account after the mortgage and closing costs were paid.
At 5:03, Ethan called.
“Mom,” he said, strangely calm. “Why is there a man on my porch measuring the windows?”
I looked at the purple bruise reflected in my bathroom mirror.
“Because I sold the house.”
The silence lasted six seconds.
Then Ethan whispered something that made my stomach drop.
“You just sold the wrong house.”
I thought he was bluffing.
Three days later, a certified envelope arrived from an attorney I had never heard of.
Inside were copies of two documents carrying my signature.
I had never signed either one.
And according to those papers, the $186,430 in my account did not belong to me.
The attorney’s letter came from a firm in downtown Columbus. It demanded that I place every dollar from the Hawthorne sale into escrow and warned me not to spend, transfer, or hide the money.
The first document was dated two years earlier. It claimed Ethan had given me $110,000 toward the purchase of the house and that I had agreed to hold legal title “for his sole benefit.”
The second was worse.
It said that if I ever sold the property, every dollar of equity belonged to Ethan.
Both pages had my name at the bottom.
Both signatures looked like mine.
For ten minutes, I sat at my kitchen table unable to understand what I was seeing.
Then I noticed the witness line.
Brooke Mercer.
Ethan’s wife.
I called my attorney, Rachel Kim, and drove to her office with the originals still inside the certified envelope. She read everything twice before looking up.
“Did you sign these?”
“No.”
“Did you ever agree verbally that the house was Ethan’s?”
“I told him he could live there as long as he paid me each month. That’s all.”
Rachel folded her hands. “Then we treat these as disputed documents. But Linda, do not touch that money.”
That was the first thing that frightened me.
The second came when Rachel pulled the county property records.
There had been no recorded transfer. No mortgage in Ethan’s name. No lien showing an ownership interest. On paper, I had been the legal owner when I sold the house.
“That helps,” Rachel said.
“Then why am I worried?”
“Because lawsuits don’t begin with truth. They begin with allegations.”
Two days later, Ethan filed one.
He accused me of fraud, conversion, unjust enrichment, and breach of trust. His complaint described me as a mother who had “retaliated against her son after a private family disagreement” by secretly selling a home he had paid for.
A private family disagreement.
That was what twenty blows became once an attorney typed them onto paper.
My family reacted exactly as families do when money enters a wound.
Daniel offered to testify about Thanksgiving.
My sister Melissa begged me to settle because she was terrified the case would divide everyone permanently.
My mother, eighty-one and exhausted by all of us, asked only one question:
“Is Ethan saying he bought the house?”
“Yes.”
She stared at me.
“With what money?”
That question mattered.
Ethan had never earned enough to produce $110,000.
Rachel subpoenaed his bank records.
That was when his confidence changed.
He stopped calling me angry. Instead, he began sending careful text messages.
Mom, this can still go away.
Mom, attorneys are going to take everything.
Mom, you know what we agreed.
I answered only once.
Then show me where the $110,000 came from.
He never replied.
A week later, Brooke called from a number I didn’t recognize.
Her voice was low and shaky.
“Linda, I need to tell you something before Ethan finds out I called.”
I stepped into my garage and closed the door behind me.
“Did you witness those papers?”
She started crying.
“I signed where he told me to sign.”
My hand tightened around the phone.
“Did you see me sign them?”
“No.”
“Then why did you tell an attorney you did?”
“I didn’t understand what he was doing at first.”
“At first?”
There was a long pause.
Then Brooke said, “The house isn’t the reason he’s suing you.”
I felt cold despite the closed garage.
“What is?”
She took a breath.
“Because if your lawyer gets his bank records, she’s going to find the account.”
“What account?”
Brooke didn’t answer.
Instead, I heard a door slam on her end.
A man’s voice shouted her name.
The call disconnected.
The next morning, Rachel called me before seven.
“We got the first batch of records,” she said. “You need to come in.”
“Did you find the $110,000?”
“No.”
Her voice was different now.
“We found where he claimed it came from.”
I drove downtown believing I was going to learn how my son had forged two documents.
I was wrong.
Those papers were only the smallest part of what he had done.
Rachel had printed nearly two hundred pages and arranged them across her conference table in colored stacks.
She pointed to the first stack.
“This is your savings account.”
I recognized it immediately. It was the account that held what remained of my husband’s life-insurance money after he died. I rarely touched it.
Then she pointed to another set of statements.
“This is an account owned by an LLC called Hawthorne Residential Services.”
“I’ve never heard of it.”
“I know.”
She slid the formation papers toward me.
The LLC had been created twenty-six months earlier. The mailing address was Ethan’s house. The contact email contained my first initial and last name.
And listed as an authorized member was me.
My full legal name.
My date of birth.
Part of my Social Security number.
For a moment, I could hear nothing except the soft hum of Rachel’s air conditioner.
“I didn’t open this.”
“I don’t think you did.”
She showed me the transfers.
Eight thousand dollars.
Twelve thousand.
Seven thousand five hundred.
Nine thousand.
The amounts moved out of my savings on irregular dates, passed through two accounts, and eventually appeared in the LLC account. Some were then transferred into Ethan and Brooke’s joint checking account. Others paid credit cards, a truck loan, restaurant debts, and what appeared to be gambling-related cash advances.
The total was $73,600.
I stared at the number.
“That still isn’t one hundred ten thousand.”
“No,” Rachel said. “The rest of his supposed contribution is listed as cash.”
“Cash he never had.”
“That is what the records suggest.”
I remembered something then.
Four years earlier, after my husband died, Ethan had helped me move all my bills online. He sat at my kitchen table with my laptop and set up automatic payments. I had given him temporary access because I was overwhelmed and could barely remember which companies needed to be called.
I changed my password later.
Apparently, not soon enough.
Rachel asked me to check whether I had ever received security alerts around the dates of the transfers. I searched my old email and found several notices saying my contact preferences had been updated. At the time, I assumed the bank had changed its system.
The phone number attached to those alerts was not mine.
It was Ethan’s old number.
I felt something inside me become very quiet.
Not angry.
Not shocked.
Just quiet.
Rachel said, “Linda, this has moved beyond a property dispute.”
I looked at her.
“What do I do?”
“You preserve everything. You report the unauthorized transfers. And you do not contact Ethan.”
That afternoon I filed a report with the bank’s fraud department. The next morning, with Rachel beside me, I spoke to a detective from the Columbus Division of Police.
I told him about the money.
Then I told him about Thanksgiving.
Until that moment, I had not filed a police report for the assault.
I had been embarrassed.
That seems ridiculous now, but embarrassment can make people protect the person who hurt them. I had spent my entire adult life explaining Ethan: his temper, his debts, his failed businesses, his promises, his apologies.
Twenty strikes in front of twelve witnesses finally ended my ability to explain him.
The detective photographed the fading bruises and took the names of everyone who had been in Melissa’s dining room.
Three days later, Brooke called Rachel instead of calling me.
She wanted her own attorney.
She also wanted to cooperate.
According to Brooke, Ethan had created the ownership documents after learning that I had begun discussing a will with an estate-planning lawyer. He was convinced I planned to leave the Hawthorne house equally to him and his sister, Claire.
He wanted proof that the property belonged only to him.
So he downloaded a legal template, changed the language, copied an old version of my signature from tax paperwork, and printed the pages.
Brooke had signed as a witness.
“Why?” I asked when Rachel told me.
“Brooke says Ethan told her you had already agreed and that the signature was just being recreated because the original document had been lost.”
I laughed once.
It didn’t sound like laughter.
“Did she believe that?”
Rachel hesitated.
“She says she wanted to.”
That answer made more sense than I wanted it to.
But Brooke had something more useful than an explanation.
She had photographs.
Ethan had taken pictures of the documents on their kitchen counter before mailing copies to an attorney. One photograph showed the top page before my forged signature had been added. Another, taken forty minutes later, showed the same page with the signature in place.
The metadata was still attached.
Then Brooke turned over text messages.
One from Ethan read:
If Mom ever tries to sell, this proves it’s mine.
Another said:
She won’t fight once she sees a lawyer letter.
That was the moment his lawsuit collapsed.
Rachel sent the evidence to Ethan’s attorney.
His attorney withdrew from the case eleven days later.
Ethan hired another lawyer, then another. The complaint remained active for several months, but the tone changed completely. He stopped claiming I had betrayed an agreement and began arguing that his years of payments and improvements gave him an equitable interest in the property.
Rachel had receipts for those too.
Most of the “renovations” had been paid with my credit card.
The monthly payments he called mortgage payments were the exact amount listed as rent in emails he had sent me himself.
At his deposition, Rachel placed one of those emails in front of him.
It read:
Rent will be three days late this month. Sorry, Mom.
“Did you write that?” she asked.
“Yes.”
“Why did you call the payment rent?”
“That was just how we talked.”
“Was the deed in your name?”
“No.”
“Was the mortgage in your name?”
“No.”
“Did you provide the down payment?”
He paused.
His lawyer leaned toward him.
Rachel waited.
Finally Ethan said, “I contributed money.”
“From what account?”
Another pause.
It lasted long enough for everyone in the room to understand what was happening.
The civil case was eventually dismissed with prejudice.
But by then, the civil case had become the least of Ethan’s problems.
The bank concluded that multiple transfers from my savings had been unauthorized. Investigators connected login records and verification changes to devices and phone numbers Ethan had used. The forged ownership documents were turned over as part of the criminal investigation.
I did not control what happened next.
That mattered to me.
For years, Ethan had accused me of controlling his life whenever I refused to rescue him from a consequence. This time, I did not have the power to erase the consequence even if I had wanted to.
He was charged with multiple offenses related to theft, identity fraud, and forgery.
The legal fight lasted longer than our family expected.
His lawyer challenged the financial evidence. Brooke hired separate counsel and gave a formal statement. Daniel and Melissa gave statements about Thanksgiving. My photographs became evidence.
Ethan’s employer, a regional automotive group where he managed service operations, placed him on leave after the charges became public.
A month later, he no longer worked there.
Brooke moved out before Christmas.
She filed for divorce in January.
The investor who bought Hawthorne Avenue did not throw Ethan’s belongings onto the sidewalk, as family gossip later claimed. He followed the legal process. Ethan received written notices and had time to leave.
He refused at first.
Then, one cold morning in February, I drove past the house and saw a rental truck in the driveway.
Ethan was carrying boxes out alone.
I did not stop.
The strangest part was that selling the house had never been part of some elaborate revenge plan.
I had not known about the forged documents.
I had not known about the hidden LLC.
I had not known money was disappearing from my savings.
I sold the house because my son hit me twenty times in front of my family and then told me I would have nothing without him.
The sale simply pulled one loose thread.
Everything else unraveled behind it.
The $186,430 remained frozen for months while the civil dispute was active. Eventually, after the ownership claim failed, the proceeds were released to me. I used part of the money to pay legal expenses and kept the rest untouched while the bank investigation continued.
Some of the stolen money was recovered through the bank’s fraud process.
Some was not.
Rachel warned me early that financial recovery and criminal accountability were separate things, and that neither would restore the years I had spent trusting Ethan with access he should never have had.
The criminal case ended in a negotiated plea.
Ethan avoided the maximum sentence, but he did not avoid consequences. He was ordered to pay restitution, received a period of incarceration followed by supervision, and was prohibited from contacting me except through attorneys while the case remained active.
By then, his marriage was over.
His job was gone.
The Hawthorne house belonged to someone else.
His lawsuit had failed.
The money he claimed to have invested had been exposed as money taken from me.
And most of the relatives who once accepted his version of every disaster stopped answering his calls.
Claire visited me one Sunday after everything was settled.
She brought coffee and sat at my kitchen table where Ethan had once helped me set up online banking.
“Do you hate him?” she asked.
I looked through the window at the backyard.
“No.”
“Do you forgive him?”
“I don’t know what that word would change.”
Claire nodded.
We sat quietly.
There was no dramatic victory in the room. No music. No feeling that a perfect balance had been restored.
There was only paperwork in a locked drawer, a new bank account Ethan had never seen, and an empty chair at holidays.
Almost a year after Thanksgiving, I received a letter from him.
His handwriting was familiar enough that I knew who sent it before I saw the return address.
I left it unopened for three days.
When I finally read it, the first page was full of explanations.
Stress.
Alcohol.
Debt.
Fear.
Brooke.
His lawyer.
Me.
Near the bottom of the second page, he wrote:
I lost everything because you sold that house.
I read the sentence twice.
Then I placed the letter on the table.
That was still the story he needed to believe: one decision by his mother had destroyed his life.
But the house had not forged my signature.
The house had not moved money from my savings.
The house had not filed a lawsuit built on documents that did not exist until he created them.
And the house had not raised a hand twenty times in front of twelve people.
Selling it did not create what happened afterward.
It revealed it.
I never wrote Ethan back.
Months later, I drove down Hawthorne Avenue again. The investor had renovated the place and sold it to a young couple. There were two bicycles by the porch and a small pumpkin beside the front steps.
For the first time, the house did not look like Ethan’s house.
It did not look like mine either.
It was simply a house.
That surprised me more than anything.
For years, I had treated that property as proof that I could keep my son safe if I just gave enough, signed enough, paid enough, and forgave enough.
In the end, it became evidence of something much simpler.
A deed can say who owns a building.
It cannot tell you what happened inside a family.
And it cannot keep a secret forever.