On Christmas Eve, Dad pushed a fifty-page contract across the dinner table. We just want you to be somebody, he announced. My sister offered me $70,000 a year to become her assistant. Everyone laughed at my supposed poverty. Then I reached page forty-two, saw my father’s signature on a $1.3 million loan guarantee, and watched my sister turn pale.
My name is Caroline Hayes. I’m thirty-six, living in Boston, where I work as a senior portfolio manager for an investment firm overseeing more than $2 billion in institutional assets. My family believes I process paperwork at a small financial office. I’ve never bothered correcting them.
My younger sister, Madison, owns a luxury interior design company in Connecticut. Dad has always considered her our family’s greatest achievement. She drives a Porsche, wears designer clothes, and frequently reminds everyone that I still rent an apartment instead of owning a mansion.
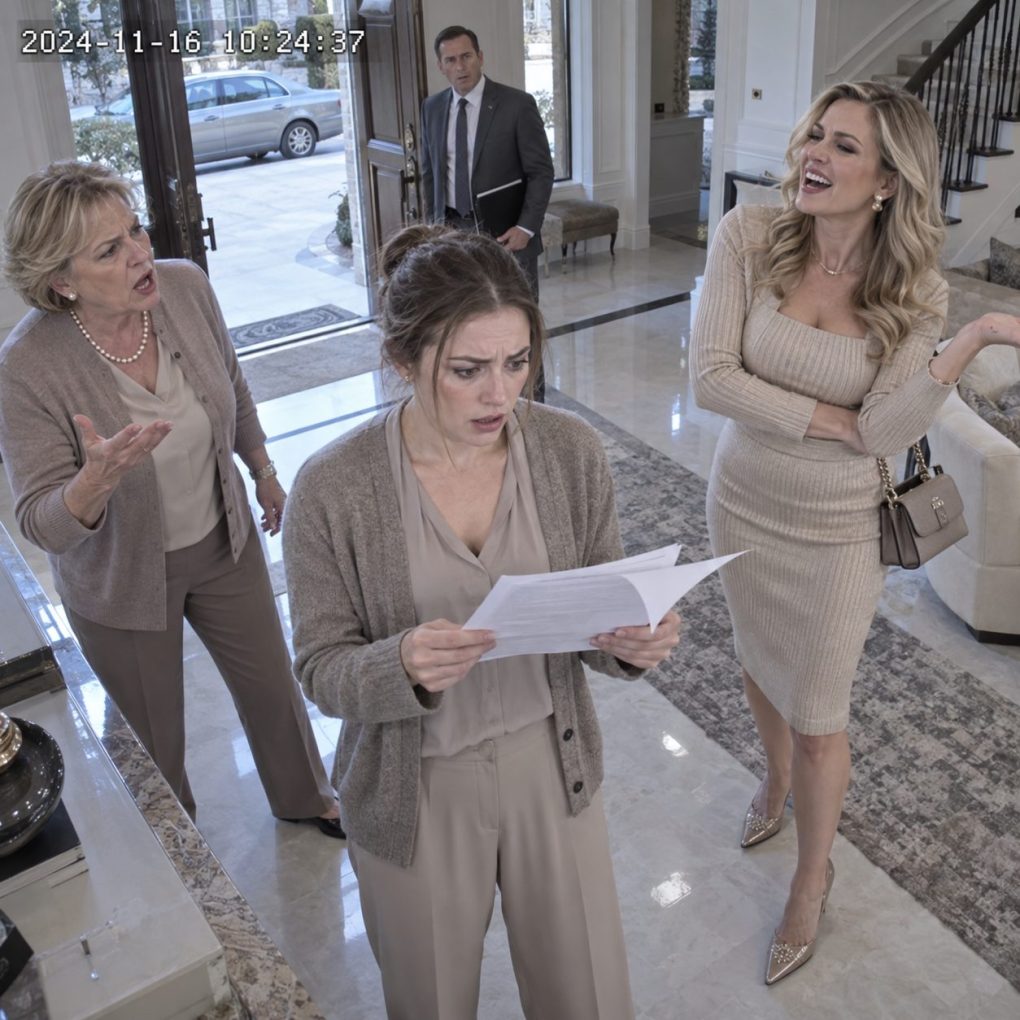
That evening, twelve relatives gathered around my parents’ Christmas table. Madison announced she’d created a position specifically for me. An executive assistant, she explained, would organize her calendar, coordinate vendors, and handle personal errands. Dad smiled proudly, as though she’d offered me the presidency.
Seventy thousand dollars is more money than you’ve ever seen, Mom added. My uncle laughed. Madison leaned closer, explaining that I’d finally be able to stop pretending my boring office job was a career. I smiled politely and opened the contract.
The first forty pages contained ordinary employment provisions: salary, benefits, confidentiality, termination, and workplace responsibilities. Then I noticed a separate document buried among the onboarding forms. Its heading identified a commercial lending agreement involving Madison’s company and a private finance firm.
Page forty-two named three proposed guarantors: Madison, my father, and me. The loan amount was $1.3 million. More disturbing, the document listed my parents’ Connecticut home as proposed collateral. Dad’s signature already appeared beside an acknowledgment he insisted he’d never seen.
I looked across the table. Madison had stopped eating. I asked Dad whether he’d agreed to pledge his house against her business debt. His fork froze halfway to his mouth. Madison reached across the table, demanding the packet back.
I pulled it away. The signature looked suspiciously like the one Dad had placed on Madison’s birthday card earlier that evening. I turned to the next page. It contained a blank space for my signature beneath the words Personal Guarantor.
Dad demanded an explanation. Madison stood so quickly her chair toppled backward. Suddenly, the $70,000 job offer made sense. She hadn’t invited me home to help my career. She had disguised a financial guarantee inside an employment packet, and she desperately needed my signature.
The Christmas table erupted into shouting. Madison insisted the paperwork was merely a standard employment requirement. I asked why an executive assistant would personally guarantee a seven-figure business loan. She answered that I didn’t understand corporate financing. I almost laughed.
Dad took the contract from me. He stared at the signature bearing his name, then at the paragraph describing his house. My mother demanded Madison explain herself. For the first time that evening, nobody seemed interested in discussing my supposed financial failures.
Madison finally admitted that her company was struggling. Two major commercial clients had canceled their contracts, leaving her responsible for expensive imported materials and outstanding supplier invoices. Her bank had declined additional financing, so she’d approached a private commercial lender.
She claimed she’d only borrowed $85,000 from Dad six months earlier. He confirmed giving her that money, believing it would fund a profitable renovation project. He hadn’t agreed to pledge his house, and he certainly hadn’t knowingly signed a $1.3 million guarantee.
I examined the remaining documents. The lender had requested additional financial verification before releasing any funds. Madison had apparently prepared the packet herself, hoping to collect my signature and submit it with the guarantee paperwork. Whether any lender would have accepted it was another question.
I asked where she’d obtained my Social Security number. Madison glanced at Mom. Years earlier, I’d given my parents copies of financial documents during an apartment application. Mom admitted Madison had requested an old file, supposedly to prepare my employment benefits.
My anger rose. I explained that using someone’s personal information to pursue credit without authorization could have serious legal consequences. Dad looked devastated. Madison responded by accusing me of exaggerating, then demanded to know what made me qualified to judge business paperwork.
I opened my professional profile on my phone and handed it to him. My official position, investment management credentials, and responsibility for institutional portfolios were clearly listed. Dad read silently before asking whether the $2 billion figure was real.
I explained that I managed investment portfolios totaling approximately $2 billion for pension funds and other institutions. That money belonged to clients, not me. My responsibilities included evaluating financial risk, examining investment documents, and recognizing irregularities in complex transactions. Madison lowered herself into her chair.
Dad finally understood how badly he’d underestimated me. But I wasn’t interested in celebrating. I photographed the relevant documents, asked him to preserve the originals, and suggested he contact an independent attorney immediately. Then I looked at Madison. She hadn’t merely insulted me. She’d risked our parents’ home.
The following morning, Dad and I met with an attorney who specialized in commercial lending disputes. He reviewed the documents and immediately contacted the finance company. Its representative confirmed that no money had been released and agreed to suspend consideration of Madison’s application while the disputed signatures were investigated.
Dad provided a sworn statement denying that he’d authorized the guarantee or offered his home as collateral. I documented my refusal to participate and secured my credit reports. The attorney emphasized that suspicious documents didn’t automatically create a valid debt, but we needed to resolve the matter before further damage occurred.
Madison called repeatedly. First she begged me to convince Dad not to involve authorities. Then she claimed she’d planned to explain everything after Christmas. I asked why she’d hidden a personal guarantee on page forty-two of an assistant’s employment packet. She had no convincing answer.
Within two weeks, the lender’s review uncovered additional discrepancies in Madison’s application. Several projected contracts had been represented as confirmed revenue, although the customers hadn’t signed final agreements. The lender rejected the financing request and referred the questionable documents for further investigation.
Dad hired an accountant to examine his own finances. The $85,000 he’d advanced Madison was documented as a personal loan, but she had missed every agreed repayment. He finally accepted that continuing to finance her lifestyle was placing his retirement at risk.
Madison sold her Porsche, canceled the lease on her expensive showroom, and began negotiating with creditors. Her business eventually closed after she couldn’t secure enough new work to cover its obligations. The investigation into the disputed paperwork continued separately. There was no instant arrest or dramatic courtroom victory.
Mom called me several weeks later. She apologized for laughing at my career and admitted she’d measured success by houses, cars, and appearances. I told her the insults had hurt, but giving Madison access to my personal documents had damaged my trust far more deeply.
Dad’s apology came in person. He drove to Boston and visited my office, where he saw my team preparing an investment presentation. Afterward, he admitted he’d never bothered asking what I actually did. He’d assumed Madison’s expensive lifestyle meant she was successful and my modest one meant I was failing.
I told him I didn’t need admiration for managing billions. I needed the same basic respect he’d always given my sister. He understood. We began rebuilding our relationship, although I kept my financial information private and declined further involvement in Madison’s business affairs.
The next Christmas, Dad invited me home without offering a job or criticizing my apartment. We had a quiet dinner with no contracts on the table. Madison wasn’t ready to face me, and I accepted that. I remembered how confidently everyone had laughed when they thought I was poor. Page forty-two hadn’t made me successful. It had simply revealed how little my family knew about me, and how dangerous their assumptions had become.