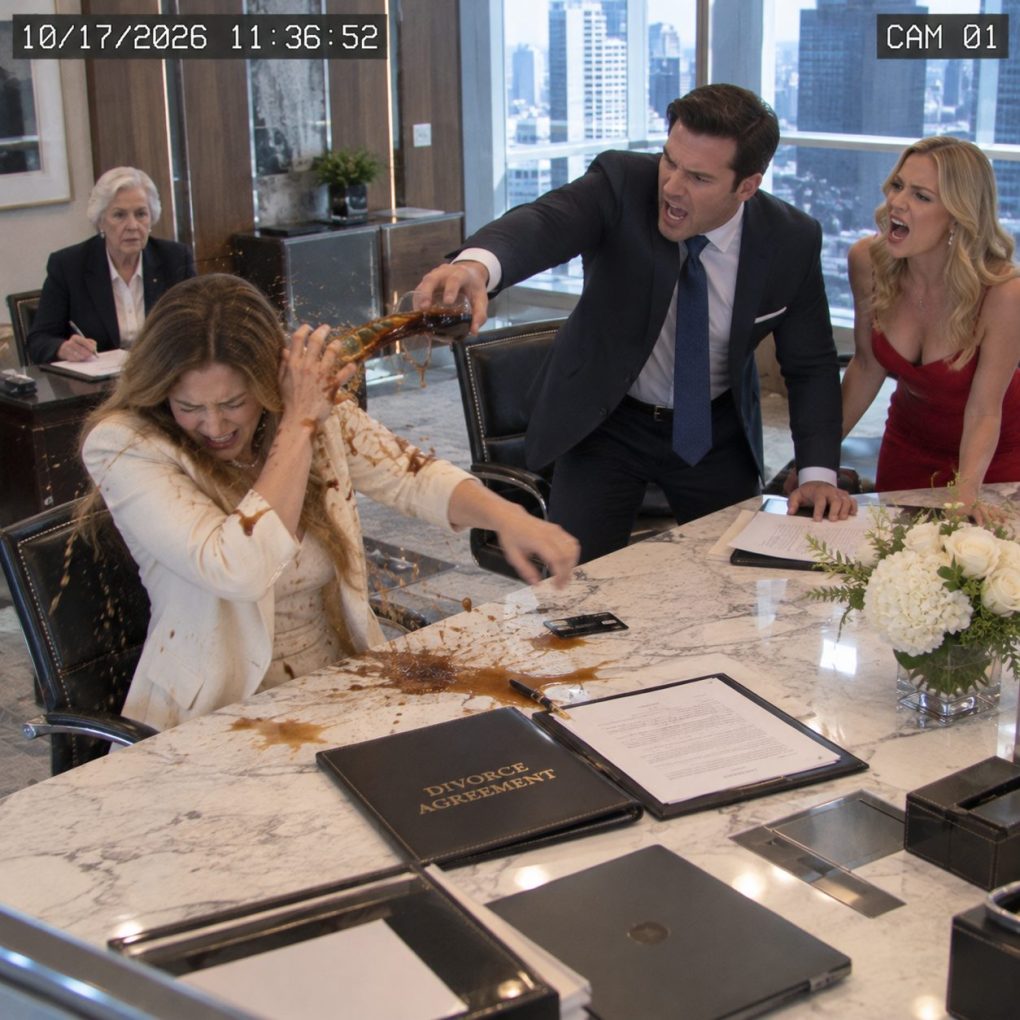
The black card landed beside the divorce papers like a tip left after an expensive dinner.
“Keep it for six months,” Graham said. “It should make the transition easier.”
Across the conference table, Vanessa Cole lowered her eyes to hide a smile. She had been Graham’s chief strategy officer for three years and his mistress for at least eight months. By noon, the two of them were scheduled to stand before investors and unveil the largest acquisition in Mercer Dynamics’ history. By eight that morning, Graham apparently wanted one smaller transaction completed first: ending our seventeen-year marriage.
I picked up the pen.
Graham mistook my silence for shock.
“Evelyn, we both knew this was over.”
No. He knew he wanted it over. I had discovered Vanessa two weeks earlier after a hotel charge appeared on a corporate travel statement sent accidentally to my home office. I had not confronted him. I called my attorney, reviewed our prenup, and requested every corporate document I had signed during the first ten years of our marriage.
There were many.
When Graham joined my late father’s manufacturing company seventeen years earlier, he was a brilliant operations executive with almost no capital. Dad liked him. I loved him. Over time Graham became CEO, renamed the company Mercer Dynamics, and began speaking about it publicly as though he had built it from nothing.
I never corrected him.
My family trust still owned the largest block of shares.
And fourteen years earlier, when Graham needed additional voting power to secure financing for an expansion, I transferred part of my personal founder stake to him under a Stock Transfer and Repurchase Agreement drafted by Dad’s attorney, Arthur Keene.
Graham apparently remembered the transfer.
He had forgotten the repurchase clause.
I signed the divorce settlement only after my attorney confirmed that the financial schedules, property terms, and disclosures matched what we had negotiated. The black card remained untouched.
Graham leaned back.
“There. Done.”
Vanessa finally smiled openly.
At the end of the table sat Arthur Keene, now eighty-one, silver-haired and mostly retired. Graham had invited him because Arthur remained a commissioned notary and had witnessed several old family documents. Graham probably thought his presence made the morning look dignified.
Arthur closed the divorce folder.
Then he opened a second one.
“Before everyone leaves,” he said, “there is a related corporate matter.”
Graham checked his watch. “Arthur, I have a presentation in three hours.”
“I’m aware.”
Arthur removed a yellowed agreement bearing Graham’s signature, mine, and my father’s.
Then he looked at me.
“Mrs. Bennett, would you like me to explain which shares now return to you?”
Vanessa stopped smiling.
Graham stared at the document.
“What shares?”
Arthur adjusted his glasses.
“The 12.5 percent founder block Evelyn transferred to you in 2012. Section Eleven grants her an immediate repurchase option upon final marital dissolution.”
Graham reached for the agreement.
Arthur did not hand it over.
“The repurchase price is the original transfer price plus the contractual adjustment.”
Graham’s face went pale.
Because those shares were not merely valuable.
They were the shares he had counted on to prove voting control during the acquisition presentation scheduled for noon.
And without them—
he no longer controlled the company.
Graham’s first reaction was disbelief. His second was anger. He insisted the clause could not possibly apply because the shares had been in his name for fourteen years. Arthur calmly explained that legal title and contractual restrictions can coexist; the old agreement had always subjected the block to my repurchase option under specified events.
The divorce itself did not magically transfer anything that morning. My attorney, Rebecca Sloan, still had to exercise the option formally, deliver notice, and follow the valuation formula written into the agreement. But Graham’s voting rights over those restricted shares were suspended once the triggering event occurred and proper notice was served.
That mattered immediately because Mercer Dynamics was hours away from announcing its acquisition of Halcyon Robotics. Graham had represented to Halcyon’s board that he controlled enough voting power to secure shareholder approval for several deal-related resolutions.
Before the divorce, that assumption was barely true. With the restricted founder block removed from his control, it was not. The acquisition was not automatically dead, but the presentation could no longer describe shareholder approval as effectively guaranteed.
Vanessa demanded to know why nobody had disclosed the clause earlier. Rebecca answered that the agreement had been included in Mercer Dynamics’ historical shareholder records for years. Graham had personally signed it, and the company’s outside counsel had referenced it during two prior financing rounds.
Arthur then produced another document: a memorandum he had sent Graham five years earlier reminding him that divorce, death, or certain unauthorized transfers would trigger restrictions on the founder block. Graham’s assistant had acknowledged receipt.
Graham looked at Vanessa instead of me. “This changes nothing. We still have institutional support.” That might have been true, except Rebecca had spent the previous week speaking with the independent trustee controlling another 16 percent of the company.
The trustee had not promised to oppose Graham. It had simply refused to commit its votes before reviewing Halcyon’s final acquisition terms. Graham had been telling investors those votes were “aligned with management” anyway.
By 9:30, Mercer’s general counsel joined the conference room. He read the repurchase agreement, called outside securities counsel, and immediately postponed any statement suggesting Graham had secured voting control. The noon presentation could proceed, but the governance slide had to change.
Then the financial schedules created a second problem. During divorce discovery, Graham disclosed personal loans totaling approximately $3.8 million. Several were secured by assets he described as “Mercer Dynamics founder shares.”
He had apparently pledged part of the restricted block as collateral.
The agreement prohibited that without written consent from me and the company.
I had given none.
The lenders had possession of security agreements, but whether those agreements attached validly to restricted shares required separate legal review. Nobody shouted fraud. Nobody declared the loans void in ten minutes. Lawyers simply began asking questions Graham had clearly hoped no one would ask before the acquisition closed.
Vanessa finally turned to him.
“You told me the shares were yours.”
Graham snapped, “They are.”
Arthur corrected him gently.
“Some are. These are not that simple.”
Then Rebecca opened the cap table.
Even after the repurchase, Graham still owned a substantial personal stake—just under nine percent. I was not taking the company from him. I was recovering the specific founder block my father had transferred under written conditions.
But once that block returned, my trust and personal holdings together would represent approximately 31 percent of Mercer Dynamics.
Enough to make me the company’s largest beneficial shareholder.
Vanessa stared at the page.
Then at me.
For seventeen years, she had known me only as Graham’s quiet wife.
She had no idea the woman she watched sign divorce papers that morning had been sitting beside the largest ownership position in the room.
Mercer Dynamics did not collapse before lunch. Companies do not disappear because one executive miscalculates a cap table. The acquisition presentation went forward at 1:00 p.m., delayed by an hour while lawyers revised the governance disclosures and removed claims that were no longer supportable.
I did not attend.
I went home, placed Graham’s black card inside an envelope, and returned it through Rebecca’s office. I had my own accounts, my own trust distributions, and no interest in carrying a symbol designed to make me feel dependent.
The repurchase process took almost three months. Independent counsel reviewed the 2012 agreement, confirmed the triggering event, calculated the contractual price, and resolved objections raised by one lender that had accepted Graham’s restricted shares as proposed collateral.
Ultimately, the founder block returned under the agreement. Graham retained every unrestricted share that genuinely belonged to him. No judge handed me his career because he cheated on me. The contract simply enforced a business arrangement he had signed long before Vanessa entered our marriage.
The Halcyon acquisition survived too, but under different terms. The board created a special committee, institutional shareholders demanded additional diligence, and the final transaction required broader shareholder approval than Graham originally expected.
My trust supported the revised deal.
That surprised him.
He called Rebecca and asked why I would vote for something that might strengthen him as CEO. My answer was simple: I was not interested in damaging a company that employed thousands of people merely because my marriage had failed.
Graham’s position weakened for reasons entirely separate from our divorce. The board became concerned that he had overstated voting certainty, failed to disclose restrictions on pledged shares to certain lenders, and allowed his personal situation to intersect too closely with corporate planning.
He remained CEO during the investigation.
Six months later, he stepped down by agreement with the board and stayed on temporarily as an adviser during the leadership transition. Vanessa resigned several weeks before that. I never learned whether their relationship survived once it no longer existed inside executive suites and hotel rooms.
My divorce settlement became final without additional drama. I kept my separate property and the assets assigned to me under the agreement. Graham kept his legitimate holdings, several properties, and more money than most people earn in several lifetimes.
He was not ruined.
He simply stopped controlling things he had convinced himself were permanently his.
Arthur retired fully the following year. At our last lunch, I asked whether my father had included the repurchase clause because he distrusted Graham.
Arthur smiled.
“No. Your father actually liked him very much.”
“Then why write it?”
“Because your father understood that affection is not a substitute for governance.”
That stayed with me.
For seventeen years, I had confused silence with support. I let Graham become the public face of a business my family had spent decades building because I believed marriage meant we were moving toward the same future.
When that stopped being true, I did not need to humiliate him.
I needed the paperwork to remain true.
The image I remember most is still that conference room.
Vanessa watching.
Graham sliding a black card toward me like severance pay.
Me signing without begging him to reconsider.
And Arthur opening the second folder.
Graham thought the divorce papers were the document ending my position in his life.
He had forgotten they were also the document activating an agreement that clarified my position in the company.
The shares did not return because he had an affair.
They returned because years earlier, three people had been wise enough to put ownership, conditions, and consequences in writing.
Love had changed.
The records had not.
And by the time Graham walked into the biggest presentation of his career, he finally understood the difference.