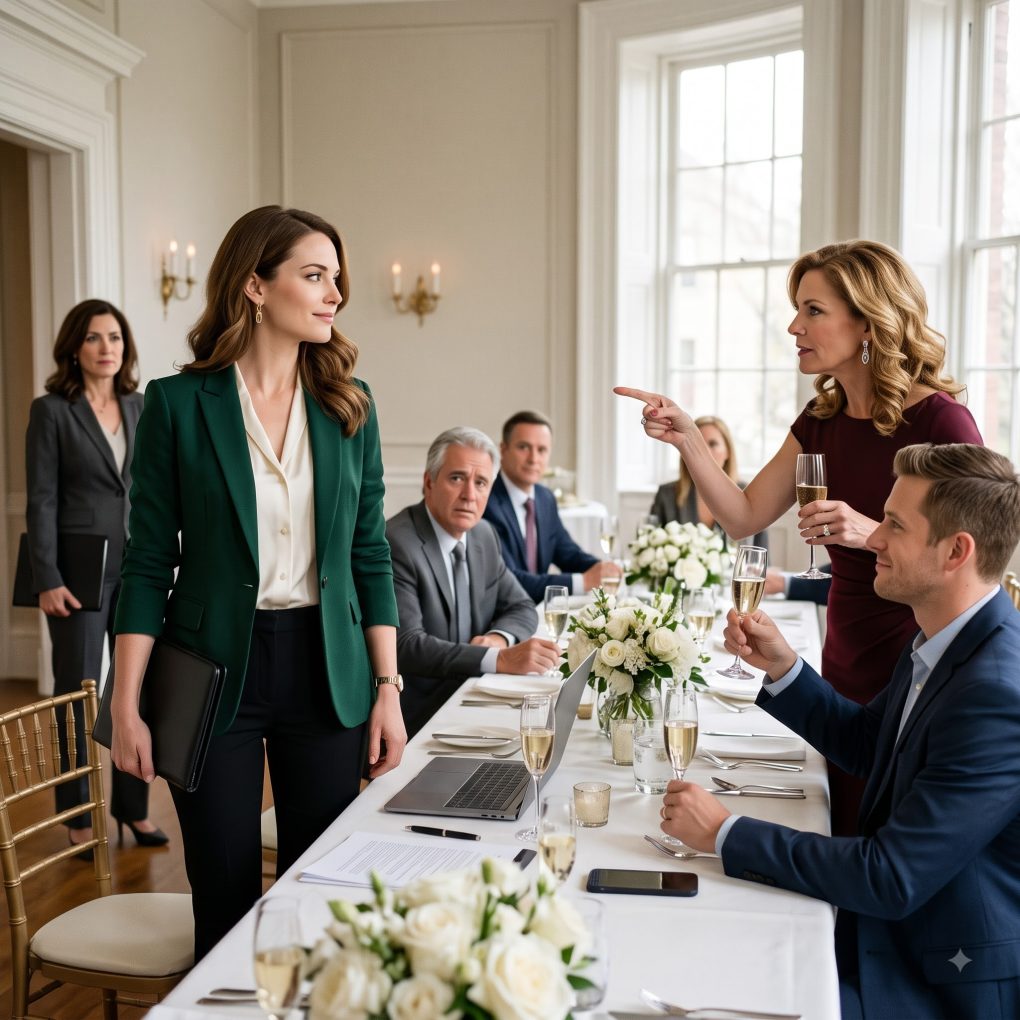
The night I secured a $10 million investment for my family’s business, my mother raised her champagne glass, pointed directly at me, and announced that my younger brother would become the next CEO.
“Your job is done, Claire. You turned our little shop into a brand. Now let your brother take over.”
Thirty relatives and employees sat around the banquet hall, applauding as if she had just promoted a deserving executive. My brother, Tyler, leaned back in his chair with a satisfied grin. He had spent most of the previous five years avoiding responsibility, yet somehow, he was being rewarded for the decade I had sacrificed building our family business.
I simply smiled and said nothing.
By Monday morning, the $10 million investment was canceled. When my family discovered why, their celebration turned into a nightmare.
My name is Claire Harper. I was thirty-four, and for ten years, I had transformed Harper House Foods, my parents’ struggling neighborhood specialty-food shop in Columbus, Ohio, into a regional brand stocked by grocery stores across seven states.
When I started, we had four employees, an outdated kitchen, and barely enough money to cover rent. I redesigned our packaging, negotiated with suppliers, built an online store, secured distribution agreements, and worked weekends developing recipes that eventually became our best-selling products.
I also persuaded our local bank to extend credit when our cash flow nearly collapsed. During our worst year, I went three months without taking a salary because I refused to let our employees go unpaid.
My father called me the backbone of the business. My mother called me whenever something went wrong. But whenever a reporter visited or a distributor offered congratulations, she introduced Tyler as the family’s future leader.
Tyler was thirty, charming, and excellent at making promises. He had worked in the business intermittently, but he had never managed a production schedule, negotiated a major contract, or been responsible for payroll.
The $10 million investment had taken fourteen months to secure. Vivian Ross, a managing partner at Northbridge Capital, had studied our financial statements, inspected our production facility, interviewed employees, and examined my expansion plan. Her proposed investment included a specific condition: I had to remain CEO for at least three years because the company’s growth strategy depended on my leadership.
The agreement had not closed yet, but the investment committee had approved the terms.
My parents knew how important that condition was.
At the celebration, however, my mother announced Tyler’s promotion as though the decision had already been made. My father stared at his plate. Tyler lifted his glass toward me.
“Don’t worry, Claire,” he said. “I’ll take it from here.”
I looked at the people who had helped me build the company, then at the family members who believed my work belonged to them simply because we shared a last name.
I didn’t argue. I didn’t threaten anyone.
I quietly placed my champagne glass on the table and went home.
On Sunday evening, Tyler posted an announcement celebrating his upcoming appointment as CEO.
By Monday morning, Vivian Ross had seen it.
And her first call was not to Tyler.
At 8:12 on Monday morning, my phone rang while I was sitting at my kitchen counter reviewing the next quarter’s production schedule.
Vivian Ross’s name appeared on the screen.
“Claire, I need to ask you something directly,” she said after greeting me. “Has the company formally appointed Tyler as CEO?”
I took a breath.
“My mother announced it at a family celebration on Saturday. Tyler posted about it last night. I haven’t received any formal notice that my position has changed.”
There was a brief silence.
“Does your board know that Northbridge’s investment committee approved this transaction on the condition that you remain CEO?”
“They know the proposed terms. I don’t know whether my parents intend to challenge them.”
“Then I need to speak to the board before our closing process goes any further.”
Her voice was measured, not angry. That made the situation feel more serious.
Northbridge had not transferred the $10 million. The company had signed a conditional investment agreement, and the closing process still required final legal documents, updated corporate approvals, and confirmation that the agreed governance terms remained intact.
One of those terms was my continued leadership.
Vivian explained that Northbridge had evaluated Harper House Foods as a business built around a proven operating strategy. The investment was meant to expand production, improve distribution, and increase capacity. It was not intended to finance an untested leadership change immediately before closing.
“I need you to understand something,” she said. “This isn’t about whether Tyler is a good person. It’s about whether the company we’re investing in is still the company we approved.”
I told her I understood.
After the call, I opened my email and found a message from Tyler.
Mom says you should prepare a handover document by Friday. I’ll need all the supplier contacts, financial models, recipes, distribution agreements, and expansion plans. Don’t make this difficult.
I read it twice.
For ten years, those files had represented thousands of hours of work. Some belonged to the company, some contained confidential business information, and others documented processes I had personally developed for Harper House Foods. I had no intention of withholding legitimate company records, but I wasn’t going to hand over control informally or pretend that an announced promotion was the same as a properly approved appointment.
I forwarded Tyler’s message to our corporate attorney, Melissa Grant, and asked her to confirm the current governance procedures and the conditions attached to Northbridge’s investment.
Melissa replied that afternoon.
The company’s board had not formally approved Tyler’s appointment. My mother, Denise Harper, held a majority of the family’s shares, but that did not give her unrestricted authority to disregard the company’s bylaws, existing executive agreements, or the approvals required by the investment agreement.
The proposed appointment needed to be addressed through the proper process.
That evening, my mother called.
“Vivian is asking unnecessary questions,” she said. “Tell her everything is fine. Tyler can become CEO, and you can stay on as an adviser.”
“The investment agreement requires me to remain CEO for three years.”
“Those are just negotiating terms. Surely she understands that families need flexibility.”
“Mom, they aren’t just suggestions. Northbridge evaluated the company on those terms.”
My mother sighed loudly.
“You’re making this personal. Tyler deserves his opportunity. You’ve had ten years. Do you expect to control this business forever?”
I looked around my kitchen at the production schedules, market research, and expansion plans spread across the table.
“No,” I replied. “But I expect us to honor the agreement we made.”
She hung up.
On Tuesday, I attended an emergency board meeting with Melissa. My parents and Tyler joined remotely. The board reviewed the proposed CEO change, the conditional investment agreement, and the risks of announcing a leadership transition before obtaining the necessary approvals.
My father, Robert Harper, finally spoke.
“I thought we were celebrating a successful investment. I didn’t realize changing the CEO could jeopardize everything.”
My mother interrupted him.
“It’s our company. We should be allowed to decide who runs it.”
Melissa calmly explained that the family’s ownership gave them important rights, but those rights had to be exercised according to the company’s governing documents and its commitments to investors. The investment agreement included a requirement for Claire to continue as CEO through the initial expansion period unless Northbridge approved a change in writing.
Tyler looked annoyed.
“So everyone expects me to sit around waiting for Claire to retire?”
“Nobody said that,” I replied. “But you cannot become CEO simply because Mom announced it at dinner.”
He leaned toward his camera.
“You’ve always wanted to keep me beneath you.”
I didn’t respond. It would have been easy to argue about the years he had spent avoiding responsibility, but that wasn’t the issue the board needed to resolve.
The meeting ended without an appointment. The board agreed to review the investment agreement with counsel and notify Northbridge of the proposed change.
By Wednesday, the tension had spread through the company. Employees asked whether their departments would be reorganized. Our operations manager worried that the new production facility would be delayed. Two suppliers contacted me because they had seen Tyler’s announcement and wanted to know who would be approving future contracts.
I reassured them that no formal transition had been approved and that company operations would continue as normal.
Then Vivian sent a written notice to the board requesting confirmation of the leadership arrangement before the investment could proceed.
My mother called me again that evening.
“Fix this, Claire. You’ve spent ten years building this company. Don’t destroy it now because you can’t share power.”
“I didn’t announce a change that violates the investment terms,” I said. “I’m not the person who needs to fix this.”
She ended the call.
By Friday, Northbridge had suspended final closing preparations pending clarification. My parents still believed they could persuade Vivian to accept Tyler as CEO after the fact. Tyler even began drafting a new executive announcement.
I knew they had underestimated the situation, but I didn’t know whether the company would survive the fallout without losing the investment.
On Monday morning, Vivian scheduled a final meeting with the board.
She arrived with Northbridge’s counsel and a written decision from the investment committee.
The first sentence read:
“Northbridge Capital hereby withdraws its proposed $10 million investment due to the company’s failure to maintain the agreed executive leadership and governance conditions.”
My father’s face went pale.
My mother dropped the paper onto the conference table.
Tyler stared at me.
“You did this,” he said.
I shook my head.
“No. You announced a new CEO before the deal closed. Now we have to deal with the consequences.”
But the canceled investment was only the beginning of what the family had to confront.
For several seconds, nobody spoke.
The $10 million withdrawal notice lay in the center of the conference table. My mother stared at it as though the words might rearrange themselves into something less damaging. My father sat motionless, both hands wrapped around a paper coffee cup. Tyler kept looking from the notice to me, waiting for me to admit that I had somehow orchestrated the entire situation.
Vivian Ross broke the silence.
“Northbridge did not withdraw because of a family disagreement,” she explained. “We withdrew because the leadership arrangement presented to us during negotiations is no longer the arrangement the company intends to maintain. The investment committee cannot approve financing based on one set of conditions while the company publicly announces another.”
My mother shook her head.
“Claire could have reassured you that she would cooperate. She’s our daughter. She would never let the company fail.”
Vivian remained composed.
“Our investment was approved because Claire demonstrated that she could lead the proposed expansion. We were clear about that requirement before the agreement was signed. When the company announced a different CEO without obtaining our written approval, we had to reassess the transaction.”
“Then change the terms,” Tyler snapped. “I’m perfectly capable of running this business.”
“You were invited to submit your qualifications during the due-diligence process,” Vivian replied. “The committee considered the management experience presented at that time. Your appointment was not part of the approved transaction, and we have not received evidence that the conditions for changing leadership have been satisfied.”
Tyler’s face turned red.
My mother pushed the notice away.
“We can find another investor.”
It was a confident declaration, but nobody echoed it.
The company needed more than a check. We needed capital to expand our production facility, purchase equipment, improve distribution, and hire additional staff. Northbridge had agreed to provide the entire funding package because it believed the financial plan and leadership structure would work together.
Finding another investor was possible, but it would require a new search, another due-diligence process, and a fresh negotiation. There was no guarantee that another firm would offer the same terms.
I looked at my father.
“Dad, the company can still recover. But we need to stop making decisions based on what we think we deserve and start looking at what the business actually needs.”
He finally met my eyes.
“What do you suggest?”
I opened my notebook.
“First, we formally withdraw the announcement naming Tyler as CEO because the board hasn’t approved it. Second, we communicate with employees and suppliers so they understand that the management structure remains unchanged until the proper process is completed. Third, we review the expansion budget and determine how long we can operate without the investment. Then we decide whether to approach Northbridge again or seek alternative financing.”
My mother stared at me.
“You expect us to apologize to an investor because we wanted your brother to have an opportunity?”
“No. I expect us to be honest about the agreement we signed.”
Vivian listened without interrupting. When I finished, she closed her folder.
“Northbridge’s decision is final for this transaction,” she said. “We will not reopen the proposed investment simply because the company changes its announcement. If Harper House Foods wants to seek financing in the future, it will need a credible business plan, a stable leadership structure, and appropriate governance.”
She stood, thanked the board, and left with her counsel.
The meeting continued for another hour.
My mother accused me of embarrassing the family. Tyler claimed that I had deliberately made him look unqualified. My father tried to defend both of them, but eventually admitted that the announcement had been made without considering the investment conditions.
I let them argue until they ran out of accusations.
Then I said something I had wanted to say for years.
“I love this family, but I will not pretend that ten years of work can be transferred to Tyler simply because you have decided it’s his turn. The company needs a qualified leader, clear authority, and honest agreements. If you want Tyler to become CEO someday, he can earn that opportunity through experience and a proper board process. But I won’t be removed to make room for an announcement you made at dinner.”
Tyler stood abruptly.
“You think you’re better than me.”
“No,” I said. “I think the company deserves better than a decision made without a plan.”
He left the meeting. My mother followed him.
My father stayed behind.
For the first time that week, he looked less like the founder of Harper House Foods and more like a tired man who had realized that he might lose the business he had spent his life building.
“I should have stopped your mother,” he admitted.
“Yes,” I replied. “You should have.”
He looked down at the table.
“I thought we could make you CEO for a while, then hand the company to Tyler when the time was right. I never thought he’d announce it before everything was finalized.”
“Dad, you cannot ask me to build a business and then treat my position as temporary whenever Tyler wants something.”
He nodded, but he had no immediate answer.
Over the following two weeks, we focused on stabilizing the company. I prepared a revised operating budget that removed the expansion expenses we could no longer afford. We postponed the purchase of additional production equipment, negotiated more manageable terms with two suppliers, and delayed hiring for positions that were not essential to current operations.
The decisions were difficult. The $10 million would have allowed us to expand faster and take advantage of several new distribution opportunities. Without it, we had to protect our cash reserves and prioritize the products that generated the most reliable profit.
Our operations team helped identify waste in the production process. We reduced packaging costs without lowering product quality, renegotiated shipping rates, and consolidated several overlapping marketing contracts. None of those measures could replace the investment, but together they bought us time.
I also met individually with department leaders to explain what had happened. I did not blame my family or disclose private details unnecessarily. I told employees that the financing had fallen through because the company had failed to maintain the leadership conditions agreed during negotiations, and that we were revising the business plan accordingly.
Some were disappointed. A few had expected promotions or new positions linked to the expansion. I promised them only what I could reasonably deliver.
Meanwhile, my mother continued looking for other investors. She contacted two regional investment firms and a private lender who had previously expressed interest in food manufacturing. Both requested financial statements and an explanation of the failed Northbridge transaction.
One lender declined after reviewing our revised cash-flow projections. The other expressed interest but offered significantly less funding at a higher cost. My mother finally began to understand that losing Northbridge had not merely delayed the money. It had weakened our negotiating position.
Tyler, meanwhile, asked me to train him for the CEO role.
His request arrived in an email that was shorter and more formal than his usual messages.
I understand you don’t want me to take over immediately. I want to learn the operations properly. Can we meet to discuss a development plan?
I didn’t mistake the email for a complete change of character, but I agreed to meet him.
We sat in the company’s small conference room on a Wednesday afternoon. I brought our production calendar, supplier agreements, financial reports, and customer retention figures.
“If you want to lead this business,” I told him, “you need to understand how it works when nobody is watching. You need to know our margins, our supply risks, our customer commitments, and how much each decision costs. You can’t begin with the title.”
He listened more carefully than I expected.
I proposed that he begin by managing a specific part of the business under supervision. He would take responsibility for retail distribution, report measurable results to the board, and complete a management development plan. Any future executive appointment would depend on performance, qualifications, and the company’s governance procedures.
He agreed, though I could tell he still disliked the idea of starting below me.
For the first month, he attended supplier meetings and reviewed our distribution costs. He learned that a seemingly small delay could cause missed delivery windows and retailer penalties. He discovered that our sales figures did not tell the whole story because product returns, freight costs, and promotional discounts could eliminate the apparent profit on certain orders.
He made mistakes. I corrected them, and he corrected some of mine. For the first time, our conversations were about the business rather than who deserved to be in charge.
My mother remained difficult.
She continued telling relatives that I had lost a $10 million deal because I refused to share control with my brother. When an aunt repeated that accusation to me, I offered to show her the actual investment conditions.
She declined.
I learned not to waste energy arguing with people who preferred a simple family story over documented facts.
Six months after the Northbridge withdrawal, Harper House Foods was stable but still operating cautiously. We had not found a replacement investor willing to provide $10 million on comparable terms. Our revised strategy focused on profitable growth rather than rapid expansion, and we began exploring a smaller credit facility that could be supported by our existing revenue.
The company also adopted a formal succession policy. Executive appointments would require board approval, documented qualifications, and a clear transition plan. Family members would be held to the same standards as external candidates, and any proposed leadership change would be reviewed for its effect on financing and operations.
My father supported the changes. My mother accepted them reluctantly.
Then, almost a year after the celebration, an opportunity arrived from a different direction.
A national specialty-food distributor approached us about a long-term supply agreement. It would not provide an investment of $10 million, but it could significantly increase our sales if we could meet the required volumes and maintain our margins.
The negotiations lasted four months. I led the financial planning, while Tyler coordinated the distribution assessment and supplier schedules. This time, nobody announced a promotion before the agreement was signed. Every responsibility was documented, and the board reviewed the risks before approving the deal.
The contract was smaller than the Northbridge investment, but it was profitable, practical, and based on what our company could actually deliver.
At the board meeting where the agreement was approved, my father looked at me across the table.
“You saved the business twice,” he said quietly. “Once when you built the brand, and again when we nearly lost control of it.”
I appreciated his words, but I didn’t let them erase the hurt of the previous year.
“I didn’t save it alone,” I replied. “The employees did the work with me. And we can’t build a healthy company if we keep treating business decisions as family rewards.”
My mother finally apologized to me several weeks later. She admitted that she had assumed Tyler deserved the CEO title because he was her son, even though she knew I had done most of the work required to grow Harper House Foods.
Her apology did not repair everything overnight. Trust rebuilt slowly, through actions rather than speeches.
Tyler continued improving in his distribution role. He stopped introducing himself as the future CEO and began presenting measurable results instead. Whether he would eventually lead the company remained an open question, and for the first time, that seemed fair.
I remained CEO, not because I had threatened my parents or forced an investor to punish them, but because the company’s board had reviewed the business requirements and determined that I was the most qualified person for the job at that time.
The $10 million investment never returned. I did not pretend otherwise. We lost an opportunity, and the business had to grow more slowly as a result.
But Harper House Foods survived.
On the second anniversary of the family celebration, we held a small gathering at the original shop where my parents had started with four shelves of specialty products and a handwritten sign in the window. Employees stood beside longtime customers, and my father spoke about how far the company had come.
When my mother raised her glass, she looked directly at me.
“To Claire,” she said. “For building something none of us could have built alone.”
I accepted the toast without pretending that one sentence repaired ten years of being overlooked.
Then I turned toward Tyler, who stood near the end of the table.
“To everyone who earns their place,” I added.
This time, nobody laughed.
I had once believed that if I worked hard enough, my family would eventually recognize my value. I had thought the numbers, the long nights, the sacrifices, and the $10 million investment would finally prove that I deserved to be heard.
What I learned was different.
My value had never depended on my mother’s approval, my brother’s ambition, or an investor’s money. The investment was an opportunity, not a measure of my worth. And losing it did not mean that my ten years of work had been wasted.
My family had tried to turn my success into a handover ceremony for the son they favored. They thought the title could be transferred as easily as a set of keys.
But a company is not a family trophy, and leadership is not a reward for being someone’s favorite child.
The next time I raised a glass at Harper House Foods, I did so as the CEO who had built the brand, the professional who had protected the company’s future, and the woman who had finally learned that silence can be more powerful than an argument—especially when the facts are on your side.