“Your sister gets the mansion. You can leave tonight.”
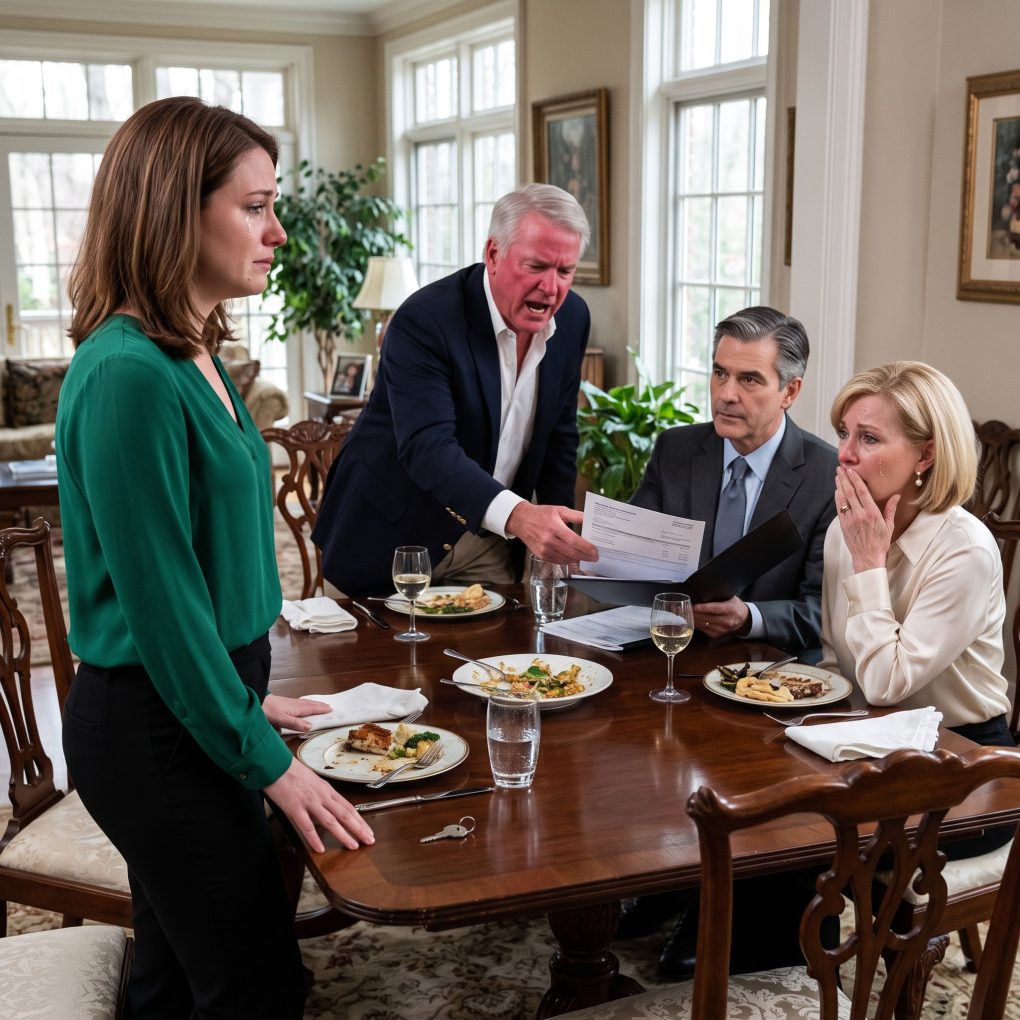
Dad dropped my house key beside my dinner plate.
Across the table, my sister, Brooke, lifted her wineglass. Mom kept cutting her chicken, as though throwing me out between courses was perfectly normal.
I looked at the key. Then at the man sitting beside Dad.
Martin Hale, the banker who had called me that afternoon.
I smiled.
“Did you tell her about the mortgage?”
Mom’s knife stopped. “What mortgage?”
Martin slowly opened his folder.
“The one your daughter has been paying.”
Brooke lowered her glass.
Dad reached for the folder. Martin moved it away.
“We agreed you would explain the financial situation before asking anyone to sign.”
“There’s nothing to explain,” Dad snapped. “Emma helps with expenses. She lives here.”
I had moved back eleven days earlier, after a burst pipe flooded my apartment.
I had been making their mortgage payments for six years.
“Four thousand, two hundred dollars a month isn’t groceries,” I said.
Mom turned toward Dad. “You told me the house was paid off.”
“Linda, let me handle this.”
“You said your aunt’s inheritance cleared everything.”
Martin glanced at me. I nodded. These were the payment records I had authorized him to bring.
He laid one page on the table.
Every withdrawal came from my account.
Mom pulled it closer.
Dad stood so quickly his chair struck the wall.
“This is a family dinner.”
“You invited him,” I said.
Dad had told everyone Martin was coming to help transfer the house to Brooke. Martin had told me something different: a proposed refinance required my approval because my parents owed me money under a recorded loan agreement.
Six years ago, I had rescued their house on one condition. Every payment would be documented and repaid when they sold or refinanced.
Both parents had signed.
Brooke pushed the page away.
“Whatever arrangement you made, Dad promised me this house.”
“Then he promised something he couldn’t afford to give you.”
Her face tightened. “You always have to ruin everything.”
Martin took out a second document.
“I need to establish whether Emma signed this.”
My name appeared beneath a paragraph agreeing to move my claim behind a new lender’s mortgage.
The signature looked almost right.
Almost.
“I didn’t sign that.”
Dad stopped moving.
Martin turned the page toward him.
“Then, Richard, we need to discuss why you submitted it yesterday.”
Mom stared at the signature.
Brooke whispered, “Dad, you said she’d already agreed.”
For the first time that evening, my father looked afraid.
Then Martin opened the last section of his folder.
That was when Dad reached across the table and tried to close it. Until then, I thought the worst thing my family had done was spend my money while planning to throw me out. I hadn’t yet seen what they intended to do next.
Martin kept one hand on the folder.
“Please sit down, Richard.”
Dad remained standing.
“What is in there?” Mom asked.
“A proposed cash-out refinance,” Martin said. “It hasn’t been approved or funded. The application says part of the proceeds would repay Emma.”
“How much?” I asked.
“One hundred and sixty-four thousand, four hundred dollars.”
My chest tightened. That was the balance on the repayment statement I had sent Dad last month.
“But the disbursement instructions send that amount to an account ending in 8821.”
“That isn’t mine.”
Brooke looked down.
I noticed because everyone else was staring at Dad.
“Whose account is it, Brooke?”
She pressed her napkin against her mouth.
Dad answered. “An account established for the family.”
Martin slid the instructions toward me.
The recipient was Bennett Home Consulting LLC.
Brooke’s last name was Bennett.
“What consulting?” Mom asked.
“It’s a business,” Brooke said.
“What business?”
“Jason handles the paperwork.”
Jason was her fiancé. He sold investment opportunities from his phone and had once asked whether I could “temporarily access” my retirement savings.
I turned to Martin. “If this went through, the bank would think I’d been repaid?”
“The closing documents would need to reflect the actual transaction,” he said. “That discrepancy is one reason I stopped the review.”
“And my signature?”
“Another reason.”
Dad leaned toward me.
“You’re making this sound criminal.”
“I’m asking where my money was supposed to go.”
“It’s not your money until the house sells.”
“It’s money I already earned. You already spent it.”
Mom stood and walked to the kitchen counter. Her purse was hanging from a chair. She took out her phone.
“Richard, show me the inheritance deposit.”
He stared at her.
“The money you said paid off the mortgage. Show me.”
“There were complications.”
“Did you receive an inheritance?”
“No,” I said quietly.
He looked at me with such hatred that I almost stepped back.
I knew because his aunt was still alive. She had sent me a birthday card three weeks earlier.
Mom sat down again.
Brooke started crying.
“Jason said this would fix everything.”
“What needs fixing?” I asked.
Dad grabbed her wrist. “Enough.”
She pulled away.
“No. You told me Emma would sign because she always does.”
The room went still.
Brooke looked at me, mascara gathering beneath her eyes.
“The business owes money. Dad guaranteed a loan. Jason said we could clear it after the refinance.”
“How much?”
She looked toward Dad.
“Two hundred and forty thousand.”
Mom made a small, strangled sound.
Martin began gathering his documents.
“I’m stopping this application. I’ll record the disputed signature and account instructions for our review team.”
Dad pointed at me.
“If you do this, your mother loses her home.”
I looked at Mom. For once, she didn’t look away.
Then Brooke’s phone lit up beside her plate.
Jason’s name filled the screen.
Beneath it was a message.
Did she sign? We need the money before Friday.
I reached for my coat.
Dad stepped between me and the doorway.
“You are not leaving until we settle this.”
Behind him, Brooke answered the call.
“Jason,” she whispered, “they know.”
“Move,” I told Dad.
He planted one hand against the doorframe.
For thirty-two years, that would have been enough. His silence, his posture, the certainty that everyone else would eventually surrender.
Martin stood beside me.
“Richard. Let her leave.”
Mom picked up my house key from the table and put it in my hand.
“She isn’t the one who needs to go.”
Dad stared at her.
I left before he could answer. From my car, I emailed copies of everything I already had to an attorney named Rachel Kim.
I had hired her six years earlier to prepare the repayment agreement. Dad had called that insulting, too.
By morning, I was grateful I had disappointed him.
Rachel read Martin’s email, then asked me one question.
“Have you signed any release of your loan?”
“No.”
“Good. Let’s keep the records together and get the full application.”
She contacted the bank with my written authorization. I reported the disputed signature, provided genuine examples, and asked for all further communication in writing.
The loan never closed.
That stopped the immediate danger. It didn’t explain how my family had reached the point of celebrating my eviction over dinner.
Mom brought the answer two days later.
She arrived at Rachel’s office carrying a grocery bag full of bank statements, business letters, and unopened envelopes she had found in Dad’s desk.
“I stopped asking questions because he made me feel stupid for asking,” she said.
Rachel emptied the bag carefully.
The story emerged a page at a time.
There had never been an inheritance. Two years earlier, Dad had told Mom the mortgage was gone and that he had repaid me.
He told me something else: Mom’s medical expenses had exhausted their savings, and discussing the payments would humiliate her.
So I kept paying. Mom kept thanking him for taking care of everything.
Neither of us compared notes.
“That was deliberate,” Mom said, reading one of his emails.
“Yes,” I answered.
She cried then. I let her.
The business records explained the rest.
Brooke and Jason had opened Bennett Home Consulting to buy and renovate houses. Dad guaranteed a private business loan because Jason promised a return big enough to restore his savings.
But there were no houses.
Most of the borrowed money had gone to personal spending and a failed investment account.
The lender wanted repayment.
Dad’s solution was to refinance the mansion, use part of the proceeds to clear the business debt, and divert the amount supposedly owed to me into Brooke’s company.
My claim would be pushed behind the new mortgage. The paperwork would suggest I had received money I would never see.
“And afterward?” I asked.
Mom looked down at the transfer documents.
“Afterward, he intended to give Brooke his share of the house.”
He had planned to stay there himself. I would leave, the payments would somehow continue, and Brooke would get the home he had promised her.
Then Rachel found the document that changed Mom’s expression completely.
A marriage certificate.
Brooke and Jason had married eight months earlier.
Dad knew. Mom and I didn’t.
The house wasn’t meant to be a wedding gift.
It was part of a rescue plan for a married couple whose finances were already collapsing.
That afternoon, Brooke came to my temporary apartment alone.
She looked smaller without Dad answering for her.
“Jason left,” she said.
I waited.
“He took what was in the business account. He says the loan is Dad’s problem.”
“Did you know about the false signature?”
Her eyes filled.
“I knew you hadn’t signed yet.”
“That isn’t what I asked.”
After a long silence, she admitted Dad had told her he would copy my signature from the original agreement.
She had watched him do it.
I set my coffee down.
“You sat across from me and accepted the house.”
“I thought once everything was fixed, we could pay you back.”
“With what?”
She had no answer.
I asked her to leave. Later, through Rachel, she provided a written account of what she had witnessed.
I didn’t thank her for finally telling the truth.
The next months were quieter than that dinner and much harder.
Mom insisted on selling the house. As a co-owner, she refused to sign another mortgage or transfer her interest to Brooke.
Dad fought her until the unpaid bills and the business guarantee left him with few choices.
The sale paid the existing mortgage, closing costs, and my documented loan. Rachel checked the final figures before I signed the release.
Dad received far less than he had expected.
The bank referred the false documents for investigation. Eventually, Dad accepted a plea agreement involving probation, restitution, and community service.
I didn’t attend that hearing.
Mom moved into a small townhouse. She began managing her own accounts and apologized without asking me to make her feel better.
Brooke took a bookkeeping job and filed for divorce. We speak occasionally. Trust has returned slowly, in small things she actually does.
When my apartment repairs were finished, I moved home.
On the first evening, Mom came over carrying takeout.
Before she sat down, she asked, “Is this a good time?”
I opened the door wider.
During dinner, my phone confirmed the final repayment had cleared. I looked at the balance, then put the phone away.
For six years, payday had meant checking whether my parents’ house was safe.
That night, I finished my meal while it was still warm.