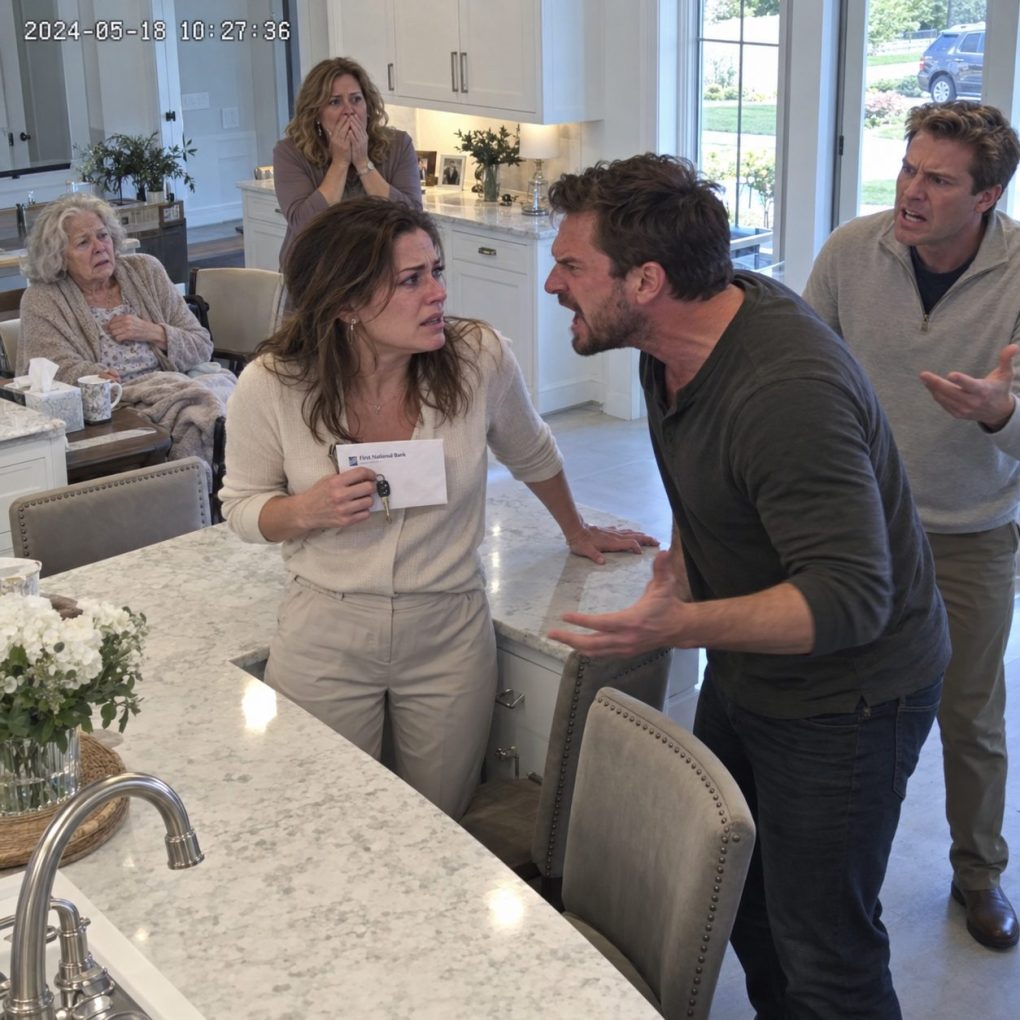
My husband slammed me against the kitchen island when I refused to sell his mother’s $450,000 house. Pain shot through my ribs. His brother needed $180,000, and Eric shouted that I wasn’t family unless I signed. He didn’t know I’d already stopped the money at the bank.
I’m Laura Mitchell, forty-two, a physical therapist in Cleveland. For years, I cared for Eric’s mother, Rose, through arthritis and heart surgery. Her house was entirely hers, mortgage-free, and she wanted to stay there with home-care visits, not move into a facility.
Rose had appointed me her agent under a durable power of attorney, prepared by her lawyer while she was mentally clear. It wasn’t my property. I had to act for her benefit, and she explicitly forbade using her home to rescue her sons.
Eric’s younger brother, Kyle, had run his auto-repair business into debt. Creditors were demanding nearly $180,000. Instead of negotiating repayment, the brothers decided Rose’s house was their solution. Eric arrived home carrying a listing agreement and ordered me to sign for Rose.
I pushed the papers away. Rose had told me that morning she would not sell. Eric grabbed my shoulders and drove me backward into the granite counter. A glass shattered near my feet. He leaned close and screamed that I was only a daughter-in-law, never real family.
He assumed I hadn’t spoken to the bank. After Rose received a letter about a $180,000 home-equity loan, we visited her lender. She hadn’t applied. A loan officer confirmed her objection, suspended the application, and opened a fraud investigation.
I had brought home the bank’s written confirmation. The application used Rose’s identification and a signature she denied making. Its contact email belonged to Kyle’s business. No loan had been approved, and no money had left the bank. Eric had no idea the file existed.
When I reached for my phone, Eric knocked it from my hand. I backed toward the hallway and shouted for help. Our neighbor, who’d heard the crash through an open window, called 911. Eric picked up the unsigned listing agreement and tried to hide it in a drawer.
Officers arrived while I was still pressing a towel against my bleeding elbow. They separated us and photographed my injuries. Eric claimed we’d argued over his mother’s living arrangements. I told them about the assault, the demanded signature, and the home-equity application.
One officer examined the bank letter and asked who stood to receive the loan proceeds. I pointed to the destination listed on the application: Kyle’s business account. Then I showed her Eric’s text from that morning, threatening to make me sign the sale papers.
At the emergency department, a doctor treated my cut and diagnosed bruised ribs. I went home with my sister, not Eric. By morning, an officer had referred the suspicious loan application for a separate financial investigation, and I had contacted a family-law attorney about protecting myself.
Rose called as soon as she heard. She’d spent the night at home with a visiting caregiver and was furious that her sons had used her illness as an excuse. She asked me to come, but I wouldn’t risk meeting Eric there without a plan.
Instead, Rose’s attorney arranged a meeting at his office. He confirmed she understood her finances and still wanted me to act as her agent. She signed instructions barring any sale or borrowing for Kyle’s debts, and authorized him to communicate directly with the lender.
The bank’s fraud department later provided Rose and her lawyer with records from the rejected application. It named Kyle’s shop as the proposed recipient of the proceeds. The electronic submission came from an email account he controlled, but investigators still needed to establish who had signed the forms.
Kyle told Rose it was just a preapproval request. Then he admitted he’d used documents Eric photographed while visiting her. He insisted the loan would have saved his business and that he planned to repay it. Rose asked why he’d never bothered requesting her permission.
He answered that she would have refused. That single admission changed everything. Rose had spent years helping both sons, believing their emergencies were temporary. Now she understood they regarded her home as money they could collect before she was even gone.
Eric sent me flowers, followed by messages demanding I withdraw the assault complaint. He claimed I’d embarrassed his family and caused Kyle’s creditors to panic. I preserved every message and let my attorney respond. I also requested a protective order and filed for divorce.
When police interviewed me again, I gave them the text about forcing a sale. They asked for the original phone records, not just screenshots. Rose separately gave a statement about the unauthorized loan. The investigations proceeded without either of us declaring anyone guilty in advance.
Kyle’s wife called one night, crying. She said he had hidden delinquent loans and planned to use Rose’s equity to clear debts she hadn’t known existed. I didn’t offer her money or advice. I told her to consult an independent attorney before signing anything herself.
Two weeks after the kitchen assault, Rose changed the locks and hired a home-care coordinator. She asked Eric and Kyle to stay away while matters were resolved. I sat beside her as she signed the paperwork. My ribs hurt, but neither of us would sacrifice her future.
The following months were exhausting. I attended medical appointments, met with my attorney, and answered investigators’ questions. The bruises faded before I stopped flinching at slammed doors. Rose called every Sunday, reminding me that leaving Eric hadn’t meant abandoning her.
The lender confirmed that the $180,000 loan had never been funded and that no new lien had been placed on Rose’s property. Its review found falsified information in the application. Those findings were forwarded to investigators, who continued examining Kyle’s and Eric’s roles.
Eric eventually accepted a negotiated resolution in the assault case, including probation and a no-contact condition. The financial inquiry continued separately; no court had yet decided responsibility for every document. I was relieved to have boundaries backed by an order, even without a perfect ending.
Our divorce required months of financial disclosures. Eric tried to describe the kitchen incident as a misunderstanding about caregiving, but I would not bargain away the truth to speed up the process. The court addressed our property and support issues without treating Rose’s house as ours.
Kyle sold equipment from his shop and negotiated repayment plans with creditors. Rose refused to pledge her home. She also refused to let guilt make her responsible for debts she’d never agreed to assume. Her lawyer updated her estate documents to reflect her choices, not her sons’ demands.
I continued visiting Rose after my marriage ended. Sometimes we talked about her garden; sometimes about how frightening the bank letter had been. She told me she regretted teaching Eric that protecting family meant rescuing anyone who demanded it. I reminded her his violence was his decision.
One afternoon, Rose asked whether I wanted to stop serving as her financial agent. I said I would if it made her life easier. Instead, she asked her attorney to appoint an independent professional as a backup, so neither of us would face pressure alone.
By autumn, Rose was still living in the house with scheduled help and a medical alert system. The bank’s fraud warning remained in place. I had rented a sunny apartment across town and returned to work after recovering from the injury.
Eric wrote once, saying he’d lost both his marriage and his mother’s trust over a house that wasn’t his. I didn’t respond. What he’d lost wasn’t property. He’d thrown away the trust of two women because he believed their signatures belonged to him.
On Thanksgiving, Rose invited me for dinner. We ate in her familiar kitchen, the mortgage-free house still hers. She squeezed my hand and thanked me for saying no. I thought of that night against the granite island. He had called me an outsider. I had been the one who protected his mother.