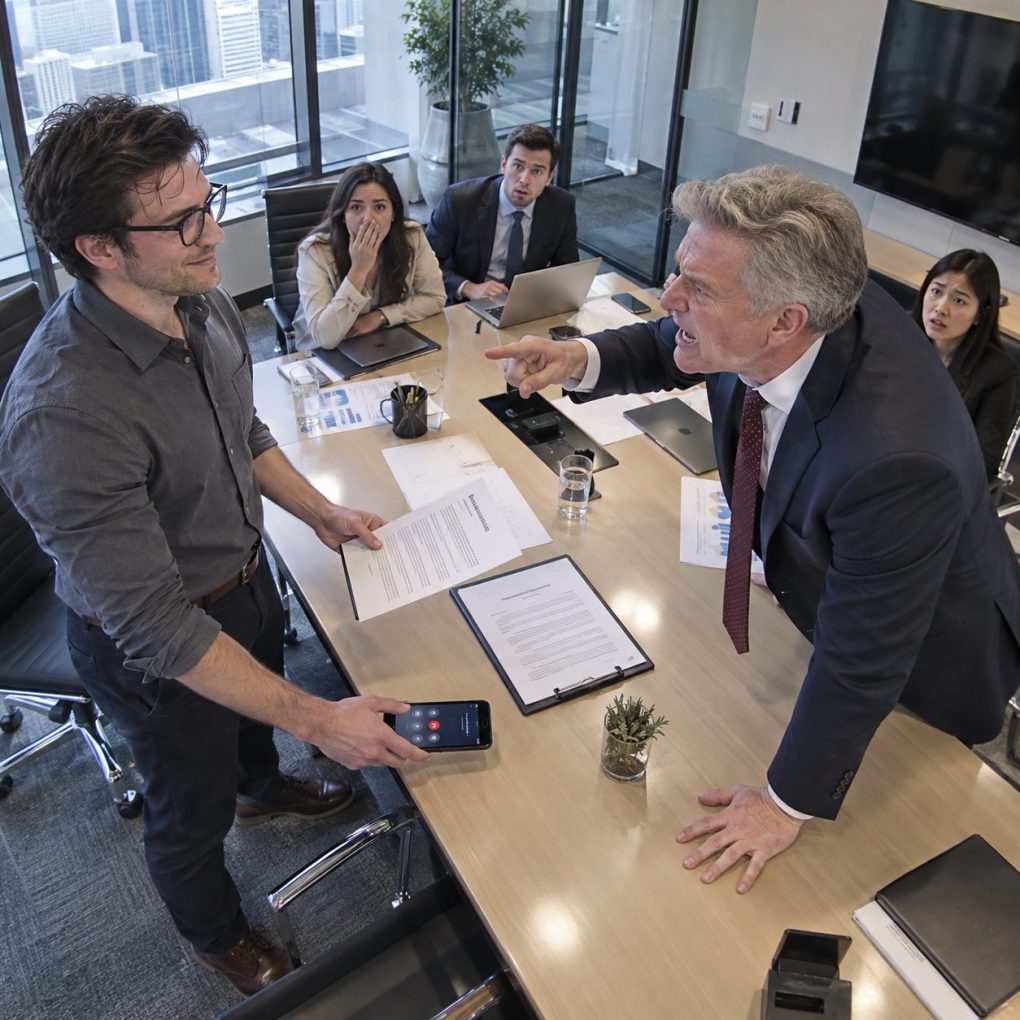
“Sign this acknowledgment, Eleanor, or I’ll have HR demote you before the end of the day.”
Richard Collins, the regional director of Sterling Financial Group, slid a single sheet of paper across the conference table, wearing the satisfied expression of a man who believed he had finally cornered the employee who had been challenging him for months. Six executives sat around us, the HR director stared at her laptop, and a dozen floors below, hundreds of employees continued working without realizing that one signature could expose a financial disaster hiding inside their company.
I looked at the paper.
Then I smiled.
“Good,” I said. “Because the second you hand me that paper, this company owes me eight figures.”
Richard laughed, assuming I was bluffing.
My name is Eleanor Brooks, I was forty-four, and I had spent eleven years building Sterling’s commercial lending division in Chicago, turning a struggling department into one of the company’s most profitable operations. I wasn’t the loudest person in meetings, and I didn’t spend my afternoons networking over expensive lunches, but I understood financial contracts, lending covenants, and the small details that could turn a profitable deal into a multimillion-dollar liability.
Six months earlier, I had discovered that Sterling had incorrectly classified a group of commercial loans during a major refinancing agreement with First National Bank. The error wasn’t mine; it had originated in a restructuring project overseen by Richard’s team, but my department had been instructed to certify the final numbers before the agreement closed.
I refused.
I documented the discrepancy, notified compliance, and requested a formal review before signing anything that would certify the figures as accurate. Richard called me difficult, accused me of delaying the transaction, and quietly removed me from two important meetings, hoping I would eventually stop asking questions.
I didn’t.
Three weeks later, Sterling’s legal department discovered that the refinancing agreement contained a specific provision addressing material misrepresentations in the loan portfolio. If the bank determined that Sterling had knowingly certified inaccurate information, it could demand repayment, terminate certain financing arrangements, and pursue contractual remedies.
The potential exposure was enormous.
But there was another detail Richard had apparently forgotten: my employment agreement contained a negotiated protection clause, added after I had threatened to leave during the previous year’s restructuring. If Sterling terminated me or materially reduced my position in retaliation for raising a documented compliance concern, the company could owe me accelerated compensation, including a substantial retention award and contractual damages, subject to the agreement’s conditions.
The potential payout exceeded ten million dollars.
Richard had spent the previous month trying to force me into accepting a lower position, believing that I would rather protect my salary than risk losing my career.
Now he was offering the exact written action my attorney had warned him not to take.
“You’re threatening me with a lawsuit?” he scoffed. “You’re a middle manager, Eleanor, not a shareholder.”
I folded my hands on the table.
“No, Richard. I’m telling you to read the agreement you approved.”
Then I took out my phone, placed it on the table, and called First National Bank’s commercial lending office on speakerphone.
When the bank’s senior relationship manager answered, I asked one question.
“Can you confirm whether Sterling has formally corrected the loan certification I reported, or whether the original representation remains in force?”
Richard’s smile disappeared.
The HR director stopped typing.
And when the bank representative replied, “Ms. Brooks, our records show that the certification remains unresolved, and our legal department is waiting for Sterling’s response,” every person in that conference room turned toward Richard.
He reached for my phone.
I pulled it away.
“Don’t,” I said quietly. “You wanted a paper trail. Let’s make sure we have one.”
Richard stood so abruptly that his chair scraped against the conference-room floor, and for a moment I thought he might order everyone out, but the bank representative was still speaking through my phone, asking whether Sterling’s authorized officers were available to discuss the unresolved certification.
I answered calmly, identifying myself as the employee who had raised the discrepancy and explaining that I was not authorized to make representations on the company’s behalf. I then asked the representative to direct all further questions through Sterling’s legal and compliance departments, because I wanted the issue addressed properly rather than turned into a confrontation between two executives.
Richard stared at me.
“End the call, Eleanor.”
“I will once the representative confirms that the matter has been referred to the appropriate department.”
The bank representative confirmed that the file would remain under review and that its legal team would contact Sterling’s designated officers, after which I ended the call and placed my phone beside the unsigned demotion notice. Nobody spoke for several seconds, and the silence felt very different from the one Richard had expected when he walked into the room.
He finally turned toward the HR director.
“This meeting is over.”
“Not quite,” I said, opening the folder I had brought with me. “Before anyone leaves, I’d like HR to confirm whether this proposed demotion is based on documented performance issues or on my refusal to certify figures I believe are inaccurate.”
Richard’s face reddened.
“You’ve been insubordinate for months. You question every decision, delay projects, and act as if you’re the only person here who understands risk.”
“I reported a specific financial discrepancy, provided supporting documentation, and followed the compliance process,” I replied. “If you believe my performance warrants a demotion, the company can document its reasons through the normal procedure.”
The HR director asked Richard whether he had completed a performance review or issued any formal warning related to my work, and his hesitation was answer enough. My performance reviews had been consistently strong, and the company’s own records showed that I had exceeded my lending division’s targets for three consecutive years.
Richard had no written basis for the sudden demotion.
He had assumed that because he controlled my reporting line, he could pressure me into signing a document that would make the decision look voluntary, but the wording on the paper was more dangerous than he realized: it required me to acknowledge that the reassignment was based on performance concerns and that I had no outstanding objections to the company’s treatment of my compliance report.
I refused to sign.
Instead, I asked HR to preserve the proposed notice, the meeting invitation, and any communications concerning the demotion, and I stated that I would refer the matter to my attorney before responding to any employment action.
Richard scoffed at the mention of legal counsel, but the HR director interrupted him.
“Richard, we need to stop here until legal reviews this.”
For the first time, he seemed to understand that the meeting had moved beyond his control.
I left the conference room without celebrating, because I knew that a bank’s concern did not automatically prove fraud, and a contractual clause did not guarantee that I would receive ten million dollars. Both issues required formal review, and the actual consequences would depend on the evidence, the contract’s language, and the company’s response.
Still, I had accomplished something important.
The company could no longer pretend that I had never raised the problem.
That afternoon, Sterling’s general counsel contacted me and asked for copies of my original compliance reports, including the dates on which I had raised the loan-classification discrepancy and the responses I had received. I provided the records through the company’s secure reporting channel, keeping my own lawful copies of relevant employment documents and avoiding any unauthorized access to confidential files.
Two days later, the board’s audit committee requested an independent review of the loan portfolio and the handling of my earlier report. Richard was removed from direct oversight of the refinancing matter while the review proceeded, a precaution the company described as necessary to protect the independence of the investigation.
The demotion notice was withdrawn pending legal review.
My attorney also examined the employment agreement and confirmed that the protection clause could create a substantial claim if the company took prohibited retaliatory action, although the exact amount and enforceability would depend on the specific facts. We did not assume that the eight-figure figure was guaranteed, and I agreed not to make public statements about the bank’s review while the matter remained active.
For the first time in months, I could concentrate on the evidence instead of defending myself against Richard’s pressure.
But the investigation was only beginning.
Over the following six weeks, the independent review uncovered a series of classification errors in the commercial loan portfolio, including several that had been carried forward from the restructuring project Richard had overseen. The review did not establish that every error was intentional, but it found that warnings from my team had not been properly escalated before the refinancing certification was submitted.
That distinction mattered.
A financial mistake could be corrected, but ignoring a documented warning and certifying information without resolving a known discrepancy could create far more serious contractual and regulatory consequences. Sterling’s legal team began negotiating with First National Bank to correct the affected records and determine whether the refinancing agreement required additional disclosures or adjustments.
Richard was required to cooperate with the investigation, and the company temporarily reassigned several of his responsibilities while the audit committee reviewed how the original certification had been approved. He insisted that he had relied on the figures provided by his team, but emails showed that he had been informed of at least one unresolved discrepancy before the certification was finalized.
I was interviewed twice, and each time I provided the same timeline, the same documents, and the same explanation of why I had refused to sign off on the figures. I didn’t embellish the evidence or speculate about Richard’s intentions, because I understood that the credibility I had built over eleven years was worth more than a dramatic accusation.
Meanwhile, my attorney and Sterling’s counsel reviewed the employment agreement separately from the banking investigation. The company initially argued that the protection clause did not apply because no demotion had been finalized, while my attorney pointed out that the proposed notice and the circumstances surrounding the meeting could still be relevant to whether Sterling had attempted to pressure me for raising a compliance concern.
We entered negotiations.
I was not demanding payment simply because Richard had embarrassed himself in a conference room, and I had no intention of accepting money in exchange for remaining silent about a legitimate compliance issue. My position was that the company needed to honor its contractual obligations, protect employees who reported concerns in good faith, and resolve any employment dispute through a documented process.
After several rounds of discussions, Sterling agreed to withdraw the proposed demotion permanently, restore my full responsibilities, and revise its internal process for escalating material loan-reporting discrepancies. The company also agreed to a confidential financial settlement based on the employment agreement, the risks associated with the disputed employment action, and the costs of continued litigation.
The settlement was substantial, but it was lower than the maximum amount I had originally calculated under the most favorable interpretation of the clause. My attorney explained that the final amount reflected a negotiated resolution rather than a court judgment, and I accepted it because it gave me certainty without requiring years of litigation.
The bank issue was resolved separately, with Sterling correcting the affected loan information and negotiating appropriate contractual adjustments with First National Bank. The bank did not simply hand the company a clean bill of health, but the parties reached an agreement that allowed the financing relationship to continue under revised reporting requirements and additional oversight.
Richard eventually resigned from his regional director position after the board completed its review of his management decisions and handling of the compliance concerns. Sterling did not publicly characterize his departure as a finding of fraud, and neither did I, because the documented conclusions mattered more than the rumors circulating around the office.
A few months later, I was appointed senior director of commercial risk and portfolio strategy, with responsibility for strengthening the controls that had failed during the refinancing process. My new role came with a higher salary, broader authority, and direct access to the audit committee when significant reporting concerns arose.
On my first day in the new position, I walked into the same conference room where Richard had once slid the demotion notice across the table, and I placed a copy of the updated escalation procedure beside the meeting agenda.
A junior analyst asked whether senior executives really had to follow the same reporting rules as everyone else.
I looked around the table before answering.
“Especially senior executives,” I said. “The higher your authority, the more important it is that your decisions can withstand scrutiny.”
Months earlier, Richard had believed that a title gave him the power to silence anyone who challenged him, and he had mistaken my calmness for fear because I had refused to turn every disagreement into a public battle.
He was wrong.
The phone call had not magically made the company owe me eight figures, and the bank had not rescued me simply because I asked the right question; what changed the outcome was the evidence I had preserved, the contract I had negotiated, and my refusal to sign a document that misrepresented the circumstances of my demotion.
I eventually received a settlement, kept my career, and helped correct a financial process that could have exposed the company to far greater losses, while Sterling learned that compliance obligations could not be dismissed as personal disagreements between executives.
Richard had handed me that paper believing it would end my career. Instead, it became the document that forced the company to confront the risks I had warned about for months—and proved that the most powerful person in the room is not always the one sitting at the head of the table.