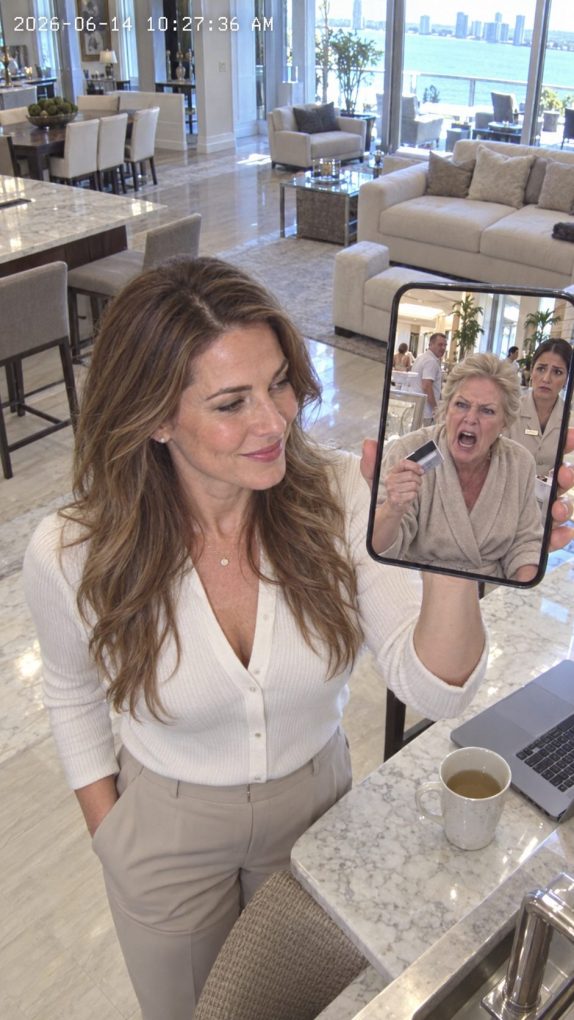
Four days after our divorce, my ex-mother-in-law called from a luxury resort in Naples, Florida, screaming about her declined credit card. I’d paid her bills for nine years. I calmly replied, I’m sorry, who is this? She went silent, then threatened to expose a $280,000 loan supposedly carrying my signature.
My name is Claire Bennett. I’m forty-two, a financial consultant living in Charlotte, North Carolina. My ex-husband, Aaron, had convinced me his mother, Judith, couldn’t survive without our financial support. I paid her rent, car insurance, medical expenses, and countless vacations while she called me selfish.
When our divorce became final, I removed Judith as an authorized user from my personal credit card. The account belonged entirely to me. Aaron had agreed during our settlement that neither he nor his mother had any right to my future income.
Judith apparently discovered the change while attempting to pay for a five-night resort stay. Her first call contained twenty seconds of screaming. She demanded that I reactivate the card immediately because the hotel was threatening to charge her another way.
I reminded her that she had a son. Judith laughed bitterly and announced that Aaron had anticipated my betrayal. According to her, I had personally guaranteed a $280,000 business loan eight months earlier. If I refused to cooperate, the lender would come after everything I owned.
I felt my stomach tighten. Aaron’s consulting business had struggled for years, but I’d never guaranteed its debts. Our divorce financial disclosures contained no such loan. When I demanded an explanation, Judith said she possessed documents proving my obligation.
Then she revealed something even worse. Aaron had supposedly used my townhouse as evidence of my ability to repay. Judith claimed the bank could eventually force me to sell it. She promised to make the problem disappear if I restored her spending privileges.
I ended the call and opened my laptop. My credit monitoring service showed an unfamiliar commercial lending inquiry from eight months earlier. I had overlooked the notification while preparing for divorce. Now the lender’s name matched the one Judith had mentioned.
I contacted my attorney, Rebecca Collins, and described the threat. She instructed me to preserve Judith’s voicemail and avoid discussing payments. We requested the loan documents and contacted the lender’s fraud department. Within hours, an account representative confirmed that my name appeared on a personal guarantee.
That evening, Rebecca emailed me the preliminary documents. Beneath the $280,000 obligation was an electronic signature resembling mine. But the verification phone number belonged to Judith. My ex-husband hadn’t simply hidden a loan from me. Someone had used my identity to obtain it.
The next morning, Rebecca accompanied me to the lender’s regional office. Fraud investigator Daniel Hayes explained that Aaron’s company had borrowed $280,000 to finance an expansion. My alleged personal guarantee helped obtain approval, but the loan had already fallen behind on payments.
I showed Daniel my phone records and the divorce disclosures. The electronic signing certificate listed a verification code sent to Judith’s number. I had never received that code, and I had never authorized anyone to sign a guarantee on my behalf.
Daniel explained that the lender would investigate the disputed authorization. My name appearing on the paperwork didn’t automatically prove consent. He arranged for the account to be flagged while investigators reviewed the records and told us the bank would communicate through our attorney.
Rebecca helped me file an identity theft report and formally dispute the obligation. We also requested the supporting application, including the income statements Aaron had submitted. Those documents revealed that someone had copied information from an old joint tax return without my permission.
Then Daniel showed us the disbursement history. Only a fraction of the borrowed money had funded legitimate business expenses. Large transfers went to a company controlled by Judith, supposedly for administrative consulting. Her company had no employees and no documented services.
One payment had covered outstanding charges associated with a luxury travel agency. Another had financed renovations to Judith’s vacation condominium. While I worked overtime paying her bills, Aaron and Judith had been diverting borrowed money into their own extravagant lifestyle.
Aaron called that afternoon, furious. He accused me of trying to destroy the family business and claimed the guarantee was merely paperwork. I asked why his mother had received the verification code. He stopped speaking. Then he offered to settle everything privately if I withdrew my complaint.
I refused. Aaron suddenly changed tactics, reminding me that we had been married when the loan was obtained. He insisted that spouses were supposed to support each other financially. Rebecca later explained that marriage did not authorize him to forge my consent to a personal guarantee.
Judith sent another message threatening to expose my supposed dishonesty to clients. I forwarded it to Rebecca. Meanwhile, investigators requested Aaron’s business records and discovered emails discussing how to secure financing without involving me directly. One message described my excellent credit as their last available resource.
Two weeks later, the lender confirmed that significant evidence supported my fraud report. The matter was referred for further investigation, and the bank agreed not to pursue the disputed guarantee against me while the claim was resolved. Judith called again, but this time her voice trembled. She asked whether we could forget the whole misunderstanding.
I didn’t answer Judith’s request. Rebecca informed her attorney that all further communication needed to go through legal counsel. After nine years of paying her expenses, I finally understood that the money had never purchased affection. It had only encouraged her to demand more.
The lender’s investigation continued for several months. Electronic records showed that the disputed signing process had been completed using a device associated with Aaron’s office. The verification code had gone to Judith’s phone, and neither could produce evidence that I’d authorized the transaction.
After examining the records, the lender formally released me from the disputed guarantee. It pursued repayment from the actual borrowing company and referred evidence of suspected fraud to investigators. Rebecca also arranged for corrections to my credit records and confirmation that my townhouse was not collateral.
Authorities subsequently filed charges against Aaron relating to the fraudulent application. Judith’s involvement was investigated separately. Both retained attorneys, and the criminal proceedings followed their own course. I didn’t attend every hearing. My priority was rebuilding the life their decisions had interrupted.
During the investigation, I learned that Aaron’s business was deeply insolvent. The borrowed money had postponed its collapse without solving its problems. Judith’s travel spending had continued because both assumed I’d eventually rescue them, just as I’d done throughout our marriage.
Aaron’s company closed, and he negotiated with creditors through his attorney. Judith sold her vacation condominium to address personal financial obligations. Neither could continue using my credit card. The resort bill that triggered her furious phone call remained her responsibility to resolve.
Three months later, Judith sent a handwritten letter. She apologized for threatening me but insisted she’d always considered me a daughter. I remembered the birthdays she’d forgotten, the insults she’d delivered, and the vacations I’d financed while she complained I wasn’t generous enough.
I returned the letter unanswered. I wasn’t interested in proving that I could forgive someone who’d never respected me. I continued therapy, spent weekends with friends, and rediscovered simple pleasures I’d sacrificed while supporting a family that treated my generosity like an obligation.
On my forty-third birthday, I took my first vacation without paying anyone else’s expenses. I booked a quiet oceanfront hotel, ordered dinner overlooking the water, and switched off my work phone. For the first time in years, I didn’t worry about another person’s credit card balance.
At sunset, I remembered Judith screaming from her luxury resort, demanding that I rescue her again. She thought her threat would frighten me into obedience. Instead, it exposed the financial deception she’d helped conceal. My divorce had ended a marriage, but that phone call ended something deeper: nine years of believing I had to buy my place in someone else’s family.