When My Son Told Me to Delay My Retirement to Keep Paying His Bills, I Silently Cut Off His Mortgage and Tuition. 4 Days Later, I Had 38 Panic-Filled Voicemails.
“Dad, you can work three more years.”
My son said it over Sunday dinner, without even looking up from his phone.
I was sixty-seven years old. After forty-two years of working, I had planned to retire at the end of the month. I wanted to spend my mornings fishing, take a road trip across the country, and finally stop checking my bank account before buying something for myself.
But apparently, my retirement wasn’t just my decision.
“Three more years,” my son, Michael, repeated. “That’s not asking much.”
His wife, Lauren, nodded while cutting food for their eight-year-old daughter. “We still have the mortgage, the kids’ tuition, insurance, everything. You know how expensive things are now.”
I looked at my granddaughter, Emily, who was quietly coloring beside her plate. Then I looked at my son.
For the past six years, I’d paid $2,400 a month toward Michael’s mortgage. I covered private-school tuition for both children, their family health insurance, and occasional emergencies that somehow happened every month.
I had never complained.
I’d told myself I was helping my family get established. But somewhere along the way, helping had become an obligation, and my paycheck had become something they considered theirs.
“I’m tired, Michael,” I said. “My retirement papers are already filed.”
He finally looked at me.
“Then delay them.”
Lauren sighed. “It’s not like you’re going to sit around doing nothing. You could keep working and help your family at the same time.”
Something inside me went quiet.
My family.
I’d spent decades making sure they never had to worry about money. Yet nobody had asked whether I was worried about my own future.
I smiled, folded my napkin, and stood.
“You’re right,” I said. “I need to think about what’s best for everyone.”
Michael relaxed immediately.
“That’s all I’m saying, Dad.”
I drove home alone that night.
At 7:15 the next morning, I called my bank.
By 8:00, I had canceled the automatic mortgage payments, withdrawn my commitment to cover future tuition bills, and removed my credit card from their recurring household expenses.
I wasn’t stealing anything from them. I was simply stopping payments on bills that weren’t mine.
Then I booked a three-week road trip and transferred money into an account reserved for my retirement.
For the first time in years, I felt free.
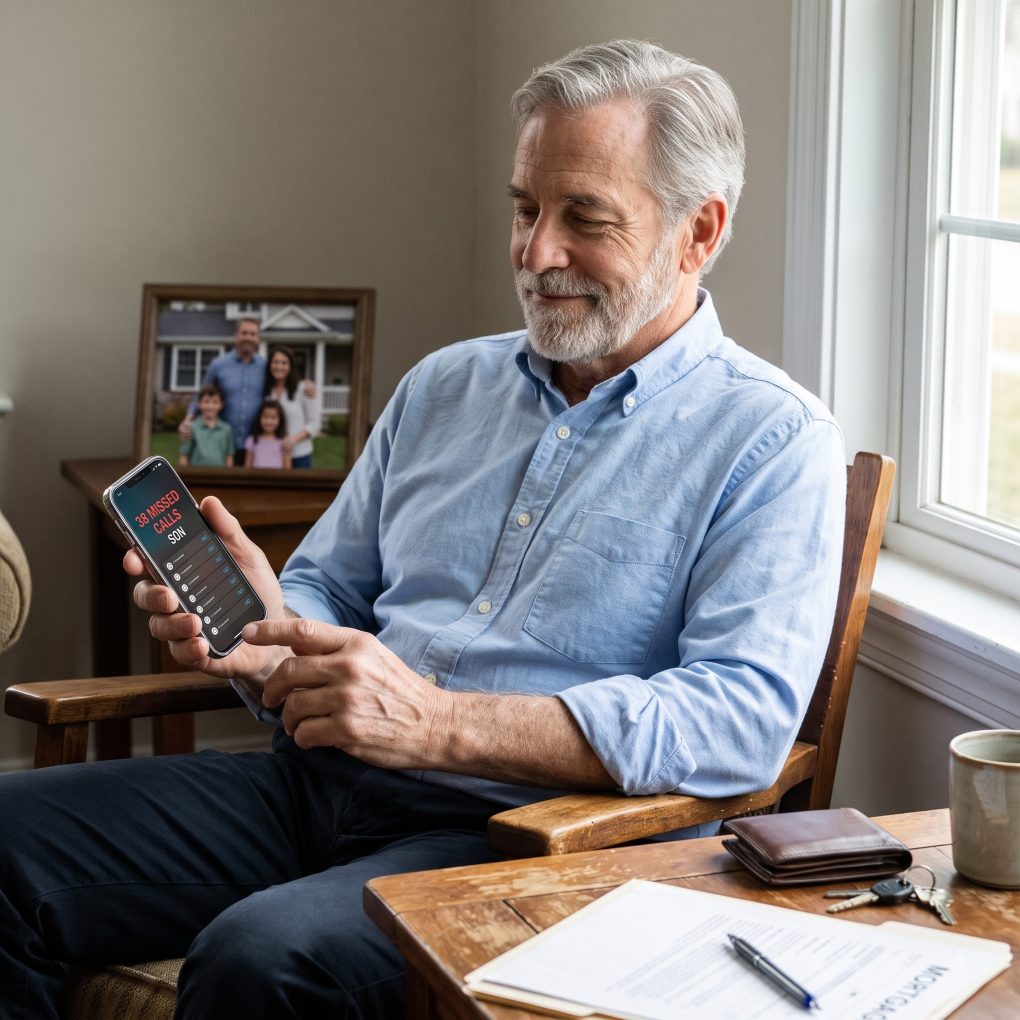
Four days later, my phone showed 38 missed calls and voicemails.
Michael’s latest message began with a scream.
“DAD! THE BANK JUST CALLED! WHAT DID YOU DO?!”
I pressed play on the next voicemail.
And when I heard the name he mentioned, I realized my family had been hiding something far bigger than their monthly bills.
The name in Michael’s voicemail was mine.
Not my first name. My full name, followed by the words “co-signer” and “past-due balance.”
I sat at my kitchen table and played the message again.
“Dad, call me back immediately! The bank says the mortgage is overdue, and they claim you’ve stopped paying. You can’t just do this without warning us! There’s a problem with the loan, and if you don’t fix it today, we’re in serious trouble!”
I had stopped paying the mortgage contribution I had voluntarily made every month. I had never signed their mortgage, guaranteed their loan, or promised to finance their house forever.
So why was the bank mentioning my name?
I called Michael.
He answered on the first ring.
“Finally! Dad, you need to call the bank and tell them you’ll resume the payments.”
“Good morning to you, too.”
“This isn’t funny!”
“I’m not joking. I retired. I canceled my payments. That’s all.”
He lowered his voice. “You don’t understand. We budgeted around that money.”
“No, Michael. You built your budget around my paycheck.”
There was a long silence.
Then he said, “Mom would never have let you do this.”
My late wife, Susan, had been gone for five years. Before she died, she’d often told me that I’d raised a son who knew how to ask for help but hadn’t learned when to stand on his own.
I had dismissed those words as a mother’s worry.
Now I wasn’t so sure.
“Your mother isn’t here to make this decision for me,” I said. “And neither are you.”
He hung up.
An hour later, Lauren called. Her voice was softer, but her words were sharper.
“Your grandchildren could lose their home because you’re having some kind of midlife crisis.”
“I’m sixty-seven, Lauren. I think the crisis would be continuing to work until I drop because you don’t want to adjust your spending.”
She gasped.
“We’ve sacrificed so much!”
I looked around my quiet home. For years, I’d postponed vacations, ignored repairs, and driven an aging car because my family always seemed to need another payment.
“What exactly have you sacrificed?” I asked.
She ended the call.
That afternoon, I visited my financial adviser, Helen Brooks. I showed her the voicemail and explained the bank’s reference to a co-signer.
Helen frowned.
“Have you ever signed any documents connected to Michael’s mortgage?”
“No.”
“Any home-equity loan? Any refinancing paperwork?”
“No. I gave them money every month. I never agreed to be legally responsible for their debt.”
She advised me to obtain my credit reports and request written clarification from the bank. We also reviewed my accounts to make sure nobody had unauthorized access.
By evening, I had an answer.
My name appeared on an application for a recent home-equity loan against Michael and Lauren’s house.
The application listed me as a supporting guarantor.
And attached to it was a digital signature bearing my name.
I had never seen the document.
I stared at the screen while Helen contacted the bank’s fraud department.
Then my phone buzzed.
A text from Michael.
Dad, don’t make this bigger than it needs to be. We can explain everything if you just come over tonight.
I read it twice.
For the first time, I wondered whether my son had been counting on my paycheck—or whether he’d been counting on something much more valuable.
My signature.
I didn’t go to Michael’s house that night.
Instead, Helen helped me contact an attorney who handled financial fraud and identity theft. The attorney, Patricia Wells, told me not to confront my son until we understood exactly what had happened.
“If your signature was used without permission, we need to preserve the records,” she explained. “Don’t sign anything new, don’t agree to cover the loan, and don’t let anyone pressure you into accepting responsibility for something you didn’t authorize.”
The next morning, Patricia and I met with the bank’s fraud department.
The loan application was dated three months earlier. Michael and Lauren had borrowed $86,000 against the equity in their house. The money had supposedly been intended for home improvements and debt consolidation.
But the application included another detail.
I had allegedly agreed to guarantee the loan using my retirement income.
My annual salary was listed correctly. So was the name of my former employer.
Someone had clearly obtained accurate information about me.
The signature looked convincing at first glance. But the application claimed I had signed it electronically on a Tuesday afternoon when I had been at a retirement-planning seminar, something I could verify through the seminar’s registration records.
The bank opened a formal investigation and placed restrictions on the disputed guarantee while it reviewed the evidence.
I went home feeling sick.
For years, I’d told myself that money was the one thing I could reliably give my family. I couldn’t bring Susan back. I couldn’t prevent every disappointment my son might face. But I could make sure he never struggled the way we had when he was young.
Somehow, that desire had turned into permission for everyone to make decisions with my money.
On the fourth evening after I stopped the payments, Michael finally came to my house.
He didn’t knock gently. He hammered on the door.
When I opened it, he strode inside, followed by Lauren.
“You’ve gone too far,” he said.
I closed the door behind them.
“Hello, Michael. Hello, Lauren.”
“Don’t do that,” he snapped. “Don’t pretend this is a normal visit.”
“Then tell me why you’re here.”
He dropped a folder onto my coffee table.
“The bank needs you to sign a confirmation form. It will clear up the misunderstanding about the loan.”
I didn’t touch it.
“What misunderstanding?”
Lauren crossed her arms. “You helped us financially for years. You knew we depended on you. This is just paperwork to keep everything running smoothly.”
“Did I agree to guarantee your $86,000 loan?”
Michael looked away.
“Dad, we were going to explain.”
“Did I sign this application?”
He rubbed his forehead.
“You’re making it sound like a crime.”
“I’m asking a question.”
Lauren stepped forward. “We had bills piling up. The kids’ school costs more every year. The house needed repairs. Michael’s business expenses—”
“Then you should have discussed those problems with me,” I interrupted. “You should not have used my name to borrow money.”
Michael’s face hardened.
“You were going to keep working anyway. We knew you could afford it.”
There it was.
Not an apology. Not even an excuse.
An assumption.
I had spent years telling myself that my son was generous at heart but careless with money. Now I was standing in my living room listening to him explain why my retirement savings were a resource he had every right to use.
“Who submitted the application?” I asked.
Neither answered.
I picked up my phone.
“If you won’t tell me, I’ll let the bank’s investigators determine that.”
“Dad, stop!” Michael shouted.
Lauren grabbed his arm.
For a moment, I thought he might finally tell the truth.
Instead, he looked at me with an expression I’d never seen before.
“You’re going to destroy your own family over money?”
“No,” I said quietly. “I’m refusing to let money destroy me.”
They left without signing anything or giving me an explanation.
The next week was difficult. Michael sent long messages accusing me of abandoning my grandchildren. Lauren posted vague comments on social media about relatives who only cared about themselves. A few family members called to ask why I was suddenly refusing to help my own child.
I didn’t argue with them.
I told them the same thing: I had retired, stopped voluntary payments, and discovered a disputed loan guarantee bearing my name. Anyone who wanted to understand the situation was welcome to hear the facts.
Most didn’t ask for them.
Meanwhile, the bank’s investigation continued. Its records showed that the loan application had been submitted through an email account Michael regularly used to communicate with the lender. The bank also identified inconsistencies in the electronic signing process.
The evidence did not establish every detail of who had done what, but it was enough to justify further scrutiny.
Patricia advised me to let the investigation proceed rather than making accusations I couldn’t yet prove.
Then, two weeks later, Michael called.
His voice was different. Smaller.
“Dad, can we talk?”
“We’ve been talking.”
“Not like this. In person. Just you and me.”
We met at a diner near my house the following afternoon.
Michael arrived early. He looked exhausted, with dark circles beneath his eyes and an untouched cup of coffee in front of him.
For several minutes, he spoke about the children, the mortgage, and Lauren’s growing anxiety. He said the household had been built around my contributions. When I stopped paying, they had immediately fallen behind on expenses they could no longer cover.
“I know I handled it badly,” he finally admitted.
“Which part?”
He looked at me.
“All of it.”
I waited.
He explained that he and Lauren had taken out the home-equity loan after accumulating credit-card debt and falling behind on other obligations. They had expected to keep receiving my monthly help, and the additional loan was supposed to give them breathing room.
When the lender asked for information about household support, Michael had included my income.
Then, according to him, the application had been completed without my direct involvement.
“Who used my signature?” I asked.
His eyes dropped to the table.
“I did.”
The answer hurt, but I didn’t react immediately.
“Did Lauren know?”
“She knew I was using your income to support the application. She says she didn’t know I signed your name.”
“Do you believe her?”
He shook his head slowly.
“I don’t know what to believe anymore.”
I told him the truth: I loved him, but I would not lie to the bank or take responsibility for a guarantee I had never agreed to provide. He would need to cooperate with the investigation and face whatever consequences followed.
He began to cry.
“I thought you’d always help me.”
“I always wanted to help you,” I said. “But I thought I was helping you build your life. I didn’t realize you thought I was supposed to finance it forever.”
He wiped his face.
“Are you going to stop seeing the kids?”
“No. Your children are not responsible for our mistakes. I’ll always be their grandfather. But I won’t use money to prove that I love them.”
That was the first honest conversation we’d had in years.
It didn’t repair everything.
The bank’s investigation continued, and Michael had to obtain independent legal advice about the disputed loan documents. I cooperated with the process and made it clear that I had not authorized the guarantee. The bank eventually removed me from the disputed obligation after reviewing the evidence and completing its investigation. Michael and Lauren remained responsible for addressing their own loan and financial difficulties.
Their situation wasn’t magically fixed. They had to speak with their lender, review their spending, and make painful decisions about what they could afford. Lauren returned to full-time work. Michael took additional projects and stopped paying for several luxuries they had treated as necessities.
Their children stayed in school, though the family reconsidered some expenses and made a more realistic plan.
I didn’t pay their mortgage again.
I didn’t cover their tuition bills.
And I didn’t apologize for retiring.
Three months later, I took the road trip I’d booked on the morning I canceled the payments. I drove through the mountains, stopped in small towns, ate breakfast wherever the coffee smelled good, and spent entire afternoons doing absolutely nothing.
For the first time since Susan died, my days belonged to me.
I bought a comfortable fishing chair. I repaired the porch I’d postponed fixing for years. I joined a local walking group and made friends who knew me as Walter, not as the man who could cover an unexpected bill.
On a bright Saturday morning, Michael visited my house with the children.
Emily ran through the front door and hugged me.
“Grandpa! Dad says you’re going to teach us fishing!”
“I certainly am.”
While the children explored the backyard, Michael stood beside me on the porch.
“I’ve been thinking about what you said,” he told me. “About helping us build our lives.”
I waited.
“I treated your money like something I was entitled to. I told myself it was for the kids, but I never asked what it was costing you.”
His apology sounded different this time. There was no demand hidden inside it, no request for another payment.
“I can’t promise I’ll never need help again,” he continued. “But I can promise I’ll ask honestly instead of assuming you’ll fix everything.”
I nodded.
“That’s a good place to start.”
He glanced at the house.
“Do you miss working?”
“Sometimes,” I admitted. “I miss the people. I miss feeling useful. But I don’t miss waking up tired before the day even begins.”
“And you don’t regret retiring?”
I looked toward the backyard, where Emily was trying to convince her younger brother that a garden hose could catch fish.
“Not for a single day.”
That evening, after they left, I checked my phone.
There were no frantic messages. No demands. No missed calls from someone expecting me to solve a financial emergency.
Just a photograph Michael had sent of the children smiling on my porch.
Underneath it, he had written: Thanks for having us over, Dad. We’re working on things.
I put the phone down and stepped outside.
The sun was setting, the neighborhood was quiet, and tomorrow held no obligations I hadn’t chosen for myself.
For forty-two years, I’d believed that being a good father meant providing until there was nothing left to give.
Now I understood something Susan had tried to teach me long ago: loving your family doesn’t mean surrendering your entire life to their expectations.
My son had told me I could work three more years because his family still needed my paycheck.
He hadn’t asked whether I needed my own life back.
So I gave myself permission to stop waiting for someone else to ask.
And at sixty-seven, I finally began the retirement I’d earned.