Before my husband Bradley came home Friday, I changed my laptop password and locked away the documents protecting the $118,000 I’d lent his mother. Someone had forged my signature to erase her debt. Then she called him—and revealed there was another account I wasn’t supposed to find.
“Give me the password, Natalie. Now.”
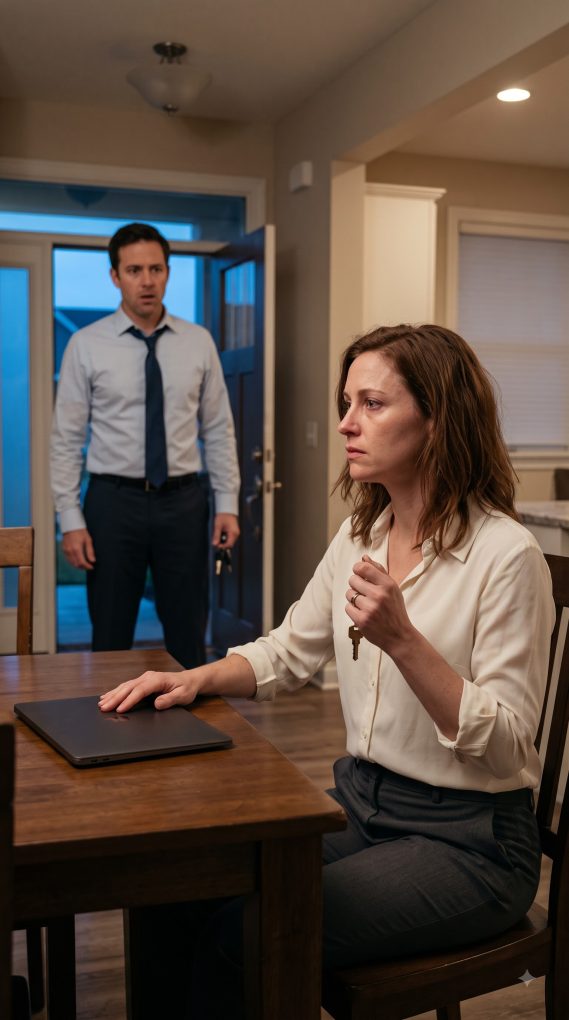
Bradley stood over my laptop, still wearing his work jacket. By the time he arrived home that Friday, I had changed the password and placed every document related to his mother’s house inside a bank safe-deposit box.
“Why?” I asked.
“Mom needs her paperwork.”
“Her paperwork, or the mortgage release someone signed with my name?”
His hand stopped on the keyboard.
Eight months earlier, I had lent his mother, Evelyn, $118,000 to save her house from foreclosure. It was most of the money my father had left me. My attorney insisted on a signed loan agreement and a recorded mortgage securing repayment.
Bradley called that insulting.
This morning, a title company emailed me to confirm that I had agreed to release my claim before Evelyn’s house sold on Monday.
Attached was my signature.
I hadn’t signed anything.
“Where are the originals?” Bradley asked.
“Somewhere you can’t reach them.”
He shut the laptop hard enough to make me flinch.
“You’re going to ruin everything over a technicality?”
“Someone forged my signature.”
“Keep your voice down.”
We were alone. That frightened me more than the shouting would have.
Then his phone rang.
Mom.
He answered before I could move away. Her voice came through the speaker, sharp and impatient.
“Did you get into her laptop?”
Bradley stared at me.
“No.”
A silence followed.
Then Evelyn said something that made the room seem to tilt.
“Bradley, you promised she wouldn’t find the other account.”
I reached for my phone.
He stepped in front of the door.
Until that moment, I thought I was protecting the last thing my father had left me. Watching Bradley guard the doorway, I understood there was something else they needed me to lose before Monday. The rest of what happened is in the comments.I finished the story in the comments.Next part is under this post..
“Move,” I said.
Bradley held up both hands.
“Nobody’s stopping you.”
“Then step away from the door.”
He moved just enough for me to pass. I took my purse and walked outside before calling my attorney, Rebecca Sloan.
“Don’t confront them again,” she said. “The title company has flagged the release. Your mortgage won’t simply disappear because somebody emailed a document.”
“What about another account?”
“Check your credit reports from somewhere secure.”
I drove to my friend Jess’s apartment. On her computer, I found a personal loan opened in my name eleven weeks earlier.
Eighty-six thousand dollars.
The application listed my income, my Social Security number, and an email address almost identical to mine. One extra letter. The payments had been made on time.
I stared until the numbers blurred.
Bradley had access to all of it. We had filed taxes together. He knew where I kept my identification.
But the bank statement I requested showed where the loan proceeds went.
Evelyn.
I called her.
“Tell me the account isn’t yours.”
She didn’t ask which account.
“Come over. We should discuss this without Bradley.”
I went with Jess, who waited in the car. I stayed on Evelyn’s porch.
She opened the door wearing the pearl earrings I had bought her for Christmas.
“Marriage requires flexibility, Natalie.”
“Did you receive eighty-six thousand dollars borrowed in my name?”
“Bradley said you would help.”
“That isn’t what I asked.”
Her expression hardened.
“You have money sitting around. My son works himself sick.”
“My father died for that money to be sitting around.”
She looked past me toward Jess’s car.
Then she sighed.
“I told him to use your information. He was taking too long to find another solution.”
For a moment, I couldn’t hear the traffic behind me.
“You told him?”
“Someone had to handle things.”
The foreclosure. The frantic hospital calls. The story about medical bills swallowing her savings.
“How much of what you told me was true?”
“The house was in foreclosure.”
“And the medical bills?”
She folded her arms.
I remembered Bradley refusing to let me review the statements. Mom was embarrassed, he’d said. Why did I always need proof?
Now I understood why.
“You’re selling the house,” I said. “You could repay everything.”
“I need somewhere to live.”
“So do I.”
“You’re young. You can recover.”
I walked back to the car before she could see my hands shaking.
Rebecca met us at her office Saturday morning. She had already received my credit report and the disputed release.
Then my phone rang.
A police officer wanted to speak with me about money allegedly taken from Evelyn’s savings.
“She says she entrusted you with managing her finances,” he explained.
Rebecca put the call on speaker.
An email arrived while he was talking.
Evelyn had sent a scanned authorization bearing my signature.
Beneath it was a message.
If you make Bradley a criminal, I’ll make sure you go down with him.
Rebecca read it once.
“Save that,” she said.
What do you think will happen next? I’d love to hear your honest guess or reaction “I’d love to hear your opinions – your comments really make me happy and inspire me to keep writing.”
“Don’t answer her,” Rebecca said. “We’re going to answer with records.”
She told the officer I disputed Evelyn’s allegation and would provide documents through counsel. Then she asked him for a case number.
Hearing those ordinary questions steadied me.
Until then, everything had felt like Bradley’s doorway. A small space where someone else decided whether I could leave.
Now there was a process. There were people who would ask for dates.
“What if they believe her?” I asked.
“Then we give them something they can verify.”
On Monday morning, I retrieved the documents from my safe-deposit box. Rebecca met me at the bank.
Inside the folder were the loan agreement, the recorded mortgage, and the closing statement from the transaction that had stopped Evelyn’s foreclosure. My money had gone directly through the closing attorney to satisfy her overdue mortgage debt.
It had never passed through Evelyn’s savings account.
Rebecca also requested the underlying bank records for Evelyn’s accusation.
The supposed authorization concerned an account I had never controlled. The transfer Evelyn claimed I had stolen was money she had moved herself, months before I lent her anything.
Her complaint relied on a signature pasted onto a document dated before I supposedly received access.
The bank’s records did not support her story.
That didn’t make everything disappear in an afternoon. The officer asked more questions. I gave a statement. Rebecca organized the records and kept copies of every message.
Meanwhile, the house sale stopped.
The buyer’s title company would not proceed while the mortgage release was disputed. Evelyn could sell her house, Rebecca explained, but she could not simply erase the debt secured against it.
Bradley called fourteen times that Monday.
I answered the fifteenth with Rebecca beside me.
“You’ve made your point,” he said. “Tell them you signed the release.”
“No.”
“The buyer might walk.”
“Then your mother can find another buyer.”
“You don’t understand what happens if she doesn’t get this money.”
“Explain it.”
For once, he did.
Evelyn had been gambling for nearly three years. Credit cards first. Then cash advances. Then the mortgage payments she stopped making.
The medical emergency had been a story Bradley helped build because he knew I would ask fewer questions if I thought she was sick.
“And the loan in my name?”
“She said we’d pay it back after the sale.”
“After paying me back?”
Silence.
“You were never going to repay my father’s money.”
“We were going to explain.”
“You had eight months.”
His voice broke.
“She’s my mother.”
“I was your wife.”
I ended the call.
That evening, Bradley came to Jess’s apartment carrying flowers.
Jess answered through the locked door.
“She doesn’t want to see you.”
“I’m trying to save my marriage.”
“Then listen to what she’s telling you.”
He left the flowers in the hallway. Jess gave them to a neighbor.
I filed for divorce that week.
There were practical things to handle before I could feel much of anything. I froze my credit, opened an account in my name alone, and reported the fraudulent loan to the lender. Rebecca helped me gather what its fraud department requested.
I also stopped answering questions that were really instructions.
Couldn’t I wait before reporting Bradley?
Wouldn’t I rather settle quietly?
Did I understand what this would do to his mother?
Every question ended at the same place: I should absorb the loss so they could keep their lives.
The lender’s investigation took months. Its records showed the false email address, the account that received the proceeds, and communications connected to Bradley. Eventually, it confirmed in writing that I would not be held responsible for the fraudulent loan.
I read that letter three times.
Then I cried in my parked car.
Evelyn’s house sold later that fall. With my mortgage still recorded, the closing attorney paid the outstanding loan principal and agreed interest from the proceeds.
There was enough left for Evelyn to rent an apartment. There was no windfall.
The criminal investigation continued separately. Bradley ultimately admitted his role in the loan application and forged release. Evelyn’s messages and financial records made it difficult for her to maintain that she had known nothing.
Both faced consequences through the courts. I stopped following every development once my attorney said my involvement was no longer needed.
I wanted my days back.
At our final divorce mediation, Bradley looked thinner. He kept turning his wedding ring around his finger.
“I should have protected you,” he said.
“Yes.”
“I thought I could fix it before you found out.”
I looked at him across the table.
“You could have told me your mother was in trouble. You could have let me decide whether to help.”
He nodded, but I wasn’t sure he understood the difference yet.
Months later, I used part of the recovered money for a down payment on a small townhouse. On moving day, Jess helped me carry my father’s old dining table through the front door.
One leg caught against the frame. We laughed, adjusted our grip, and tried again.
That night, I sat at it with takeout and my laptop.
My phone lit up with a message from Bradley.
I hope someday you can forgive us.
I set it facedown.
Then I opened a folder containing my mortgage papers, my bank statements, and the letter clearing the fraudulent debt.
For the first time in almost a year, looking at my own name on a document didn’t frighten me.
I closed the laptop and finished dinner.