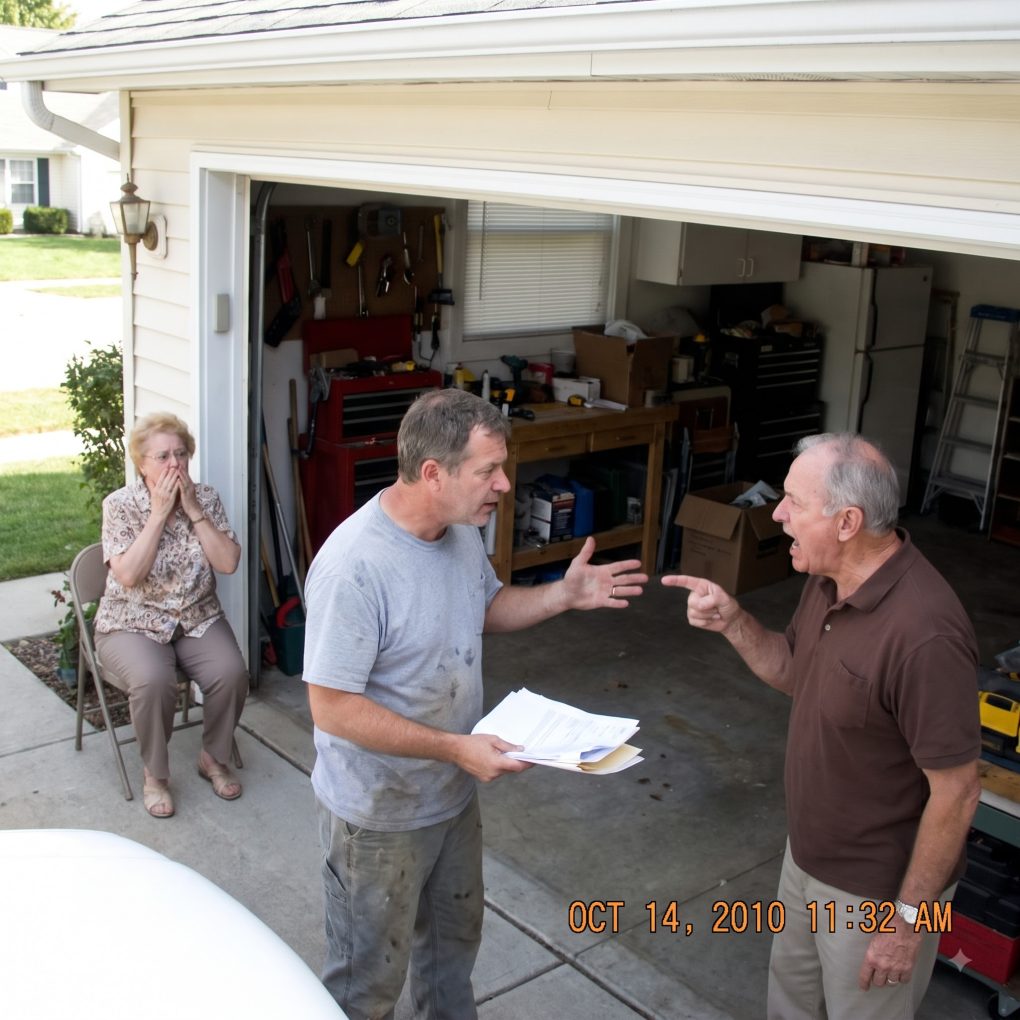
I was repairing my parents’ garage door when a folder slipped from the storage shelf above my father’s workbench. Inside was his estate plan. The house, the lakefront property, and nearly three million dollars were going to my younger brother. My inheritance was exactly one dollar. Before I could turn another page, Dad stormed into the garage and screamed for me to put everything back.
My name is Daniel Whitaker, and I’m forty-two years old. I own a small electrical contracting business outside Madison, Wisconsin. For fifteen years, I’d been the person my parents called whenever something broke, a bill needed explaining, or an emergency required immediate help.
My brother, Ryan, was thirty-seven and lived in Milwaukee. He worked in commercial real estate, drove expensive cars, and visited our parents mostly on holidays. Dad constantly praised his ambition while describing my electrical business as ordinary work that would never amount to much.
The documents were dated six weeks earlier. Dad had signed a will and created a revocable trust directing most of his assets to Ryan. The one-dollar provision was deliberate, and a separate letter explained that Ryan deserved the family wealth because he understood investments.
Dad snatched the folder from my hands. He accused me of snooping, although the papers had fallen while I was moving tools to repair the garage mechanism. I asked whether Mom knew about the arrangement. He refused to answer and ordered me to finish the repair.
I looked at the broken garage door, then at the man who’d spent years expecting free labor from me. I told him I wouldn’t continue working. He shouted that family members helped each other without calculating what they received in return. I agreed, then asked why that principle apparently applied only to me.
Dad said Ryan had greater responsibilities and would preserve the family legacy. I reminded him that I’d helped maintain the house and lake property for years without payment. He dismissed those contributions as chores any decent son would perform. Something inside me finally hardened.
I reached into my wallet and placed a one-dollar bill on the dashboard of Dad’s pickup truck. I told him he’d already decided what my place in the family was worth. Then I gathered my tools, walked past him, and drove home without looking back.
For the next three months, I ignored requests to fix appliances, maintain the lake cabin, and review household bills. I answered Mom’s occasional calls but refused to discuss Dad’s estate. I focused on my business, my wife, and our teenage daughter instead.
Then, one Tuesday morning, my phone began ringing continuously. Ryan called seven times, Mom left four frantic messages, and Dad sent a text demanding that I come immediately. The final voicemail came from a bank officer. He said my father had used my company’s name on documents involving a $680,000 loan.
I returned the bank officer’s call before contacting my family. He explained that Ryan’s development company had applied for financing to renovate the lake property. The application included a contractor commitment letter naming my electrical business as the firm responsible for major infrastructure work.
I’d never agreed to the project. The letter contained my company’s logo and an electronic signature resembling mine, but the document wasn’t authentic. I asked the officer to send me a copy and immediately contacted my business attorney, Rebecca Hayes.
Rebecca reviewed the paperwork and advised me to dispute the authorization in writing. We notified the bank that my company had neither approved the project nor signed the commitment. The bank suspended its review while investigating the conflicting information. No funds had been disbursed.
Only then did I call Dad. He answered angrily, accusing me of humiliating Ryan and jeopardizing a profitable investment. I asked why my business had appeared on financing documents without permission. Dad went silent before admitting that Ryan had prepared the paperwork.
The plan was worse than I’d imagined. Ryan wanted to renovate the lake property into a luxury vacation rental complex. Dad had agreed to let Ryan use the land as collateral, believing the investment would multiply the family’s wealth. They needed an established contractor to make their construction budget credible.
Ryan had chosen my company because he knew our licensing history and reputation. He claimed he’d intended to hire me eventually and that the signature was merely preliminary. I reminded him that my consent wasn’t something he could assume. He accused me of destroying his future over a technicality.
Mom called that evening, crying. She said she’d discovered the loan application only after the bank contacted Dad. She also revealed that Ryan had already paid a nonrefundable deposit to an architectural firm and promised several contractors that financing was imminent.
I asked Mom whether she’d known about the inheritance arrangement. She admitted Dad had discussed leaving Ryan the lake property but insisted she hadn’t understood the full estate plan. The house was jointly owned, and some accounts were hers, so Dad’s documents couldn’t simply dispose of everything.
Rebecca advised me to preserve all correspondence and avoid negotiating directly with Ryan. The bank’s investigators requested business records to compare signatures and verify the disputed commitment. I cooperated through my attorney while continuing normal operations at my company.
A week later, Mom arrived at my office carrying another folder. She’d obtained copies of documents Ryan had persuaded Dad to sign. Among them was a proposed mortgage against the lake property and a separate agreement promising Ryan control of future rental income. Then she showed me a transfer record revealing that Dad had already given Ryan $240,000.
The $240,000 had come from an investment account Dad controlled individually. Ryan had described the transfer as startup capital for the development project. Mom was furious because Dad had repeatedly told her their retirement savings were secure. She now feared he was risking their financial stability to support Ryan’s ambitions.
I told Mom I would help her understand the paperwork, but I wouldn’t become responsible for Ryan’s business decisions. Rebecca recommended that Mom consult an independent estate attorney and financial adviser. She arranged those appointments herself, and I attended only when she asked me to accompany her.
The advisers confirmed that Dad could generally control assets held solely in his name, subject to applicable legal obligations. They also explained that Mom’s ownership interests and marital rights required separate consideration. She began reviewing account statements, property titles, and beneficiary designations before making any decisions.
Meanwhile, the bank concluded that my company hadn’t authorized the contractor commitment. It rejected Ryan’s financing application and referred the questionable documents for further review. I filed a formal report regarding the unauthorized use of my business identity, protecting my company from potential contractual disputes.
Without the loan, Ryan couldn’t proceed with the development. He lost the architectural deposit and struggled to repay several personal advances. Dad initially blamed me, insisting that family loyalty should have mattered more than paperwork. I told him loyalty didn’t require accepting forged authorization or risking my employees’ livelihoods.
Three weeks later, Dad requested a meeting at my office. He arrived without Ryan and looked older than I remembered. For the first time, he admitted that he’d treated my work as less valuable because it didn’t sound impressive at dinner parties. He apologized for using my generosity while overlooking my contributions.
Then he offered to revise his estate plan and divide everything equally. I told him that his money was his decision, provided he respected Mom’s rights and made arrangements lawfully. What I wanted wasn’t a larger inheritance. I wanted him to stop treating me as an unpaid employee whose loyalty could be demanded indefinitely.
Mom eventually persuaded Dad to meet with independent legal and financial professionals. After reviewing their assets, they revised their estate documents to reflect both their wishes and ownership rights. Dad also established a separate budget for property maintenance instead of expecting me to handle every repair without compensation.
Ryan moved into a smaller apartment and accepted a position with an established development firm. We didn’t become close overnight, but he eventually acknowledged that he’d crossed a serious line by using my company’s identity. I agreed to remain civil while making clear that future business discussions would require written agreements.
Six months after the garage incident, Dad invited me to the lake property. I brought my daughter, and we spent the afternoon fishing instead of fixing something. Before we left, he handed me the same one-dollar bill I’d placed on his dashboard. He said he’d kept it because it reminded him of the day he nearly lost his older son. I accepted it without pretending everything had been repaired. Trust would take longer than an afternoon beside the water. But when my daughter asked why Grandpa had given me a dollar, I told her it was a reminder that money couldn’t measure someone’s worth. For years, I’d confused being needed with being appreciated. Walking away had finally taught my family the difference, and it had taught me something even more important: I could love them without allowing them to use me.