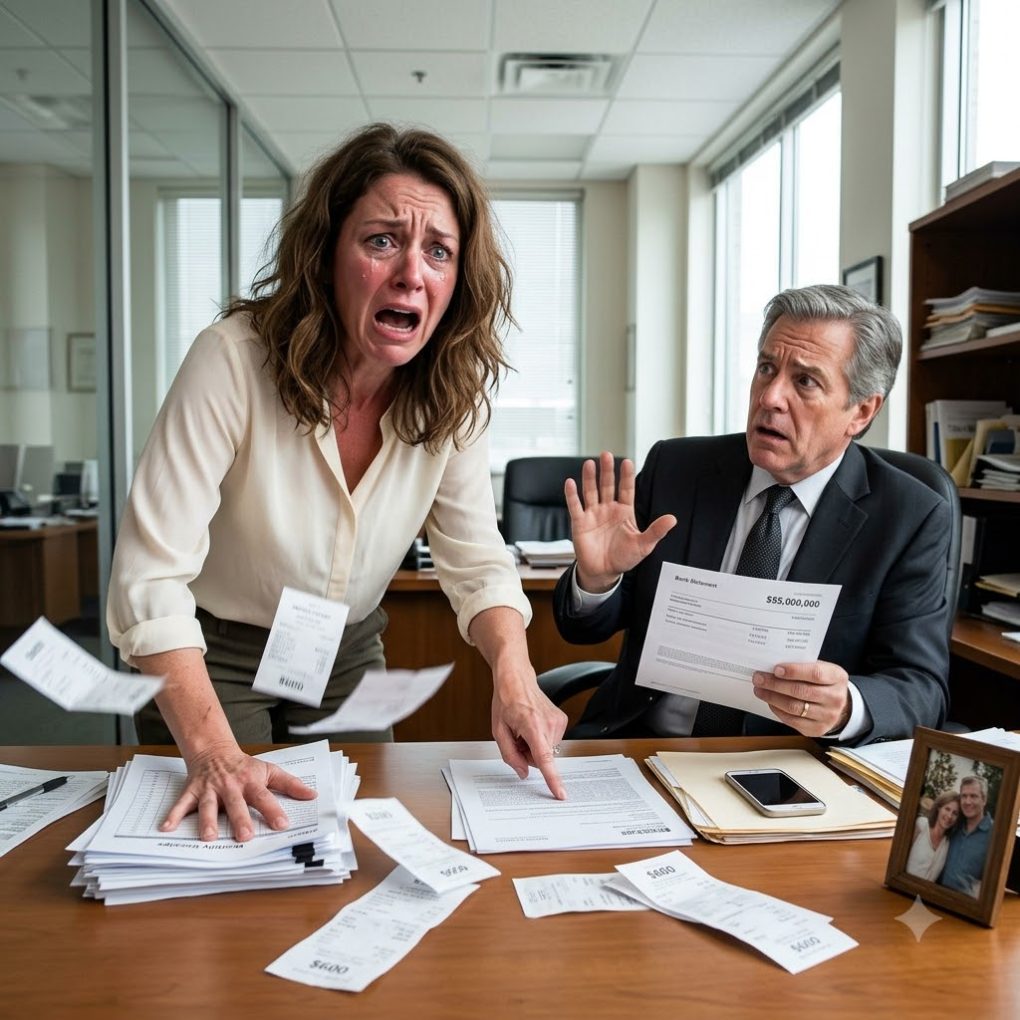
After my husband died, I was told he’d left me nothing but debts. Every month, I faithfully transferred $600 to pay off his loan, struggling to keep up with the payments. But one day, the bank called with shocking news. “Ma’am, your husband left you $55 million. He never had any debts!” I nearly dropped my phone. Then I asked the bank manager who had been receiving my money, and his answer left me speechless…
“Ma’am, your husband left you $55 million. He never had any debts.”
I nearly dropped my phone.
“That’s impossible,” I whispered. “I’ve been paying his loan for sixteen months!”
The bank manager went silent.
Then he asked, “Mrs. Morgan, who told you your husband owed money?”
I stared at the $600 payment reminder sitting on my kitchen table.
“My brother-in-law.”
My name is Claire Morgan. I’m forty-two years old, and my husband, Andrew, died in a car accident sixteen months ago.
After his funeral, his older brother, Garrett, arrived with a folder of financial documents.
He claimed Andrew had borrowed money from a private lending company and left an outstanding debt.
“Don’t worry about the paperwork,” Garrett told me. “Just send $600 every month. Andrew would want you to honor his obligations.”
So I did.
Every month, I transferred $600, even when I could barely afford groceries.
I sold my wedding jewelry, canceled my health club membership, and took extra shifts at the accounting office.
I thought I was protecting my husband’s memory.
Now the bank was telling me everything had been a lie.
“Mrs. Morgan,” the manager continued, “I’m Robert Ellis. Our trust department has completed the distribution review of your husband’s investment holdings. Your husband owned shares in a technology company that was recently acquired.”
I couldn’t speak.
“After the sale and applicable deductions, your inheritance is $55 million.”
“But Garrett said Andrew was bankrupt!”
“Our records show no outstanding debts against the estate.”
My chest tightened.
“Then who has been receiving my payments?”
Robert asked me to confirm the account I’d been transferring money to.
After reviewing the transaction details, he spoke carefully.
“The recipient is Ridgeway Capital Services.”
I swallowed.
“And who owns it?”
“The company’s publicly registered director is Garrett Morgan.”
My husband’s brother.
The man who hugged me at the funeral.
The man who watched me sell my wedding ring while collecting $600 every month.
I gripped the edge of my table.
Robert urged me to preserve my payment records and speak with an attorney before confronting anyone.
Then my phone vibrated.
Garrett.
I ignored it.
A text appeared seconds later.
“Claire, don’t forget this month’s payment. Andrew wouldn’t want you falling behind.”
I stared at those words, trembling.
Then another message arrived.
“Also, I heard someone from the bank contacted you. Don’t discuss Andrew’s finances without me.”
My blood turned cold.
How did Garrett know?
And why was he so terrified of me speaking to the bank alone?
I spent the next hour sitting at my kitchen table, staring at Garrett’s messages. Sixteen months. Sixteen payments of $600. That was $9,600 I’d handed over while struggling to survive. Worse, Garrett had watched me cry over overdue electricity bills and never once suggested that I stop paying.
I called Robert back and asked how Garrett could have learned about the bank’s investigation. Robert explained that Garrett’s name appeared as an old emergency contact in Andrew’s business records. During the effort to locate me, someone from the trust administration team had contacted him for updated information. “He was not authorized to receive financial details,” Robert assured me. “But he knew we were trying to reach you.” Suddenly, everything made sense. Garrett hadn’t been reminding me about the payment out of concern. He was afraid his deception was ending.
That afternoon, I met with an attorney named Rebecca Lawson. I brought every bank statement, every text message, and every payment confirmation. Rebecca studied the documents carefully. “Claire, were you ever shown an original loan agreement signed by Andrew?” I shook my head. “Garrett gave me photocopies. He said the originals were with the lender.” She pointed to the account details. “These payments went directly to a company controlled by Garrett. That doesn’t prove the loan was legitimate.” Then she asked a question that made my stomach tighten. “Why did you believe you personally had to repay your husband’s individual debt?” I whispered, “Because Garrett told me I’d lose our house if I didn’t.”
Rebecca explained that a deceased person’s debts are generally handled through the estate and that a surviving spouse isn’t automatically responsible for every loan. She instructed me not to send another payment while she investigated. For the first time since Andrew’s death, I felt a little less helpless.
Two days later, the bank’s trust department provided the documents confirming my inheritance. Andrew had helped develop software for freight companies years before we married. I’d known about the business, but he’d always described his ownership stake as something that might never be worth much. After his death, a larger corporation acquired the company, turning those shares into an extraordinary fortune. The trust documents named me as the beneficiary. The distribution review had taken months because of the acquisition, tax calculations, and legal verification.
But there was something else.
Inside the trust file was a letter Andrew had written shortly before our tenth wedding anniversary.
“Claire, if anything happens to me, I want you to know that I have always tried to keep you protected. My shares may someday become valuable. I hope they give you security, but never let money make you dependent on someone who doesn’t respect you.”
I pressed the letter against my chest and cried. My husband had never been wealthy in the way people imagined. We drove ordinary cars, lived in a modest house, and saved wherever possible. But he’d quietly preserved something that could now change my entire future.
That evening, Garrett arrived unexpectedly. He wore an expensive coat and carried a leather briefcase. “Claire, we need to discuss your inheritance,” he announced. I kept the front door partly closed. “How much do you know about it?” He smiled. “Enough to realize you need experienced family guidance.” Then he handed me a document.
At the top were the words “Acknowledgment of Outstanding Family Loan.”
The supposed remaining balance was $780,000.
I nearly laughed. “You told me Andrew owed a small private loan. Now you’re claiming almost eight hundred thousand dollars?” Garrett’s expression hardened. “Interest and penalties accumulated. I was trying to spare you the details.” I stared at him. “By collecting $600 from me every month?” He stepped closer. “Your husband made promises, Claire. Don’t disgrace him by refusing to honor them.”
I thought about the wedding ring I’d sold for $2,100. I thought about the extra shifts, the sleepless nights, and the countless times I’d apologized to Garrett for being late with a payment.
Then I asked, “Why does the receiving account belong to your company?”
His smile disappeared.
“Who told you that?”
“The bank.”
Garrett slammed the briefcase onto my hallway table. “You have no idea what Andrew owed me! I helped him when nobody else would!”
I looked directly at him.
“Then you won’t mind proving it to my attorney.”
His face went pale.
“You hired a lawyer?”
“Yes. And she has copies of everything.”
Garrett grabbed his briefcase and stormed away.
Ten minutes later, Rebecca called.
“Claire, I’ve compared the supposed loan documents with Andrew’s business records.”
Her voice was unusually serious.
“There’s something you need to see. The signature Garrett claims belongs to your husband appears on a document dated six months after Andrew died.”
For a moment, I couldn’t breathe.
Garrett hadn’t just lied about a debt.
He’d apparently been creating paperwork in a dead man’s name.
I stared at the document Rebecca had emailed me. There it was, in black and white: Andrew’s supposed signature beneath a date six months after his funeral. My hands trembled as I compared it with the death certificate lying beside my computer. Garrett had spent sixteen months convincing me I was honoring my husband’s memory. Now I had evidence that at least one document supporting his story could not possibly be genuine.
Rebecca told me not to confront Garrett again. Instead, she prepared a formal written demand for the original loan records, a complete accounting of every payment, and an explanation of how Andrew’s signature appeared on a document created after his death. She also advised me to preserve all messages and provide the evidence to the appropriate investigators. I followed her instructions. For once, I wasn’t going to let Garrett frighten me into making another decision.
Three days later, Garrett called. I let it go to voicemail. “Claire, you’ve misunderstood everything,” he said. “That signature was copied onto an updated form by my office. It doesn’t mean the loan wasn’t real. We can settle this privately if you stop involving lawyers.” I saved the recording. An hour later, another message arrived. “I can forgive the remaining balance if you agree not to pursue this.” I read it twice. The man who’d demanded $780,000 was suddenly offering to forget the debt entirely.
Rebecca arranged a meeting at her office to discuss his claims. Garrett arrived wearing the same expensive coat he’d worn at my house. He looked confident until he noticed the original payment records spread across the conference table. Rebecca asked him to identify the lender and explain the money’s movement. Garrett insisted Andrew had borrowed the funds for business expenses. “Where is the signed original agreement?” she asked. He said it had been misplaced. “And why does this later document bear Andrew’s signature six months after his death?” Garrett shifted in his chair. “Administrative error.” Rebecca slid another page toward him. “Then please explain why the receiving account was opened by your company shortly after your brother died.”
Garrett’s face turned red. “I don’t have to answer these ridiculous questions!” He stood so abruptly that his chair scraped across the floor. I remained seated. “You watched me sell my wedding ring,” I said quietly. He froze. “You knew I was struggling. You knew I was taking extra shifts. And every month, you reminded me that Andrew would be disappointed if I missed a payment.” Garrett looked away. I continued, “You weren’t collecting a debt. You were using my grief to control me.”
For the first time, he had nothing to say.
Rebecca ended the meeting when Garrett refused to provide supporting documentation. She told him future communication would go through counsel. As he approached the door, Garrett turned toward me. “Claire, don’t forget that Andrew and I were brothers.” I looked him straight in the eye. “Then you should have treated his wife like family.”
Over the following weeks, the investigation into the suspicious documents continued. My bank supplied records of the sixteen monthly transfers, and Rebecca submitted the questionable loan papers and Garrett’s messages for review. Garrett eventually retained his own attorney. Through negotiations handled by our lawyers, his company returned the full $9,600 I’d paid, without my agreeing that any debt had existed. The potential legal consequences of the documents remained a separate matter. I wanted the authorities to determine what had happened based on evidence, not my anger.
Meanwhile, the bank completed the remaining security and identity checks on Andrew’s trust distribution. I sat in Robert Ellis’s office when he handed me the final confirmation. The inheritance, totaling $55 million, was mine. I didn’t scream or celebrate. I simply stared at the figures, remembering the nights I’d worried about buying groceries. Robert asked whether I needed a moment. I nodded. Then I began crying.
That evening, I went home and opened the wooden box where I kept Andrew’s photographs. There was one from our wedding day, another from a camping trip, and a picture of him laughing while trying to repair our old kitchen faucet. He had never cared much about appearances. Even when his company began succeeding, he wore the same faded jackets and insisted that a good life wasn’t measured by expensive possessions.
I wished he had told me more about the trust. I wished we’d discussed what might happen if his investment became valuable. Most of all, I wished he’d lived long enough to enjoy the future he’d helped build. But I knew one thing: he would have been heartbroken to learn that his brother had used his death to take advantage of me.
With professional advice, I arranged for the inheritance to be managed carefully. I paid off my mortgage, created an emergency fund, and established long-term investments. I didn’t buy a mansion or a fleet of cars. I wanted security, not attention. I also decided to create a small educational foundation in Andrew’s memory, supporting students from families facing financial hardship. It felt like something he would have appreciated.
Two months later, I received a letter from Garrett. He wrote that he’d been under financial pressure and had convinced himself I owed him something because Andrew’s success had surpassed his own. He admitted he’d taken advantage of my trust, though his letter still avoided fully explaining the forged paperwork. He asked me to forgive him for the sake of the family.
I placed the letter in a drawer. Forgiveness was something I might consider someday, but reconciliation required honesty and accountability. I wasn’t ready to welcome him back into my life.
On the anniversary of Andrew’s death, I visited his grave with white roses. I knelt beside the headstone and whispered, “You left me more than I ever imagined, sweetheart.” Tears rolled down my cheeks. “But I would give every dollar back for one more ordinary evening with you.”
When I returned home, I found the final payment reminder Garrett had sent before the truth came out. It read, “Don’t forget the $600. Andrew would want you to do the right thing.”
I deleted it.
For sixteen months, I’d believed being a good wife meant repaying a debt my husband had supposedly left behind. I’d sacrificed my savings and my peace of mind because someone knew exactly how to exploit my love for him.
Then one phone call changed everything.
“Ma’am, your husband left you $55 million. He never had any debts.”
I’d thought the most shocking part was the inheritance.
I was wrong.
The real shock was discovering that the person who kept demanding money in my husband’s name was the very person betraying his memory.
Andrew had left me financial security.
Garrett had tried to leave me with fear.
And for the first time since losing my husband, I was finally free of both the imaginary debt and the man who created it.