“You’ll never measure up to your brother.”
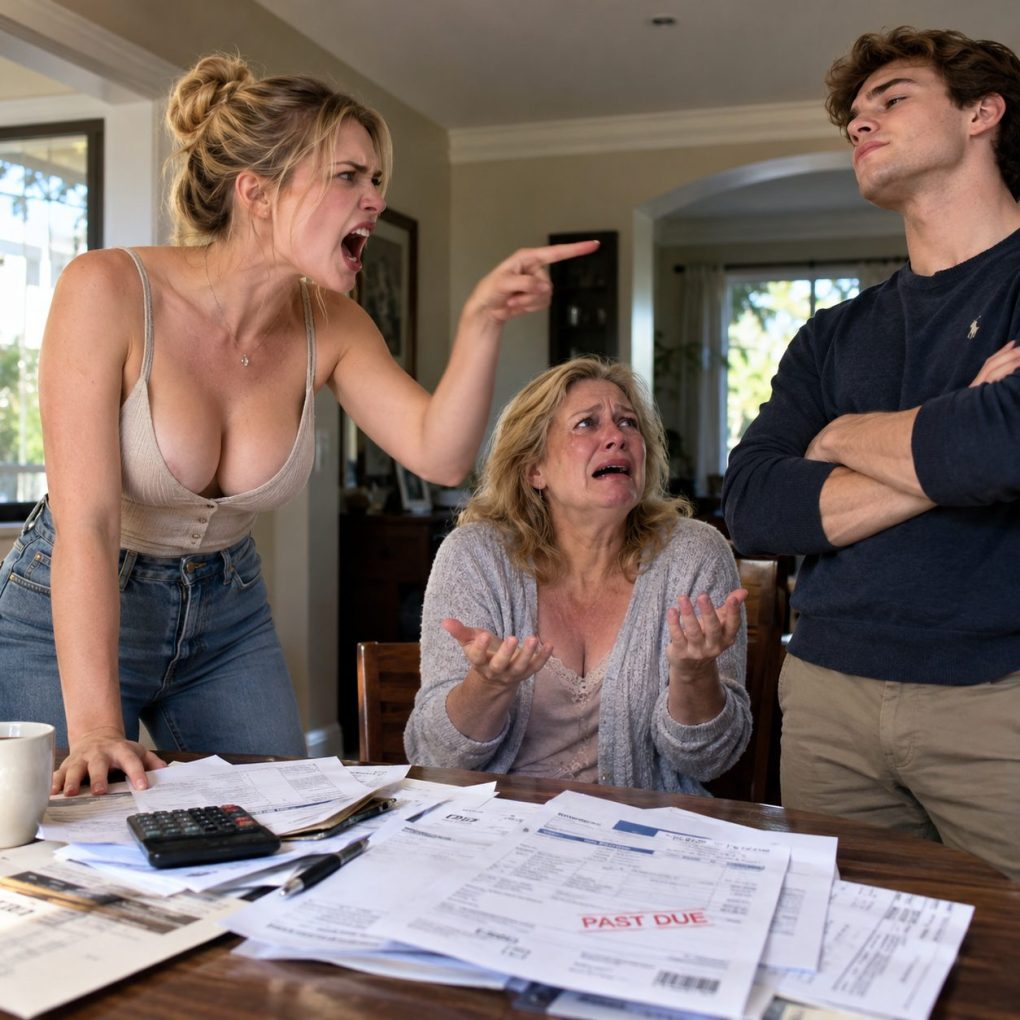
Dad said it as I reached for my purse. Mark leaned back, smiling, while Mom stared at her plate.
I stood.
“Then let him cover every bill.”
Mom’s face drained. “What money?”
My hand froze on the chair.
“The eighteen hundred I send Dad each month. For this house.”
Nobody moved.
Then Mark set his glass down too hard.
“Laura,” Dad said. “Sit.”
“For twenty-six months,” I added.
Mom looked at him. “You said Mark was paying that.”
“Diane, please.”
“You said Laura kept asking you for rent money.”
I had been working weekends to keep their lights on.
Across the table, my brother looked away.
“Tell her,” I said.
Dad rose so fast his chair struck the wall.
“We are not doing this here.”
“Where should we do it? At my second job?”
Mom pushed her plate aside. Her hands shook as she reached for my phone.
“Show me.”
Dad caught her wrist.
I stepped between them.
“Let go.”
He did, but his eyes stayed on me as I opened my bank app.
Mom scrolled through the transfers. Each had the same note: House bills.
“This is your account?” she asked Dad.
He said nothing.
She looked at Mark.
“You let me thank you.”
“I helped too.”
“With what?” I asked.
His mouth opened. Nothing came out.
Mom stood and walked to the kitchen drawer.
Dad blocked her path.
“Those are old papers.”
She slipped past him and pulled out an envelope.
“I found this yesterday. He said the bank made a mistake.”
The red words showed through the window.
NOTICE OF DEFAULT.
I stared at Dad.
“You said the mortgage was paid off.”
“It is,” Mom whispered.
She unfolded the page, read the first line, and gripped the counter.
“Frank. When did I borrow sixty-five thousand dollars?”
Dad reached for the paper.
Mark grabbed his arm.
“Don’t,” he said. “She hasn’t seen the signature yet.”
My brother knew what was on that page before Mom turned it over. Suddenly, the money I had sent wasn’t the only thing I needed explained. I watched his hand tighten around Dad’s arm.
Mom turned the page. Her name sat beneath a signature that almost looked like hers. Almost. “I didn’t sign this.” Dad pulled out a chair. “You don’t remember everything you sign.”
“Don’t talk to her like that,” I said. Mark released his arm and backed toward the hall. “Where are you going?” “To get the folder.” Dad’s expression changed. For the first time that night, he looked afraid.
Mark returned with a blue binder. Dad reached for it, but Mom took it first. Inside were loan statements, inventory receipts, and paperwork for a business called Miller Resale. Dad and Mark were both listed as owners.
I recognized the address. Mark had called it his warehouse, the proof he was finally doing better than everyone else. “You used the house to start his business?” “It was an investment,” Dad said.
Mom kept turning pages. “And Laura’s money?” “We had expenses.” I found a transaction sheet tucked behind a receipt. My monthly deposits landed in Dad’s account. Transfers to the business followed.
“How much of this went toward their bills?” I asked Mark. He stared at the floor. “Some.” Mom made a small sound, as if someone had pressed a thumb into a bruise.
“You told me she was taking from us.” Dad spread his hands. “You were worried about her. I didn’t want you asking questions.” “So you made me ashamed of my daughter?” He tried to touch her shoulder. She stepped away.
I photographed the papers. Dad watched every movement. “You send those outside this family, you’ll destroy your brother.” “His name isn’t on that house,” Mom said. “Mine is.”
The notice said four payments were overdue. Dad had been intercepting the mail, promising Mark that one good inventory sale would catch them up. Mom reached for her phone.
Dad stood in front of the kitchen doorway. “Think before you call the bank.” I moved beside her. “Move.” For a moment, nobody spoke. Then Mark opened the back door. “Let them leave, Dad.”
We drove to my apartment with the binder between Mom’s feet. She cried without making a sound. At nine the next morning, we sat across from a bank representative. Mom disputed the signature and requested the underlying documents.
The representative recorded her complaint and explained that the investigation would take time. It would not erase an overdue balance that morning. We left with reference numbers and an appointment with a local attorney, Ellen Brooks.
Ellen examined the photographs, then stopped at a page I had barely noticed. “Laura, did you guarantee a separate business credit line?” “No.” She turned the binder toward me. Forty thousand dollars. My name. My old address. “That isn’t my signature.”
My phone buzzed. Mark. I answered on speaker. “Did you find the guarantee?” he asked. Mom covered her mouth. “Who signed it?” I said. A door slammed on his end. Dad shouted something I couldn’t make out. Then Mark whispered, “Dad signed it. But I sent them your information.”
“What information?” I asked. Ellen held up a hand, asking me to slow down. Across her desk, Mom sat perfectly still. Mark was breathing hard. “Your Social Security number. Your pay stubs. Dad still had copies from when you applied for that apartment after college. He said you’d agreed to help.” I stared at the guarantee. “You could have called me.” His silence answered before he did. “I knew you might say no.”
Ellen wrote that down. “Mark, this is Attorney Ellen Brooks. Laura is here with me. Preserve the emails, messages, applications, and account records. Don’t delete or change anything.” Dad’s voice rose in the background. Mark said, “I have copies.” Then the call ended. I wanted to throw my phone. Instead, I set it on Ellen’s desk and asked what we needed to do first.
We spent that afternoon separating facts from guesses. Mom disputed the home equity loan in writing. I disputed the business guarantee with the other lender. We filed police reports and froze our credit. Ellen warned us that a report wasn’t a verdict, and neither lender would simply accept our account without reviewing the evidence. She helped Mom request a temporary pause on collection activity while the signature dispute was investigated.
The full application files arrived over the following weeks. The signature on Mom’s loan paperwork matched an old check, down to an odd stray mark beneath her last name. The electronic guarantee carried my name, but the contact phone number belonged to Dad. The business emails came from Mark. Each discovery made the dinner table feel farther away. This had not been one desperate decision made on a bad afternoon.
Mark eventually brought Ellen his laptop and signed a written account. Dad had proposed the resale business after losing his job. They borrowed against the house to buy pallets of returned appliances. Mark expected quick profits. Instead, repair costs and unsold stock swallowed the cash. Dad began using my monthly transfers to keep the warehouse open. When that failed, they sought another credit line. Mark submitted my records, then looked away when Dad supplied the signature.
“Why tell Mom I was borrowing from you?” I asked Dad at a meeting in Ellen’s office. It was the first time I had seen him since dinner. He looked older, but I refused to let that become an answer. “She kept saying we should ask you to dinner more,” he said. “She might have thanked you for helping. You might have compared notes.” There it was. He had turned my own mother against me to keep us from talking.
Mom leaned forward. “Every time I told her to grow up. Every time I told her to learn from Mark. You sat there.” Dad rubbed his face. “I thought I could fix it before anyone got hurt.” Mom shook her head. “You needed us quiet until the next payment.” He looked at me then. “Can you at least help us settle this?” For twenty-six months, that question had felt like an obligation. This time, I said, “No.”
The consequences moved slowly, through appointments and letters, not one triumphant phone call. The home lender reviewed the original closing file and the other evidence. Months later, its investigation confirmed Mom had not authorized the loan. Through counsel, she obtained a written resolution releasing her from the debt and clearing the lien. I read the recorded release twice before handing it to her. She pressed the paper against her chest.
The business lender also accepted my dispute after reviewing its application records and Mark’s statement. It removed me as guarantor and corrected the information it had reported about me. I kept every confirmation. Dad and Mark still owed the business debts. Their warehouse closed. Inventory and equipment were sold, and the proceeds went toward those obligations. They had called me unsuccessful while using my steady paycheck to prop up a business they would not admit was failing.
The criminal case took longer. Both eventually entered guilty pleas connected to the fraudulent applications. Their sentences included supervision and restitution. Ellen helped us understand which losses were covered and what would require a separate civil claim. I knew I might never recover every dollar I had sent willingly to Dad’s account. That hurt. But I stopped measuring the outcome by whether they could return enough money to make those two years disappear.
Mom chose to separate from Dad. She stayed with me while she arranged her finances, then returned to the house after the legal issues were settled. We made a budget together. For the first time, she saw her own statements and paid her own bills. One evening, she reached across my kitchen table. “I believed him because believing you would have meant admitting what he was doing.” Her eyes filled. “That doesn’t excuse me.” I held her hand. “No. It doesn’t.” We stayed there anyway.
Mark wrote three times before I answered. I told him any apology had to include what he had done, without blaming Dad. His next letter did. I thanked him for telling the truth and told him I still needed distance. Dad sent a shorter message: After everything, we’re still family. I put my phone down without replying. The next payday, my rent cleared, my savings grew, and eighteen hundred dollars stayed in my account. Nobody called to tell me I wasn’t enough.