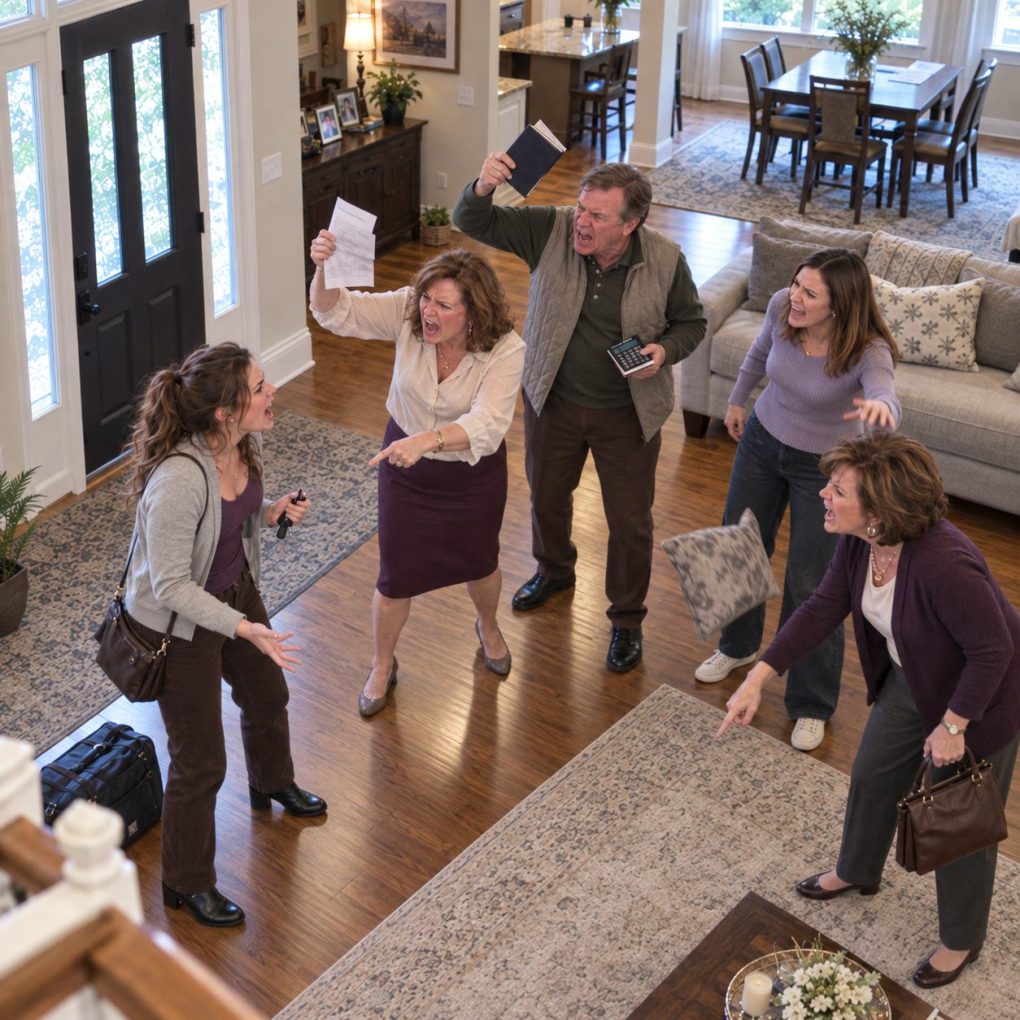
My mother dropped a handwritten bill for $30,000 onto the kitchen counter and gave me until Sunday to pay the first $2,000. If I refused, she said she would take my car. Dad added that the remaining balance would accumulate ten percent interest every month, while my sister laughed and Aunt Linda called me a worthless freeloader.
I was twenty-nine, working as a hospital respiratory therapist in Columbus, Ohio. Three years earlier, I had moved back into my parents’ house after Mom underwent major surgery. They had asked me to stay temporarily, promising that helping with household expenses would be enough.
During those years, I paid $900 monthly toward utilities and groceries, covered several medical bills, and purchased the used Honda Civic I drove to work. The title and registration were entirely in my name. My parents had never mentioned rent, much less a debt approaching thirty thousand dollars.
Mom claimed she had calculated what I should have paid for occupying my childhood bedroom. Dad produced a notebook filled with monthly charges, penalties, and interest that had apparently been added without my knowledge. My sister, Brittany, suggested selling my car immediately because I could take the bus.
I asked whether they remembered our original arrangement. Mom dismissed it as an informal family favor that had expired. Aunt Linda announced that responsible adults paid their parents instead of exploiting them, although she knew nothing about the money I had contributed.
Then Dad reached for my car keys on the counter. I picked them up first and calmly reminded him that the vehicle belonged to me. He warned that refusing to cooperate would mean losing my place in the family, and Mom gave me twenty-four hours to reconsider.
I didn’t argue. I went upstairs, packed my documents, medications, laptop, and several changes of clothes. Before midnight, I drove to my coworker Emily’s apartment, where she had offered me her spare bedroom during difficult hospital shifts.
The next morning, I changed my banking passwords and downloaded three years of payment records. I also checked my credit reports and discovered two recent inquiries from lenders I had never contacted. Both inquiries were associated with applications listing my parents’ address.
I called the lenders and learned that someone had recently applied for a personal loan using my information. Neither application had been approved, but both included an estimated monthly income matching my hospital salary. I immediately reported suspected identity theft and placed fraud alerts on my credit files.
That evening, Brittany sent me a photograph of an envelope addressed to me at my parents’ house. Inside was a notice from a finance company about a vehicle-secured loan application. I stared at the photograph, realizing my parents hadn’t merely threatened to take my car. Someone had already tried to borrow money against it.
I contacted the finance company before its office closed. A representative confirmed that an application had been submitted using my name, vehicle identification number, and home address. The company had not released any funds because the identity verification process remained incomplete.
I explained that I had never applied for the loan and requested written confirmation. The representative directed me to the company’s fraud department, which opened an investigation. I also filed a police report documenting the unauthorized applications and my parents’ threats concerning the car.
Emily encouraged me to speak with an attorney before confronting my family again. I met with Marcus Bennett, a local consumer protection lawyer, and showed him the handwritten rent demand, bank records, credit inquiries, and messages from Brittany. He explained that my parents could not simply create a retroactive rental contract or seize a vehicle titled to me.
Marcus also cautioned that my contributions did not automatically prove every aspect of our living arrangement. We gathered text messages from the period when I moved home, including one from Mom thanking me for staying to help after her surgery. Another message from Dad explicitly described my monthly payments as contributions toward household expenses.
Meanwhile, Mom began calling relatives and claiming I had abandoned her after refusing to pay my debts. Aunt Linda posted an insulting message about irresponsible adult children, carefully avoiding my name. I ignored the public accusations and continued collecting documentation rather than starting an online argument.
Four days after I left, Dad called demanding that I return my car to the driveway. He claimed he had helped me negotiate its purchase and therefore possessed a financial interest in it. I reminded him that I had paid the seller myself and that the title contained only my name.
Dad became angry and said Brittany had already arranged for a buyer to inspect the vehicle. I told him the car was not available for sale. After ending the call, I forwarded the recording of his voicemail and a written account of the conversation to Marcus.
The finance company’s investigation produced a troubling detail. The application had included a photograph of my driver’s license taken from an older family insurance file. Its contact number belonged to Brittany, who had previously helped Mom organize household paperwork.
When Marcus sent a preservation request concerning the application records, Brittany called me in tears. She admitted she had entered the information but insisted Mom had told her I agreed to use the car as collateral. She said the loan proceeds were supposed to cover overdue household bills.
I asked why nobody had requested my permission. Brittany fell silent, then admitted that Mom believed I would eventually accept the arrangement once the paperwork was completed. Before hanging up, she revealed something else: my parents had fallen three months behind on their mortgage, and the supposed back rent was their desperate attempt to make me cover the shortage.
The mortgage trouble explained the sudden demand, but it did not excuse what my family had done. I asked Marcus to communicate with the finance company and preserve Brittany’s admission. The lender confirmed in writing that the application had been closed without funding and that I owed nothing.
My parents had refinanced their house two years earlier to help Brittany open a boutique. The business closed after fourteen months, leaving her with unpaid suppliers and little income. Instead of confronting the consequences, they had quietly used their savings to cover her expenses until the mortgage payments became difficult.
I learned these details when Dad requested a meeting at Marcus’s office. He arrived without Mom and looked exhausted. He admitted the $30,000 figure had been invented to resemble three years of rent, even though nobody had ever agreed to those charges.
Dad also acknowledged that he knew Brittany was attempting to obtain a loan against my car. He claimed he believed the application would only become binding after I signed the final documents. Marcus explained that submitting information in someone else’s name without authorization was already a serious matter, regardless of whether money changed hands.
I demanded three things before considering any further family contact. My parents had to withdraw the fabricated debt, acknowledge in writing that they had no claim to my car, and stop using my personal information. I also made clear that I would cooperate with any investigation rather than conceal what happened.
Mom initially refused, accusing me of caring more about money than family. But when Dad showed her the lender’s written findings, she finally agreed to sign a statement withdrawing the rent demand. Brittany separately admitted in writing that I had never authorized the loan application.
I continued monitoring my credit and cooperating with the fraud investigation. No funds had been disbursed, and the lender removed the unauthorized inquiries after reviewing the evidence. The authorities handled the report independently, and I did not pretend that a family apology erased the underlying conduct.
With Marcus’s assistance, I recovered the remaining belongings from my parents’ house during an agreed appointment. Emily helped me carry the boxes while Dad remained in the living room. Mom watched silently as I removed the last photograph from my childhood bedroom.
Two months later, I signed a lease on a small apartment near the hospital. I purchased secondhand furniture, arranged automatic savings transfers, and began rebuilding the financial cushion I had spent supporting my parents. Dad eventually entered a mortgage assistance program, while Brittany found full-time employment to contribute toward the household bills.
Mom sent me a message asking when I would come home for Sunday dinner. I replied that I needed time and that rebuilding trust would require more than pretending nothing had happened. She had demanded thirty thousand dollars for the privilege of helping my family, then threatened the car I needed for work. Leaving that night had cost me a familiar home, but staying would have cost me something far more important: the right to decide what happened to my own life.