The front door was unlocked, and that was the first thing that felt wrong.
Emily Carter had only come back to Diane Mercer’s brick house outside Raleigh, North Carolina, for one reason: her mother’s locket. She had taken it off during the final dress fitting that afternoon, afraid the clasp would snag the lace, and left it in the upstairs guest room where she had changed.
The wedding was in two days.
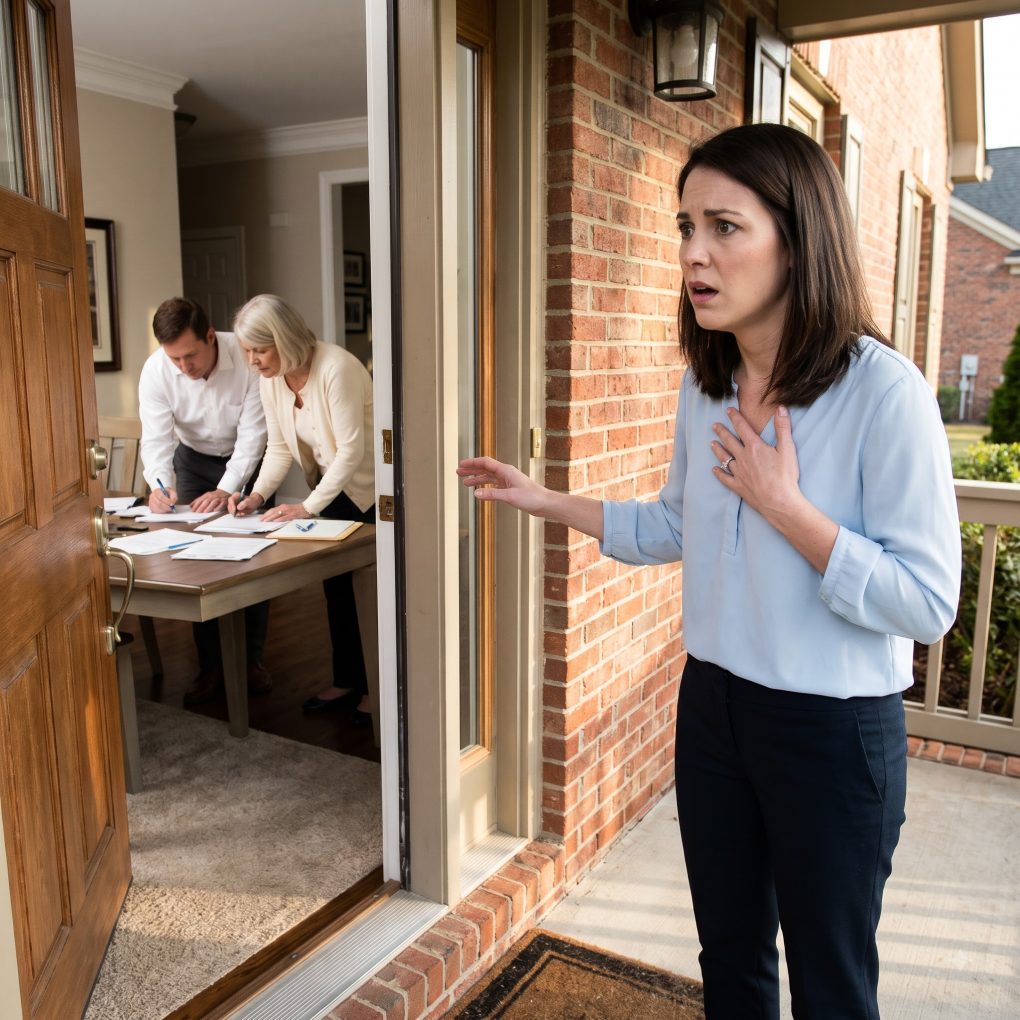
Emily reached for the doorknob, then froze when she heard her fiancé’s voice from inside.
“Once we’re married, she’ll stop questioning everything.”
Ryan.
He was supposed to be at the hotel with his groomsmen.
Emily stood perfectly still on the porch.
Diane laughed softly. “She questions because nobody ever taught her how marriage works. After Saturday, you’re her husband. She’ll listen.”
Emily’s hand dropped from the knob.
Ryan answered, lower now. “The bank still needs her signature.”
“What exactly are you telling her?”
“That it’s part of the homeowners insurance update.”
Emily’s stomach tightened.
Her townhouse had belonged to her mother. After her mother died three years earlier, Emily inherited it outright. Ryan had complained more than once that keeping a paid-off property instead of “using the equity” was financially stupid.
She had always said no.
Inside, papers rustled.
Diane said, “And the line of credit is how much?”
“Two hundred forty thousand.”
Emily stopped breathing.
Ryan continued, “It clears the business note, the cards, and most of what I owe Uncle Mark.”
“You said she doesn’t know about the cards.”
“She knows I have a balance. She doesn’t know the real number.”
Diane gave a dismissive little sigh. “Then don’t tell her until after the honeymoon.”
Emily pressed one hand against the brick wall beside the door.
Two weeks earlier, Ryan had handed her a folder and asked her to sign several pages before the wedding. She had skimmed them, noticed a lender’s name she didn’t recognize, and said she wanted her attorney to review everything first.
Ryan had become offended.
He told her she was treating him like a criminal.
Now Diane said, “What if she takes it to that lawyer again?”
“She won’t. I’ll give it to her Saturday morning when she’s getting ready. She’ll be emotional. Everyone will be around. She signs, we leave for the ceremony, done.”
Emily felt something inside her go cold.
Then came the sentence that broke whatever was left.
Diane said, “Good. Because once you pay off your mess, we can finally talk about putting my name on the house too. I’m not spending my retirement renting while my son’s wife sits on free property.”
Ryan laughed.
“Give me six months.”
Emily looked down at her engagement ring.
For eleven months, he had told her they were building a future together.
They were.
Just not the future she thought.
She stepped backward from the door without making a sound. Her mother’s locket was still upstairs.
For the first time, Emily did not care.
She walked to her car, locked the doors, and called one person.
“Rachel,” she said when her attorney answered. “I need you to tell me exactly what Ryan tried to get me to sign.”
Emily thought she had already heard enough to destroy the wedding. Then her attorney checked the paperwork—and discovered that Ryan and Diane had started moving forward long before Emily ever stood outside that door.
Rachel did not tell Emily to calm down.
She said, “Send me a photo of every page Ryan gave you.”
Emily drove straight to her office, photographed the unsigned folder, and emailed it. Rachel called back twelve minutes later.
“Do not sign any of this.”
“I wasn’t planning to.”
“This is not an insurance update. It’s a home-equity line of credit application secured by your townhouse. There’s also a personal guaranty for Mercer Outdoor Concepts.”
Ryan’s landscaping company.
Emily closed her eyes. “For two hundred forty thousand?”
“That’s the maximum line.”
The betrayal suddenly had numbers, account names, and signature boxes.
Rachel continued, “The good news is that these pages are unsigned. He cannot borrow against property titled only to you without valid authorization. But I want to know whether an application has already been opened.”
The rehearsal dinner started in ninety minutes.
“Can we find out tonight?”
Rachel called the lender’s fraud department. Twenty minutes later, the lender confirmed that a preliminary application existed in Emily’s name.
Her hands went numb.
It had been submitted three weeks earlier.
The application listed her Social Security number, income, employer, property address, and an estimated value for the townhouse. Copies of tax documents had been uploaded.
“I never gave Ryan my tax returns,” Emily whispered.
“You kept copies at home?” Rachel asked.
“In my filing cabinet.”
“Did he have access?”
Emily thought about the key Ryan had been given after they became engaged.
“Yes.”
Rachel’s voice became precise. “Do not confront him alone. Preserve every text, email, and document. Change your financial passwords. Contact the credit bureaus. I’ll notify the lender in writing that you dispute and did not authorize the application.”
Then Rachel paused.
“There’s something else.”
The application identified a secondary contact for scheduling and document questions.
Diane Mercer.
Emily almost laughed from disbelief.
Her future mother-in-law had not merely encouraged Ryan from the kitchen. Her phone number and email address were already inside the loan file.
Emily opened her wedding planner.
Flowers. Music. Catering. A ballroom full of people expecting a marriage in two days.
She called the venue first.
“I need to cancel Saturday’s wedding.”
The coordinator went silent. “All of it?”
“All of it.”
Next came the officiant, photographer, florist, and band. Some deposits were gone. Emily accepted that.
At 8:17 p.m., she removed her engagement ring and placed it in an envelope.
Then she texted Ryan.
The wedding is canceled. Do not come to my house. Rachel Grant will contact you regarding the loan application.
Her phone rang immediately.
Ryan.
She declined it.
On the third call, she blocked him.
At 8:31, Diane called from another number.
Emily answered.
“You misunderstood,” Diane snapped. “Ryan was trying to protect your future.”
“My future?”
“You’re throwing away a marriage over paperwork.”
Emily looked at the empty ring box.
“No. I’m canceling a marriage because of what the paperwork proves.”
Diane went quiet.
Then Emily heard Ryan in the background.
“Ask her if she found the second application.”
Emily froze.
Diane abruptly hung up.
There was a second application.
And Emily had no idea what it was for.
Rachel found the second application the next morning.
It was not another mortgage document.
Ryan had applied for a $110,000 business line of credit for Mercer Outdoor Concepts and listed Emily as a personal guarantor. The application included her income and assets, and an electronic signature bearing her typed name appeared on a guaranty she had never seen.
The lender had not funded it.
Their verification team had emailed Emily two days earlier, but the message had gone to her spam folder. Rachel forwarded Emily’s written dispute immediately and told her to preserve the original email.
Emily sat in her office staring at the screen.
Ryan had not been preparing for marriage.
He had been preparing access.
By noon, he had retained an attorney. Through counsel, he denied forging anything and claimed Emily had verbally agreed to help his business. Rachel’s response was simple: all further communication would be in writing, and the lenders could determine what documentation they had received and from whom.
Emily did not argue with him.
She changed the locks after confirming Ryan had never established residence in her townhouse, froze her credit files, replaced compromised account numbers, and gave the lenders copies of the documents she had kept.
Then she remembered why she had gone to Diane’s house in the first place.
Her mother’s locket.
Emily refused to go back alone. Rachel contacted Ryan’s attorney, and the next afternoon Diane placed the locket, Emily’s dress bag, and several personal items into a box that a courier collected.
When Emily opened it, the locket was wrapped in tissue paper.
For the first time since the porch, she cried.
Not for Ryan.
For her mother, who had worn that tiny gold oval for twenty-six years and had left Emily the townhouse with one instruction written in her estate notebook: Don’t let anyone rush you into decisions about the house.
The sentence felt almost impossible now.
The wedding weekend passed quietly. Emily stayed with her closest friend while the venue dismantled flowers meant for a ceremony that never happened.
Over the following months, both lending matters were investigated. The home-equity application was withdrawn without funding. The business lender also closed its application after Emily disputed the guaranty. Ryan’s attorney negotiated directly with the lenders regarding the records and his responsibility for them.
Emily did not recover every wedding deposit.
She did recover something more important: her finances remained hers, her townhouse remained unencumbered, and no marriage certificate ever gave Ryan another opportunity to explain away what she had heard.
Diane sent one final message.
You embarrassed our family over money.
Emily read it once, then blocked the number.
Six months later, she stood on her townhouse porch before dinner with friends. Her mother’s locket rested against a simple navy dress.
Rachel noticed it.
“You got the clasp repaired.”
Emily smiled. “I did.”
She touched the locket and looked at the front door Ryan had once expected to walk through as her husband.
The strangest part was that she had gone back to Diane’s house that night because she was afraid of losing one small piece of her mother.
Instead, standing outside that door and hearing the truth had kept her from losing the home, the credit, and the future her mother had worked so hard to leave her.