Two days after I sent my family one penny for my brother’s baby shower, my sister called from our bank, screaming. She’d tried withdrawing $12,000 from our joint account and found only $286. My birthday had been forgotten again, but suddenly everyone remembered my number.
I’m Emily Carter, thirty-four, a respiratory therapist in Columbus, Ohio. My brother, Ryan, was expecting his first baby with his wife, Jenna. My younger sister, Madison, handled most family celebrations. For three years, I’d quietly helped cover our mother’s expenses after her hip surgery.
Madison and I had opened a joint checking account for Mom’s care. I deposited $1,100 every month; Madison contributed occasionally. We agreed withdrawals would cover prescriptions, transportation, and approved home-care visits. When Mom recovered, I kept depositing, assuming the money was a safety cushion.
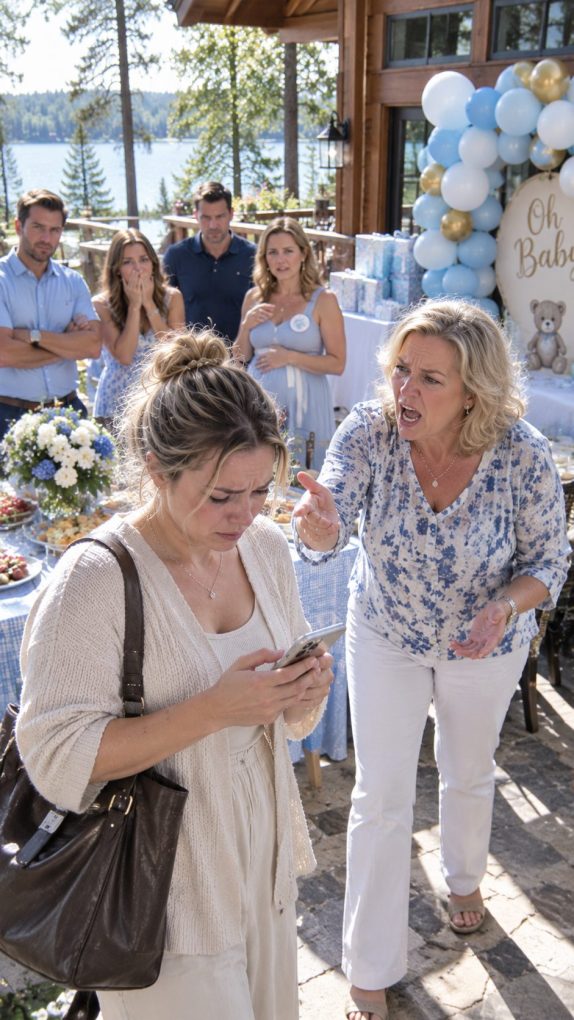
On my birthday, nobody called. The family chat was busy debating Jenna’s balloon arch and dessert table. A week later, Dad invited me to the shower, then demanded $200 toward catering. When I reminded him they’d missed my birthday, he replied that adults shouldn’t require applause.
I sent a penny with the note, That’s all I have left for you. Then I reviewed the joint account before making another deposit. Transfers marked family support had been going to Madison’s personal account, including $4,800 during the week of my birthday.
Madison admitted she’d used some money for Ryan’s nursery renovation. She insisted it was family money and refused to provide receipts. I checked the statements, identified the unused portion of my own deposits, and asked the bank about transferring my funds without affecting her contributions.
I moved $19,600 of my traceable contributions into an account solely in my name, leaving Madison’s $286 untouched. I stopped future deposits and arranged to pay Mom’s genuine medical costs directly. I did not freeze Madison’s access, close our joint account, or take anything she’d deposited.
Two days later, Madison visited the branch expecting to withdraw $12,000. She’d promised a contractor that the nursery renovation would be paid for by Friday. The teller explained the balance. Madison called me selfish, then warned that Ryan might lose his deposit and his contractor.
Dad joined the call, shouting that I was ruining his first grandchild’s celebration. I asked who had authorized a nursery renovation from an account meant for Mom’s medical needs. He went quiet. Apparently Madison had told him I’d offered to pay for it.
Then Mom took the phone. Her voice shook as she said she’d never known about the renovation, the transfers, or even the size of the account. She asked Madison a question nobody could answer: If that money was for my care, why was it disappearing into someone else’s house?
Madison hung up before answering Mom. Ten minutes later, Ryan called, demanding I restore the account. He said the contractor had already ordered cabinets and expected payment under the agreement Ryan signed. I reminded him I hadn’t approved the work or promised a dollar.
Ryan insisted Madison had shown him an account screenshot with more than twenty thousand dollars. He assumed it was a gift. I asked why he’d never confirmed that assumption with me, the person supplying almost every deposit. He said Madison told him not to bother me.
Mom came to my apartment that evening with home-care receipts. She’d believed Madison paid those bills from the joint account. In fact, most were charged directly to my credit card, and I’d reimbursed myself only rarely. The account had accumulated as her needs declined.
We compared receipts with bank records. Several transfers carried descriptions such as mobility equipment or caregiver reimbursement but led straight to Madison’s personal checking account. One funded a furniture purchase. Another coincided with a deposit on the shower venue. Mom fell silent.
I didn’t accuse Madison of a specific crime or demand the bank reverse authorized transactions. She was a legal joint owner, with withdrawal rights under the account agreement. But she had broken our stated purpose for the money and misled everyone about what I had agreed to fund.
On Saturday, I met Madison and Ryan at Dad’s house. I brought printed statements and the original messages establishing the account’s purpose. Madison said she deserved compensation for coordinating Mom’s appointments. I acknowledged her work, then asked when we’d agreed to pay her thousands without telling Mom.
Dad began defending her until Mom placed her pharmacy receipts on the table. She explained that she’d cut back on groceries because she feared her medical savings were running low. Madison had let her believe that while transferring money for celebrations and home improvements.
Ryan looked genuinely sick. He said he would cancel the remaining renovation work and negotiate with the contractor over completed work and cancellation costs. Jenna, who’d known nothing about the account, said they could hold the shower in their backyard. Neither expected me to fund the changes.
Madison accused me of keeping score and embarrassing her. I said I was asking for an accounting, not revenge. My attorney advised preserving records and considering a written repayment agreement for withdrawals that exceeded what we’d discussed. I wouldn’t negotiate while anyone shouted.
Mom reached across the table for my hand. She apologized for forgetting my birthday and for treating my help as automatic. Then she turned to Madison and asked for every transfer receipt. For the first time in years, the family’s demands weren’t aimed at me.
Ryan and Jenna hosted a modest baby shower in their backyard. They borrowed chairs, served sandwiches, and used decorations they’d purchased. I attended for an hour because Jenna invited me personally, without attaching a payment request to the invitation.
The contractor completed only the work already paid for, and Ryan arranged an installment schedule for the remaining charges he owed under his agreement. I didn’t sign anything or make promises on his behalf. The renovation was smaller than he’d imagined, but the baby’s room was safe and ready.
Madison eventually provided records showing she’d used $7,300 from the joint account on expenses unrelated to Mom. We reviewed the dates and available balances with an accountant so nobody had to rely on competing memories. The misuse was impossible to dismiss.
With a lawyer’s help, Madison agreed in writing to repay a negotiated amount over time. I didn’t claim the bank had stolen the money or pretend I could retroactively revoke her joint ownership. We arranged to close the account by mutual agreement.
I set up direct payments for the few services Mom still needed and sent her receipts each month. Dad began contributing regularly too. It was the first time he’d offered money without asking whether I could cover the difference, and I welcomed the change cautiously.
Mom invited me to lunch at a quiet diner the following month. She brought a birthday cake and admitted she’d grown accustomed to celebrating the children demanding attention. She said my silence had made it easy to assume I didn’t need anyone. I told her quiet wasn’t the same as unhurt.
Madison apologized later, though she struggled not to explain herself. She’d grown jealous of my savings and convinced herself I wouldn’t miss the money. I told her I had savings because I worked hard and skipped things I wanted, not because my time had no value.
When Ryan’s daughter arrived, I visited the hospital with a handmade blanket. Jenna thanked me for coming and asked about my work. There were no invoices, requests for gifts, or speeches about what family owed one another. I held the baby until she fell asleep.
My relationships with my parents improved slowly. I kept my finances separate and declined invitations that came with hidden obligations. Sometimes Mom remembered to call just to ask how my day had gone. Those conversations meant more than the belated cake.
One penny hadn’t ruined my family. It had revealed how much they expected me to give without ever noticing what I needed. When Madison found the account nearly empty, she faced the cost of spending money I had earned. I learned that love doesn’t require unlimited access to my bank account.