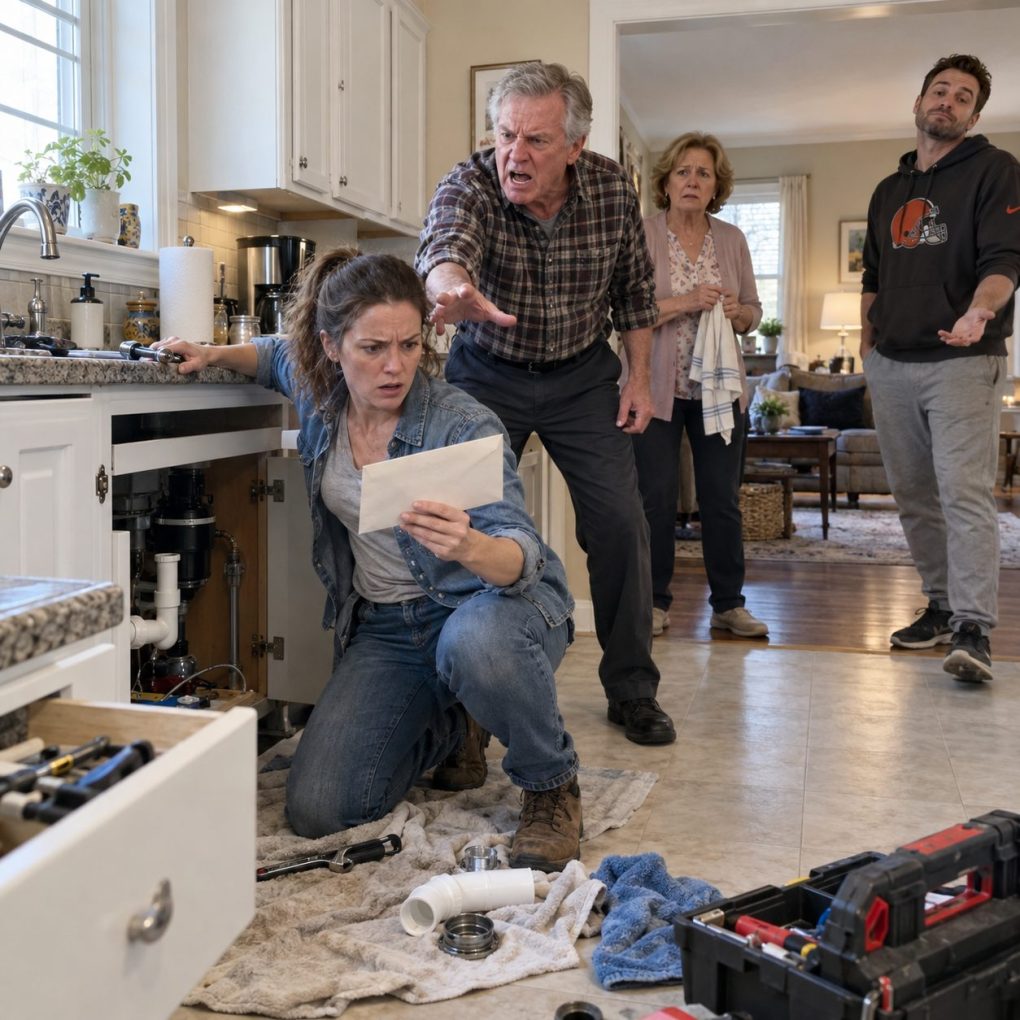
“PUT THAT DOWN!” Dad shouted when I found the envelope in their kitchen drawer.
I’d been on my knees for forty minutes, replacing a corroded supply line while my brother, Ryan, sat in the living room watching a game. When I opened the junk drawer for plumber’s tape, a thick envelope slid onto the floor.
Across the front: ESTATE PLAN — FINAL COPY.
“I wasn’t looking for it,” I said.
“Then stop reading.”
But a page had already fallen open. I saw my parents’ house, their savings, and an estimated combined estate of $740,000. Under beneficiaries, there was one name: Ryan. On a handwritten care memo clipped to the will, there was mine.
“Nora will continue coordinating appointments, home maintenance, and daily assistance,” I read aloud.
Mom appeared in the doorway, drying her hands on a dish towel.
“Ryan has a family to provide for,” she said. “You’re independent.”
“Being single doesn’t mean my time is free.”
“You know what I mean.”
I was thirty-three, a licensed plumber in Dayton, Ohio. For four years I’d handled Dad’s cardiology appointments, fixed their boiler, paid for a new water heater when their savings were supposedly tight, and stocked the freezer after Mom’s knee replacement. Ryan owned a remodeling business thirty minutes away. He liked to describe himself as “the one who’d carry on Dad’s legacy.”
“Is this a draft?” I asked.
Dad set his jaw. “We signed it last month.”
“And the care instructions?”
“Of course we still expect you to help,” he said. “Inheritance has nothing to do with that.”
I studied the next page. Ryan was also named financial power of attorney, authorized to manage accounts if they needed assistance. There was no obligation attached to the letter about my work; I knew that. What stung was how confidently they had volunteered my life.
Ryan came in when he heard us arguing.
“Don’t make this about money, Nora.”
I put the paperwork back in the envelope and set my wrench on the counter.
“No,” I said. “I’m making it about asking me.”
Dad called after me as I left. “You’ll be back when something breaks!”
I didn’t go back. I gave them contact numbers for a plumbing company and a senior transportation service, then stopped answering requests disguised as emergencies.
Eight months later, Mom called just after midnight.
“Your father’s in the hospital,” she whispered. “And Ryan says there’s no money left to bring him home.”
“What do you mean, no money?” I asked.
Mom was sitting outside Dad’s hospital room. He’d fallen on the basement stairs and fractured his hip. Surgery had gone well, but discharge would require either a rehabilitation facility or substantial help at home.
“Ryan says the accounts are tied up,” she whispered. “He told us you’d know what to do.”
Of course he had.
I drove to the hospital the next morning, not because I was back on call, but because Mom sounded frightened. Dad looked smaller against the white pillow. He didn’t say hello.
“Can you stay at the house while I recover?” he asked.
“No. I can help you speak with the discharge planner.”
His eyes narrowed. “After everything we’ve done for you?”
I placed the plastic cup of water within his reach. “Tell me what care you need. Not what you want me to give up.”
At eleven, a hospital social worker outlined short-term rehabilitation, coverage questions, and home-safety options. Mom kept glancing at my phone, as if waiting for me to volunteer a solution.
Ryan arrived after lunch in a pressed polo shirt.
“Good. Nora’s here. She can use her vacation days until Dad gets steady.”
“I can’t,” I said.
He laughed. “You fix strangers’ sinks all week. You can help your own father.”
In February, he’d sent me a photograph of a leaking faucet with the caption YOUR TURN. I’d replied with a local plumber’s number. He called me selfish in three separate messages. Now he was volunteering my vacation days without asking.
“The hospital needs an actual plan, Ryan.”
“We’ve got a plan. You’re it.”
Mom touched his sleeve. “Please stop.”
For the first time, he looked startled that she was addressing him.
I asked about their finances. Mom explained that Dad had given Ryan account access under the power-of-attorney paperwork shortly before I left, when keeping track of bills became difficult. Dad nodded. He was alert, understood our questions, and said he’d trusted Ryan to handle things.
“What does ‘tied up’ mean?” I asked.
Ryan folded his arms. “You walked away from this family. You don’t get to audit us.”
“I’m not asking for account passwords. They need to know whether they can afford care.”
Mom looked at Dad. Then she pulled a folded bank statement from her purse.
“I called the bank yesterday,” she said. “These aren’t payments for us.”
Six transfers, each labeled with Ryan’s remodeling company. The first had been made three days after I left. The last was dated Friday.
Dad’s hand shook as he reached for the paper.
“Ryan,” he said, his voice thin but steady, “tell your mother why you moved sixty-two thousand dollars out of our savings.”
Ryan stared at the statement until Dad repeated the question.
“My company had a cash-flow problem,” he said. “A contractor delayed payment. I was going to put it back.”
“You told me you were moving the money somewhere safer,” Mom said.
“I was protecting our investment.”
“Our?” Dad whispered.
Ryan glanced at me. “It’s not like it was going to anyone else.”
There it was. Eight months ago, the estate plan had looked like a promise of future money. Ryan had treated it as permission to spend their present savings.
I asked Mom for the rest of the statement. Their house accounted for roughly $665,000 of the estimated estate. The actual savings had been about $75,000. Ryan’s transfers had stripped away nearly all of the cash they depended on for emergencies.
Dad stared toward the window. “I signed the power of attorney because my hands shake when I write checks.”
Ryan spoke quickly. “Dad, I can replace it once the remodeling job closes.”
“When?” Mom asked.
He said nothing.
I could have reminded them about the water heater, the furnace, and every afternoon I’d spent waiting for delivery trucks. Instead, I moved a chair beside Dad’s bed.
“Your money is yours while you’re alive,” I said. “You need an attorney who represents you, not Ryan. And you need a care plan that doesn’t rely on me leaving my job.”
Ryan scoffed. “So you’re just going to watch them suffer?”
“No. I’m going to help them find professionals. That is different from becoming their unpaid employee.”
Mom covered her mouth. Dad looked at the ceiling for a long time.
Over the following week, they met privately with an elder-law attorney. Because Dad was still able to understand and make decisions, he revoked Ryan’s financial power of attorney. The lawyer helped notify the bank, request a full accounting, and demand repayment. She explained that recovering the money might require civil action; nobody promised a quick fix.
Dad moved to a rehabilitation center while Mom arranged estimates for accessibility improvements. Insurance covered part of his rehabilitation, with costs and limitations they reviewed before agreeing to anything.
Ryan sold equipment and repaid $18,000 by the end of the summer. The rest remained disputed, subject to a written repayment demand. His business survived, but my parents no longer let him manage a dollar.
They also met with an estate planner to reconsider their will. Mom offered to split everything equally.
“You can make whatever plan you believe is fair,” I told her. “But please don’t mistake an inheritance for a contract to take care of you.”
Two months later, I visited for Sunday coffee. Dad had hired a plumber to replace the kitchen faucet. It cost more than I would have charged, and he didn’t complain once.
As I reached for my mug, he glanced at the drawer where he’d once kept the envelope.
“I should have asked,” he said.
“Yes,” I answered.
The tap didn’t drip. My wrench was at home. For once, I was too.