“Keep dreaming,” my brother said, sliding my business proposal back across the restaurant table as though it were a dirty napkin.
Six years later, he said it again.
Grant raised his glass at our parents’ anniversary dinner in Raleigh. “To Emma’s little startup. Still selling imaginary money, sis?”
Dad chuckled. Mom studied the candle between us. I was thirty-nine, but the old feeling returned instantly: being seventeen, coming home from my grocery-store shift to find Grant’s college acceptance framed on the mantel while my scholarship letter sat beneath a pile of coupons.
“It’s doing fine,” I said.
“Sure it is.” He adjusted the cuffs of his expensive jacket. “I run commercial lending at Briar County Bank. I know what successful businesses look like.”
He ordered a second bottle of wine without asking anyone. I watched Mom fold her napkin into smaller and smaller squares. Last week she had canceled our Sunday coffee, saying she was tired. Tonight there were gray shadows beneath her eyes.
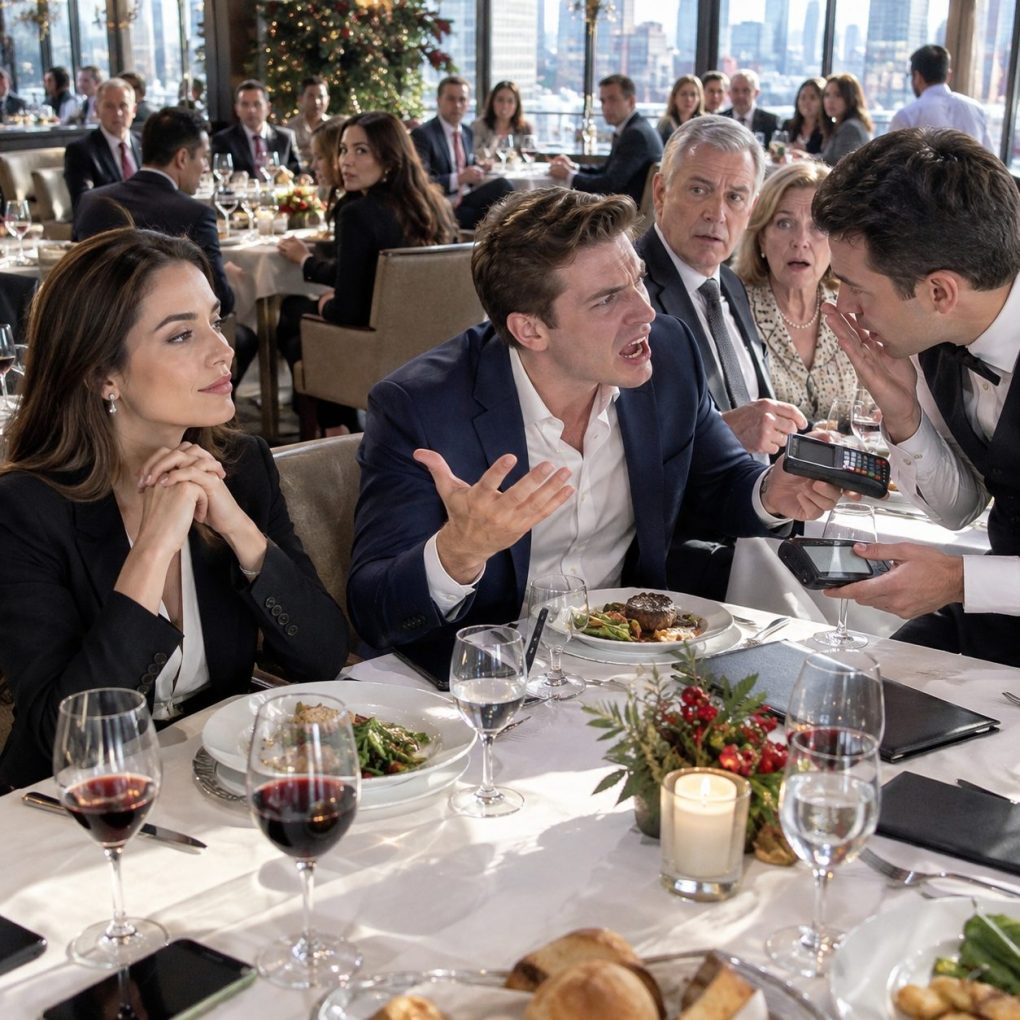
When the check arrived, Grant snatched it from the waiter. “I’ve got this. Unlike some people, I can afford dinner.”
The card machine beeped. The waiter returned, apologetic, and said the charge had been declined.
Grant went red. “Run it again. Your machine is broken.”
I reached for my wallet, but he slapped his hand over the bill. “Don’t make this more embarrassing.”
The waiter tried a second time. Same result. Grant began scolding him loudly enough that nearby tables turned.
Then the waiter glanced at the television above the bar, where a financial-news banner crawled beneath a photograph of me. He looked from the screen to my reservation card.
“Ms. Walker,” he whispered, “your bank just acquired his.”
Our company had started as software that helped small businesses manage payroll. It had grown into a financial holding group with a bank subsidiary. That afternoon, after months of regulatory review, our subsidiary had completed its purchase of Briar County Bank. I owned a controlling stake in the holding company. The news had just become public.
Grant followed the waiter’s eyes. His face changed.
“That’s you?” Dad asked.
Before I could answer, Mom gripped my sleeve. Her folded napkin lay abandoned beside her plate.
“Emma,” she whispered, “please don’t let them take our house.”
I turned toward her. “Who would take your house?”
She looked at Grant.
And for the first time that evening, my brother stopped talking.
Grant said Mom was confused. He blamed medication, stress, the wine she hadn’t touched. I had heard him talk over her my entire life, but never with that much fear beneath his voice.
“Tell me what happened,” I asked her.
Mom pulled a creased envelope from her purse. It contained a notice from Briar County Bank about a defaulted $430,000 commercial loan to a property company called Oak Hollow Development. The letter identified our parents’ house as collateral.
“Grant said the business would pay it off in six months,” Dad admitted. “He said signing would help us retire.”
“You signed a mortgage against your home?”
Dad lowered his head. Mom shook hers. “I never signed anything. He said I didn’t need to.”
Grant leaned forward. “This is between me and them. You don’t understand how financing works.”
I did understand one thing: owning a bank did not give me the right to erase a debt or secretly inspect customer accounts. The acquisition also didn’t cause his declined card; he admitted his issuer had texted him about a spending-limit problem before dinner.
I paid the restaurant bill on my own card and drove Mom and Dad home. On their porch, Dad tried to thank me. I couldn’t find an answer. For years, when Grant came up short, they had found money for him. When I needed help getting my startup off the ground, Dad had said failure would teach me character.
The next morning I gave Mom the number of an independent attorney. I also disclosed the family conflict to our board and removed myself from all decisions involving Grant’s loan. Outside counsel and the bank’s compliance team would examine the documents; I would receive no special access to their confidential files.
Mom’s attorney obtained the recorded deed of trust and the closing paperwork. Dad’s signature was genuine. Mom’s wasn’t. The notary acknowledgment said both had appeared in person on a day Mom had been admitted to a hospital emergency department. Her hospital records made that impossible.
She called me after reading it. “I thought he was only taking Dad to sign papers. He kissed my forehead before they left.”
I sat on my kitchen floor with my phone against my ear, remembering how Grant had laughed when I offered to repair their porch railing for free.
Then Mom said the sentence that broke what little trust I had left.
“Your father knew I hadn’t signed. Grant told him he’d take care of it.”
I could hear Dad crying behind her.
And suddenly I understood why he hadn’t looked me in the eye at dinner.
Dad asked to meet me at the diner near our childhood home. He arrived wearing the green sweater Mom had mended at the elbow years ago. I remembered being eight and watching her thread the needle under a kitchen light while Grant slept upstairs.
“I thought I was protecting your mother,” Dad said, staring into his coffee. “When I saw her name on the paperwork, Grant said it was a technicality. I knew something wasn’t right, but I didn’t ask.”
“You watched her lose sleep over those letters.”
He nodded. He had always made excuses for Grant. I used to think it was love. At the diner, I saw how easily his fear of disappointing one child had taught him to betray the other.
The independent review unfolded over several months. Bank investigators found that Grant had used his position to steer the loan toward a colleague without disclosing his ownership interest in Oak Hollow. The property company had received the funds; some of the invoices supporting the borrowing were fabricated. Mom’s signature on the recorded deed of trust had been forged, and the notary’s account did not match the hospital records.
I learned the findings only through public filings and information Mom chose to share with me. The bank suspended Grant during the investigation, then terminated his employment after its procedures were complete. It referred the suspected misconduct to law enforcement and filed a civil claim against his company.
Mom’s lawyer challenged the lien on her interest in the house. Rather than fight over a document its own review had found unreliable, the bank agreed to release the house as collateral while preserving its claim against Oak Hollow and the people responsible. Dad’s genuine signature made the negotiations harder, and his own lawyer explained how close his decision had brought them to losing everything.
Grant eventually pleaded guilty to a fraud charge connected to the loan. He received a sentence that included restitution and supervised release. His expensive car disappeared from the driveway long before the case ended. I never asked whether it had been sold or repossessed.
My parents kept their house, but I refused to become their emergency fund. I paid for Mom’s first consultation with her lawyer because she had asked for help understanding her rights. After that, the decisions were hers. She began managing the bills herself. Dad apologized without asking me to make anything disappear.
One Sunday, Mom invited me for coffee. The porch railing I’d repaired years earlier was still there, its paint worn thin where hands had gripped it. She placed two mugs on the table, then brought out an envelope containing my old startup proposal.
“Grant left this here,” she said. “I should have read it when you first showed us.”
The pages were yellowing. Across the top, in his handwriting, were the words KEEP DREAMING.
She looked ashamed. I didn’t tell her it was fine, because it hadn’t been.
Instead, I took the proposal home and slipped it into a drawer beside the original sketch of our first product. That night my phone buzzed with a message from Mom: I read every page. I’m proud of you.
It was six years late. I cried anyway.
My brother’s card had declined because he had spent beyond his limit, not because I’d acquired his bank. That distinction mattered. I hadn’t taken his money, his job, or our parents’ house.
He had built his troubles himself.
And the business he once called a dream had finally taught me something success alone never could: I didn’t have to keep paying for my family’s approval.