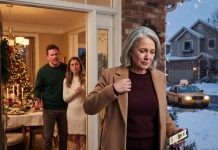
My daughter-in-law threw my clothes onto the porch at 8:10 on a Tuesday morning and called me a leech loud enough for the neighbors to hear. My son, Andrew, stood behind her in the entryway wearing a navy suit and holding his car keys. He was the CEO of a regional logistics company. He said nothing.
I had been staying with them for seven weeks after a pipe burst in my townhouse and flooded the first floor. I paid for groceries, covered half the utilities, and had already written them a check for the guest-room repairs Lauren insisted were necessary because I was “using the space.”
Still, she pointed at two suitcases on the porch and said, “You’ve lived off us long enough.”
I looked at Andrew.
He looked at the floor.
That hurt more than her words.
I picked up my clothes without arguing. Lauren kept talking behind me, saying successful adults should not need their children, saying I had become comfortable because Andrew had money.
What she did not mention was that Andrew’s company had money partly because I had been quietly keeping it alive.
Three years earlier, when his company nearly lost its main credit line after a failed expansion, I had pledged a $2.4 million certificate of deposit as collateral for a standby guarantee. The arrangement was temporary, supposedly six months.
It never ended.
The bank renewed it every year because Andrew’s company still depended on the borrowing facility.
Andrew knew.
Lauren apparently did not.
I loaded my suitcases into my Buick and drove directly to First Atlantic Bank.
At 9:03, I sat across from the commercial banking officer and said, “I want my guarantee withdrawn at the first contractually available moment.”
She studied me carefully.
“Mrs. Bennett, you understand this may trigger a covenant review?”
“I do.”
She made one phone call to legal.
Then another.
At 9:26, she slid a confirmation across the desk.
The guarantee was officially revoked subject to the agreement’s notice terms, and the bank immediately froze further draws while it reviewed the company’s collateral position.
At 9:41, my phone rang.
Andrew.
I declined it.
At 9:43, he called again.
Then his chief financial officer.
Then a number I recognized from the company’s board chair.
At 9:56, the CFO texted me:
The board has called an emergency meeting. Please tell me what changed.
I looked at my suitcases in the back seat.
For once, they were about to find out.
Andrew reached the bank before I left.
He came through the doors fast enough that the security guard stood up.
“Mom, what did you do?”
I remained seated.
The banking officer closed the conference-room door behind him.
“What I should have done two years ago.”
Andrew stared at the paperwork.
“You pulled the guarantee?”
“I stopped renewing it.”
He ran both hands through his hair.
“You can’t do that without warning.”
I almost smiled.
“That sentence sounds familiar.”
He understood immediately.
His face changed.
“Lauren was angry.”
“And you were silent.”
He sat down.
For the first time that morning, the CEO disappeared and my son was sitting across from me.
He explained that the company was negotiating a major acquisition and needed access to the full credit facility for another ninety days.
Without my guarantee, the bank could cut the borrowing limit dramatically.
I asked, “Did you tell the board the facility depended on my money?”
He did not answer.
That was answer enough.
The board meeting happened at noon.
I was asked to join by phone.
The board chair, Martin Keller, was direct.
“Mrs. Bennett, were you compensated for providing this collateral?”
“No.”
Silence.
The CFO interrupted.
“We disclosed the related-party support in the original financing package.”
Martin responded, “Three years ago. I’m asking about renewals.”
Nobody had a good answer.
Andrew had allowed the arrangement to become permanent without renegotiating it or replacing my guarantee.
Worse, he had repeatedly presented the company’s liquidity position as independently stable.
Not fraudulent.
But incomplete enough to make the board furious.
I told them I had no intention of destroying the company.
I would honor the existing notice period.
But I would not extend the guarantee again.
Martin thanked me.
Andrew said nothing.
After the call, he sat across from me for nearly ten minutes.
Finally, he asked, “Where are you going to stay?”
That question almost broke me.
Not because I needed somewhere to go.
My insurance had already arranged a furnished rental.
Because it was the first time he had asked about me since I left his porch.
I told him I was fine.
Then I said, “Your company has ninety days to learn how to stand without me.”
He nodded.
“So do I.”
The next three months were ugly for Andrew’s company.
The acquisition was postponed.
The board froze executive bonuses.
The finance team negotiated a smaller credit facility backed by company assets instead of my savings.
Two warehouses were sold.
Andrew had to explain to investors why the business had relied for years on personal family collateral.
He hated that.
But the company survived.
Lauren called me twice.
The first time, she accused me of trying to ruin Andrew.
I hung up.
The second time was different.
She said Andrew had finally told her about the guarantee.
Then she went quiet.
“You had over two million dollars tied up for his company?”
“Yes.”
“For three years?”
“Yes.”
She whispered, “I didn’t know.”
“I know.”
She apologized for calling me a leech.
I accepted the apology.
I did not move back in.
By summer, the repairs on my townhouse were finished.
I moved home.
The first night back, I sat in my own kitchen with cardboard boxes around me and realized how much peace I had traded away just to avoid making Andrew uncomfortable.
He visited a week later.
No suit.
No company car.
Just jeans and a grocery bag.
He put dinner on the counter.
Then he said, “I failed you.”
I waited.
He did not blame Lauren.
That mattered.
He said, “I let her speak to you that way because I was afraid of another argument. And I told myself your guarantee was just paperwork because admitting what it really meant made me uncomfortable.”
“What did it mean?”
“That I was still depending on my mother while pretending I had built everything alone.”
That was the first honest thing he had said about it.
I forgave him.
But I did not restore the guarantee.
A year later, the company had paid down enough debt to operate under a normal commercial line.
Andrew’s board added stricter disclosure rules for related-party financing.
He stayed CEO.
Lauren and I remained polite.
Never close.
That was fine.
My certificate of deposit returned fully under my control.
Sometimes Andrew jokes that I taught his company its most expensive finance lesson.
I tell him he has it backward.
The lesson was never about money.
It was about silence.
Lauren threw my clothes onto the porch.
Andrew said nothing.
I left quietly.
And that quiet decision forced everyone to finally say out loud who had really been supporting whom.