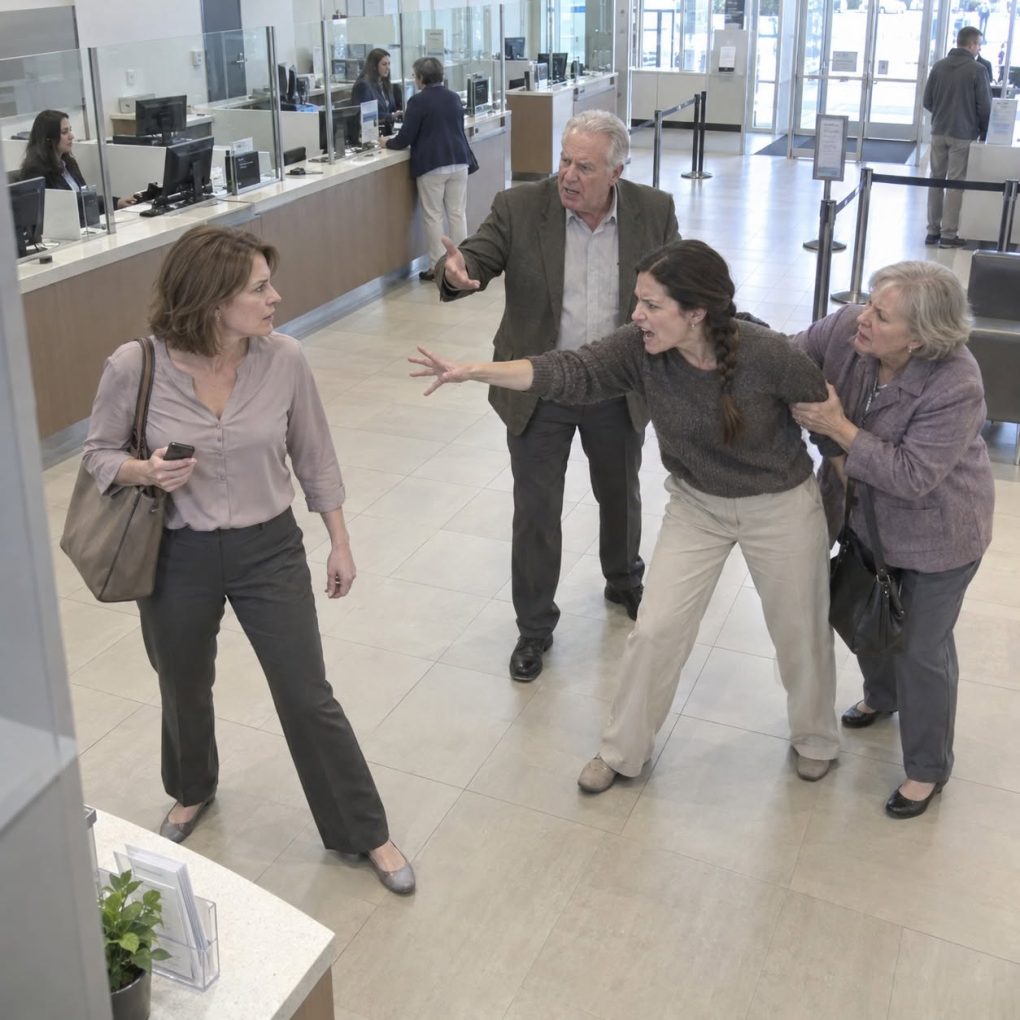
My sister Lauren threw a mug of boiling coffee at me because I refused to co-sign a loan in her name. It happened in my mother’s kitchen in suburban Pennsylvania, with six relatives standing close enough to stop her. Nobody did. The coffee hit my shoulder and chest, soaking through my blouse before the mug shattered against the cabinet behind me.
I screamed from the heat and stumbled backward. Lauren did not apologize. She pointed at me and shouted, “This is what happens when you think you’re better than your own family.” My mother grabbed a towel, but instead of confronting Lauren, she told me not to make the situation worse.
The argument had started twenty minutes earlier. Lauren wanted a $42,000 personal loan to consolidate credit cards and fund what she called a “fresh start.” Her credit score was too low to qualify alone. Mine was excellent, and she had already decided that meant I should sign.
I said no.
Lauren acted as though I had stolen something from her. She reminded everyone that I earned more, had no children, and owned my condo outright. My uncle actually suggested that co-signing would cost me nothing if Lauren made the payments.
That sentence told me nobody in the room understood what they were asking.
I explained that co-signing made me legally responsible for the entire debt. Lauren had already missed payments on two previous loans. She had also borrowed $8,000 from me over four years and repaid less than a thousand.
My mother sighed and said, “She’s your sister.”
I replied, “That doesn’t make my credit family property.”
That was when Lauren grabbed the coffee.
After it hit me, everyone suddenly became interested in calming me down instead of holding her accountable. My stepfather told me Lauren was under enormous stress. My aunt said calling the police would “destroy the family.” Lauren stood beside the sink, breathing hard, almost daring me to react.
I did something none of them expected. I took photographs of my burns, the wet blouse, the broken mug, and the coffee across the floor. Then I opened my phone and wrote down exactly who had been in the kitchen.
I drove myself to urgent care. The burns were painful but fortunately superficial enough to heal without surgery. I requested copies of every medical record and receipt. From the parking lot, I froze my credit with all three bureaus.
Then I changed every password Lauren might know.
That night, I opened my financial files and discovered just how deeply my family depended on me.
For years, I had quietly been the person who fixed problems. My mother’s phone plan was under my account because she received a discount through me. I paid the insurance on a car Lauren drove because she had once promised to reimburse me monthly. I covered a storage unit holding furniture belonging to both of them.
There was more.
My stepfather used an authorized-user card on one of my credit accounts for household emergencies. My mother’s streaming services, roadside assistance, and several recurring utility payments were charged to my card. Nobody had forced me to arrange these things. I had done them gradually because helping seemed easier than arguing.
But helping had become infrastructure.
The morning after the coffee incident, Lauren sent me a text saying I should apologize for “provoking” her. My mother sent another asking me not to create legal trouble over “one terrible moment.”
I saved both messages.
Then I began separating everything.
I removed my stepfather as an authorized user. I transferred my mother’s phone line back to her responsibility after giving her proper notice. I canceled my payment method on the storage unit and sent them the account information so they could take it over.
The car was more complicated because the insurance policy was legally mine. I gave Lauren written notice that coverage would end on the date permitted under the policy terms. She responded with twenty-three messages in one afternoon.
I answered none of them.
Instead, I filed a police report about the coffee incident. I provided photographs, medical documentation, receipts, and the names of everyone who had witnessed it.
Nobody in my family called to ask how my burns were healing.
They called about bills.
My mother wanted to know why her phone payment had increased. My stepfather complained that his card no longer worked at the hardware store. Lauren demanded that I restore her insurance because getting her own policy would cost nearly three times as much.
I kept repeating one sentence by text: “Our finances are now completely separate.”
Two weeks later, I accepted a temporary work assignment in North Carolina. I had already been considering it, but now the timing felt perfect. I packed my car, gave a trusted neighbor my spare key, and left Pennsylvania.
For the first time in years, my monthly expenses dropped dramatically.
Then something unexpected happened.
I received a fraud alert.
Someone had tried to apply for credit using my personal information.
And the application listed Lauren’s address.
I contacted the lender immediately and confirmed that I had not submitted the application. Because my credit was frozen, the account had never opened. I requested written documentation of the attempt and added it to the growing folder on my laptop.
Then I called the police officer handling my earlier report.
I did not accuse Lauren of something I could not prove. I simply provided the information: the address, the date, the lender, and the failed application. The officer told me to preserve everything and file an identity-theft report with the appropriate federal system as well.
After that, my family went quiet.
For nearly a month, nobody contacted me. The silence was strange at first. Then it became peaceful.
I worked, healed, and began noticing how much energy I had previously spent monitoring everyone else’s emergencies. Lauren had trained me to expect a crisis every week: an overdue bill, a broken appliance, a late payment, a mysterious bank fee.
Without access to my money or credit, she had to solve those problems herself.
Six weeks after I left Pennsylvania, my mother sent one message at 2:17 in the morning.
“Please call. Lauren has lost the car, the storage unit is being auctioned, and Dad’s card was declined for the property tax payment. We didn’t understand how much you were covering until you stopped.”
I read it twice.
There was no apology for the coffee. No question about my injuries. But for the first time, someone had finally admitted the truth.
They had not simply been asking me for occasional help.
They had built their financial lives around my ability to rescue them.
I called my mother the next afternoon. She cried and asked whether I could make one payment “just this once” to stop the storage auction.
I said no.
Then I told her something I should have said years earlier: “You need a budget based on your income, not mine.”
Lauren eventually faced consequences beyond losing cheap insurance. The attempted credit application became part of an investigation after the lender provided additional records. I stayed out of the speculation and cooperated only when formally asked for information.
Months later, my mother apologized.
Not perfectly. Not dramatically. But she admitted that everyone had treated my stability as a shared resource while treating my boundaries as selfishness.
I never restored the old financial arrangements.
Lauren and I barely speak now.
My credit remains frozen unless I personally need to unlock it.
And the scar on my shoulder faded faster than the lesson did: sometimes the clearest way to discover whether people value you or merely depend on you is to stop paying for the difference.