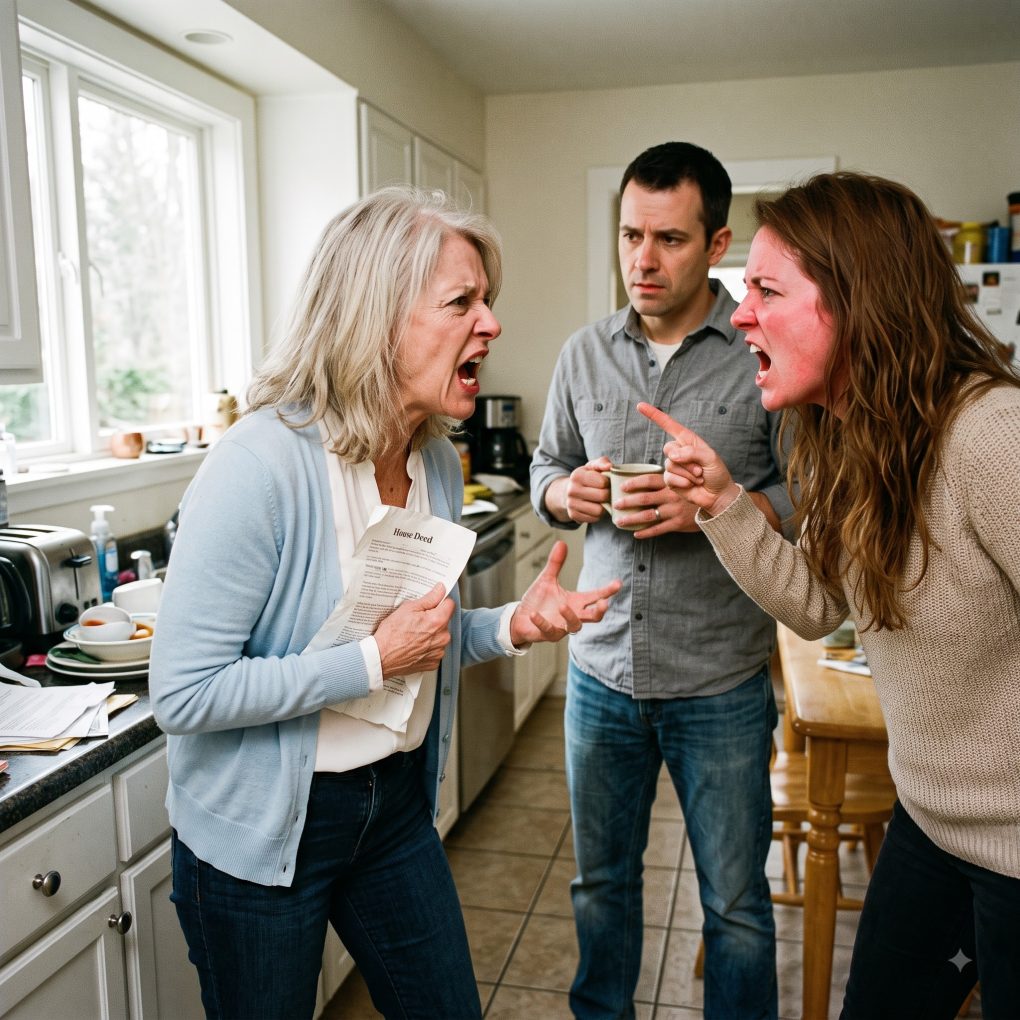
My daughter stood in my own kitchen and said, “You’re lucky we even let you stay here.”
For a second, the only sound was the dishwasher humming behind her.
Rachel folded her arms like she was the one paying the mortgage. Her husband, Derek, leaned against my counter with my favorite blue coffee mug in his hand, wearing that lazy little smirk he’d perfected since moving in six months earlier.
I looked at both of them.
“Excuse me?”
Rachel sighed. “Mom, don’t start. We’re trying to make this work. But you keep acting like this is still completely your house.”
Still.
That word settled something inside me.
I didn’t yell. I didn’t remind her that I’d bought the three-bedroom house outside Columbus after twenty-eight years of working payroll for a trucking company. I didn’t mention that Rachel and Derek had arrived with two suitcases, a maxed-out credit card, and a promise they’d be gone in eight weeks.
Instead, I dried my hands on a dish towel.
Derek took a sip from my mug. “We just need boundaries.”
“Of course,” I said.
His smile widened, because he thought I’d surrendered.
I walked through the mudroom and into the garage.
Behind two plastic Christmas bins and an old folding table was a gray fireproof document box. My late husband, Tom, used to tease me for keeping every important paper in duplicate. That night, I silently thanked him for encouraging the habit.
I opened the box.
There it was.
The warranty deed.
My name. Only my name.
I checked the property tax statement beneath it, then the home-equity paperwork I’d refused to sign three months earlier when Derek had suggested we “unlock some value.”
Everything was exactly where it belonged.
Then I heard voices through the door.
Rachel was whispering, but not quietly enough.
“She’ll calm down. Once the refinance closes, it won’t matter.”
My hand stopped on the folder.
Derek answered, “It matters if she talks to the bank.”
“The appointment is tomorrow.”
“No. It got moved up. Nine a.m.”
I stared at the deed.
Refinance?
There was no refinance.
At least, none I had agreed to.
I slipped the deed into my purse, grabbed the rejected loan packet, and went back inside.
Derek had already rinsed my mug and placed it in the sink.
“How thoughtful,” I said.
Rachel rolled her eyes. “Mom, please.”
I smiled at her. “I’m tired. I’m going to bed.”
Neither of them noticed I took my purse upstairs.
At 4:52 the next morning, I was sitting at the kitchen table with coffee when headlights swept across the front windows.
A black SUV pulled into my driveway.
Derek came downstairs fully dressed.
He froze when he saw me.
Then Rachel appeared behind him, pale and silent.
The doorbell rang.
Derek recovered first. “That’s just someone from the bank.”
“At five in the morning?”
He didn’t answer.
I opened the door.
A man in a charcoal coat held out a business card and looked directly at me.
“Mrs. Bennett? I’m with Franklin County Fraud Investigations. We need to talk about a deed transferring your property yesterday.”
Behind me, Rachel made a sound like she’d forgotten how to breathe.
I thought the forged deed was the worst thing I was going to discover that morning. I was wrong. Someone had been building a paper trail behind my back for months—and when the investigator opened the loan file, even my daughter stopped defending her husband.
I didn’t move from the doorway.
“A deed transferring my property to whom?” I asked.
The investigator, Marcus Hale, glanced past me toward Rachel and Derek.
“To an LLC called D&R Residential Holdings.”
Derek’s face changed.
Not dramatically. Just enough.
The smirk disappeared.
Rachel grabbed the back of a dining chair. “What is that?”
Marcus looked at her. “You tell me.”
Derek stepped forward. “This is ridiculous. We have an attorney.”
“Good,” Marcus said. “You should call them.”
I set my coffee down before my hand could shake.
Marcus explained that the county recorder’s office had flagged the transfer because the notarization number belonged to a notary whose commission had expired months earlier. The signature on the deed was supposed to be mine.
It wasn’t.
Rachel turned toward Derek.
“You said Mom signed everything.”
He stared at her. “Not now.”
My stomach dropped.
Not because Rachel knew nothing.
Because she knew something.
“What exactly did you think I signed?” I asked.
She started crying immediately, which only made me angrier.
“Derek said you agreed to put the house into a family company so we could refinance it and fix our finances.”
“Our finances?”
She looked down.
Marcus asked Derek for identification.
Derek refused.
Then another vehicle rolled into the driveway.
A silver sedan.
A woman stepped out carrying a leather folder.
Derek swore under his breath.
I recognized her.
Three months earlier, she had sat across from me at my kitchen table introducing herself as a “financial restructuring consultant.” Derek had claimed she was helping them consolidate debt.
Her name was Nicole Price.
She walked inside, looked at Derek, and said, “You told me Elaine was already in assisted living.”
The room went silent.
Rachel’s head snapped toward her husband.
I almost laughed, but nothing about it was funny.
Nicole opened her folder. Inside were copies of emails, draft contracts, and a loan application listing my home as an investment property owned by D&R Residential Holdings.
The requested loan amount was $310,000.
I had never seen it.
Marcus pointed to a line on the application.
Primary contact: Derek Collins.
Then another.
Authorized managing member: Rachel Collins.
Rachel backed away. “No. I never signed that.”
Nicole’s expression hardened. “Your electronic signature is on twelve documents.”
Derek suddenly reached for Nicole’s folder.
Marcus blocked him.
“Don’t.”
That single word stopped everyone.
Then Nicole pulled out one final page.
“This is why I came before the closing,” she said. “Something didn’t match.”
She handed it to me.
It was a life-estate affidavit stating I had voluntarily surrendered occupancy because of “progressive cognitive impairment.”
My knees nearly gave out.
They hadn’t just tried to take my house.
Someone had built paperwork saying I was mentally incapable of objecting.
Rachel stared at the page, horrified.
Then she whispered, “Derek… what did you do?”
He looked at her with complete calm.
“What you asked me to do.”
Rachel went white.
Marcus turned to her.
And from upstairs, a phone began ringing.
Not mine.
Not Rachel’s.
Derek looked toward the ceiling.
I knew instantly whose room it was coming from.
My late husband’s locked office.
A room nobody was supposed to have a key to.
Marcus raised one hand.
“Nobody move.”
The phone kept ringing upstairs.
Derek’s eyes stayed fixed on the staircase.
That was enough.
He called another investigator outside, then asked my permission to enter the office. I gave it immediately.
The door was locked, but the spare key was missing from the kitchen drawer. Marcus found it in Derek’s pocket.
Inside Tom’s old desk, beneath tax folders, they found the phone.
And much more.
Copies of my Social Security card. Bank statements. A scanned image of my signature. Password-reset notes. Printed emails between Derek and a man named Calvin Ross, the broker arranging the $310,000 loan.
The phone was registered under a prepaid account.
Its text history told the rest.
For months, Derek had been pretending to be me.
He’d emailed lenders, requested duplicate records, and created a fake explanation for why “Elaine Bennett” could no longer attend meetings in person. The cognitive-impairment affidavit was designed to silence questions if anyone contacted me directly.
But Rachel’s name was there too.
Marcus showed her a message.
Rachel to Derek: “Just get Mom to put the house in both our names. I’m tired of begging.”
Another read: “If she won’t help us willingly, figure something out.”
Rachel covered her mouth.
“I didn’t mean this.”
Derek laughed once.
“You meant whatever fixed the problem.”
That was the ugliest truth.
Rachel hadn’t forged my signature. She hadn’t invented the fake notary or the medical story.
But she had pushed him to get control of my house, knowing I had already said no.
Nicole admitted she became suspicious the previous evening when Derek demanded the loan close before county records updated. She checked the notary credentials, discovered the expired commission, and contacted the recorder’s fraud unit.
The forged deed had been recorded, but the flagged filing had not yet been accepted for the loan.
By noon, the closing was dead.
By evening, Derek was gone under a temporary protection order while investigators referred the fraud case for prosecution.
Rachel remained in my living room beside two packed suitcases.
“Mom, I can explain.”
“You already did.”
“I never wanted you homeless.”
“No,” I said. “You just wanted my home badly enough to stop caring what happened to me.”
I handed her an envelope.
Inside was a thirty-day notice to leave, prepared by an attorney Marcus recommended. Tenant rules still mattered, so I did everything properly.
Rachel stared at it.
“You’re evicting your own daughter?”
“I’m ending your assumption that being my daughter makes you my owner.”
Thirty days later, she left.
Months later, Derek pleaded guilty to multiple fraud-related charges. Rachel cooperated with investigators and avoided charges tied to the forged deed, though the financial damage followed her.
I changed the locks, froze my credit, moved important documents into a bank safe-deposit box, and updated my estate plan.
I kept one thing in the kitchen.
The blue coffee mug.
The next time Rachel visited, nearly a year later, she stood at the front door and waited for me to invite her inside.
That mattered more than any apology.
Family can ask for forgiveness.
But ownership?
Ownership is on the paperwork.