At 6:31 on Christmas evening, my phone lit up with twenty-three missed calls from my husband. The twenty-fourth came while I was staring at the screen. I answered, and Eric did not say hello.
“Where are you? Get here now. Do not call anyone. Just come.”
Behind him, I heard his mother shouting, a man demanding payment, and something glass hitting the floor. Then Eric lowered his voice.
“If you don’t get here before seven, everything is going to fall apart.”
I was sitting alone in a small hotel room forty minutes away, eating takeout noodles in sweatpants. For the first Christmas in nine years, I had not cooked, decorated, booked a photographer, bought gifts for twenty people, or covered the bill when Eric’s family suddenly “forgot” their wallets. More importantly, I had not given anyone permission to use my credit card.
That morning, I had frozen the card they all seemed to treat like a family inheritance.
By 6:32, there had been sixteen declined charges. Catering. Wine. Rentals. A luxury gift basket. A $2,900 electronics purchase. The total was already over $11,000.
Eric’s mother, Diane, called next.
“You have humiliated this family,” she hissed. “The caterer is packing everything up. Your father-in-law’s guests are here. Fix your card.”
“My card is not broken.”
There was silence.
Then I heard Eric’s older brother, Mark, somewhere behind her.
“If she doesn’t sign tonight, we’re screwed.”
Diane immediately hung up.
I stopped breathing.
For three days, that word had been sitting in the back of my mind.
Sign.
On December 22, I had found a bank email in our home printer tray. It was addressed to Eric, but the subject line contained my full name and the words HOME EQUITY APPLICATION. The house was mine. I had bought it four years before I married him. According to the attached summary, someone had applied to borrow $240,000 against it.
The signature on the scanned authorization looked like mine.
It was not mine.
Eric had told me the email was probably spam. Then he accused me of ruining Christmas again, just like I supposedly did every year when I asked why I was paying for everyone.
I had pretended to believe him.
I had not told him I had already called the bank’s fraud department.
Now my phone buzzed with a message from Nora, Mark’s wife.
Do not come to the house.
A second message arrived before I could reply.
They have papers here with your name on them. Eric told everyone you already agreed. There is a notary waiting.
My stomach turned cold.
I called Nora, but she rejected the call. Then she sent a photograph.
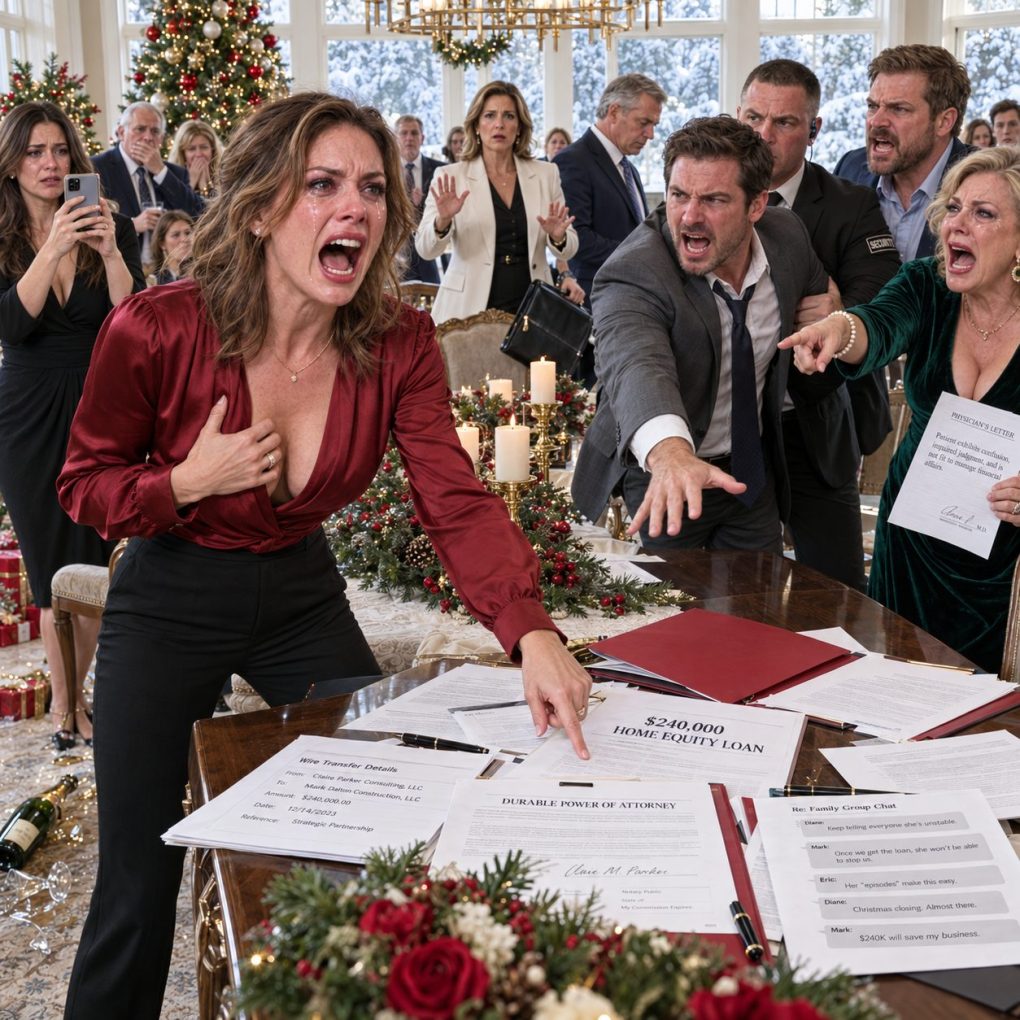
On Diane’s dining table sat a red folder, a bottle of champagne, and a document titled DURABLE POWER OF ATTORNEY. My name appeared on the first page.
Below it was another document showing the $240,000 loan.
I zoomed in until my fingers shook.
The closing deadline printed on the page was 8:00 p.m. that night.
Someone knocked on my hotel door.
Three hard knocks.
Then Eric’s voice came through the wood.
“Claire, open the door. We only need your signature.”
I backed away from the door and called the front desk with one hand while starting an audio recording with the other. Eric knocked again, harder.
“Claire, stop making this dramatic.”
I told the receptionist my husband had tracked me to the hotel and was trying to force me to sign financial documents. She said security was already coming. I also called 911.
The knocking stopped.
For ten seconds, the hallway went silent.
Then Eric said, very calmly, “You are going to destroy my family over a misunderstanding.”
That calm voice frightened me more than the yelling.
I asked how he had found me.
He did not answer.
Instead, a folded sheet of paper slid under the door. It was a copy of the power of attorney Nora had photographed. My supposed signature was already on the last page. The only blank line belonged to the notary.
That was when I understood they did not actually need my signature.
They needed me physically present.
If I appeared at Diane’s house, smiled for photographs, drank champagne, and stood near the notary, they could later claim I had signed willingly and that the earlier electronic documents were legitimate.
My phone vibrated. Nora had sent six screenshots from the family group chat.
Eric: Keep Claire calm tonight.
Diane: She always makes a scene. Get her a drink before Robert arrives.
Mark: Once the loan clears, we can put the money back before she notices.
Then came the message that made my skin crawl.
Eric: If she refuses, we use the other paperwork. Mom already has it.
I asked Nora what “other paperwork” meant.
Before she could answer, someone tried my door handle.
I shouted that police were on the way.
Eric cursed. A second male voice told him to leave. Hotel security had arrived.
Through the peephole, I saw Eric holding a Christmas gift bag and a red folder identical to the one in Nora’s photograph. He smiled at the guard as if he were an embarrassed husband collecting a confused wife.
Then he saw me looking through the peephole.
The smile vanished.
He stepped toward the door and said, “Claire, you have no idea what you’ve done.”
Security ordered him back.
My phone rang again. This time it was Nora.
She was whispering.
“Claire, I found out why they need the money.”
Mark’s construction company was not simply struggling. It had been insolvent for months. Payroll taxes were overdue. Suppliers were threatening lawsuits. Eric had already transferred $78,000 from an account I used for my consulting business into Mark’s company through three smaller transactions.
I nearly dropped the phone.
I had never authorized any transfer.
Nora said Diane knew. Mark knew. Their father knew enough to stop asking questions.
Then she told me the real reason for the Christmas party.
The family had invited a private lender’s representative and a mobile notary as “friends.” They planned to present the loan as a cheerful family investment after dinner. Eric had told them I was a willing partner who became anxious under pressure, which was why the paperwork had been prepared in advance.
But that was not the biggest lie.
Nora sent one final photograph.
It showed another document from the red folder.
A physician’s letter claimed I had recently suffered episodes of confusion and impaired judgment. Attached to it was a petition naming Eric as the person who should temporarily manage my finances.
The doctor’s name belonged to Diane’s cousin.
I stared at the screen, suddenly understanding every accusation that I was “unstable,” “dramatic,” and “forgetful” during the past year.
They had been building a story about me.
Outside my door, the security guard raised his voice.
Eric suddenly lunged past him.
The handle jerked violently.
The door slammed inward against the safety latch.
And Eric shouted, “Give me your phone before you ruin everything.”
What do you think will happen next? I’d love to hear your honest guess or reaction.
The safety latch held for half a second before the hotel security guard drove his shoulder into Eric and pushed him away from my door. I heard both of them hit the hallway wall. Eric swore, the red folder fell open, and papers scattered across the carpet.
I stayed inside.
For years, whenever Eric raised his voice, I had rushed to calm him before anyone else could see. That night I did the opposite. I left the door locked, kept recording, and waited for the police.
Two officers arrived within minutes. By then Eric had stopped fighting the guard and returned to the version of himself strangers usually met. He was composed, apologetic, almost charming. He said his wife was emotional. He said there was a family misunderstanding. He said he had only come to bring me home for Christmas.
Then one of the officers picked up the papers on the floor.
The first page was the loan agreement.
The second was the power of attorney.
The third was the letter describing my supposed mental impairment.
Eric’s expression changed.
I opened the door only after an officer told me it was safe. I handed over my phone and played the recording. I showed them Nora’s photographs, the group messages, the bank email, and the declined charges on my card.
Eric immediately claimed the screenshots were fake.
Then Nora sent me a video.
She had quietly started filming at Diane’s house after our call. The video showed Mark pacing beside the dining table while Diane argued with the mobile notary. The private lender’s representative was packing his briefcase. At one point Mark slapped his palm against the table and shouted that I had “cost them everything.” Then Diane picked up the physician’s letter and told him they could still use “the incapacity route” if Eric got me back before the end of the night.
I watched one of the officers replay that sentence.
Eric stopped talking.
The police did not decide the entire case in a hotel hallway, and I did not expect them to. But they had enough to separate us, document what had happened, and take statements. Because Eric had forced himself against the door after being ordered back by security, the guard also made a report.
When Eric was escorted away from my floor, he looked at me as if I had betrayed him.
That look finally broke something inside me.
Not my heart.
The habit of feeling guilty.
I spent the rest of Christmas night with the chain on the door, lights on, and every financial password I owned spread across a legal pad. I froze my personal credit. I changed banking credentials. I removed Eric from shared devices. I called the emergency number for my business bank and blocked outgoing transfers.
At 1:14 a.m., I discovered how he had found me.
My car still shared its location with the tablet mounted in our kitchen. I had forgotten about it. Eric had used the tablet to track me from our house to the hotel.
I disabled it and took a screenshot first.
The next morning, I met my attorney, Rachel Kim, at her office. She had already spoken with the bank’s fraud team because I had contacted her two days earlier, after finding the home equity application. She told me the single smartest thing I had done was not confront Eric before preserving evidence.
The $240,000 loan had not funded.
My fraud report had triggered a hold before Christmas, but the lender had not yet told Eric because it was reviewing the application. That explained his panic. His family believed the money would be released after the in-person closing. In reality, the transaction was already under scrutiny.
The $78,000 was worse.
Eric had not taken it in one transfer. He had used login credentials I once shared with him when I was recovering from surgery. Over seven months, he moved amounts ranging from $6,000 to $14,500 from my consulting reserve account into an account controlled by Mark’s company. He labeled them with vague descriptions like “vendor deposit” and “tax reserve.”
I had missed them because Eric handled household bookkeeping and regularly sent me spreadsheets showing different numbers.
Those spreadsheets became evidence too.
By December 27, the bank had traced the transfers. By New Year’s Eve, it had identified the account receiving them. Mark tried to say they were legitimate loans from me to his company.
He could not produce one signed loan agreement.
Nora could.
Not a real one.
A draft.
She found it on Mark’s laptop after he left their house. The document described a $100,000 “family bridge loan” from me to his company. My name was typed at the bottom, but the signature line was empty.
In the margin, Mark had written: Get C to sign after dinner.
That one note destroyed the story that I had already agreed.
Nora also explained why she had finally warned me.
Three weeks before Christmas, she had overheard Eric and Diane discussing the power of attorney. At first she believed they were planning some kind of emergency financial arrangement because Mark’s business was failing. Then she saw the physician’s letter.
The letter described symptoms I had never had.
Confusion. Memory loss. Irrational suspicion. Impulsive financial behavior.
The details were written to resemble things Diane had been saying about me for almost a year.
Whenever I questioned a missing receipt, Diane called me obsessive.
Whenever I refused to pay for a family weekend, Eric told people I was becoming paranoid.
Whenever I remembered a conversation differently from him, he said my memory was getting worse.
They had not simply insulted me.
They had been rehearsing a narrative.
The doctor named on the letter, Diane’s cousin Dr. Leonard Price, initially claimed the document was only an unsigned draft prepared at Diane’s request. That explanation collapsed when investigators recovered an email from him attaching the final letter and writing, “Use only if necessary. I do not want my office involved.”
He had never examined me.
He had never spoken to me as a patient.
The letter was later withdrawn, and his professional conduct became a separate matter. I did not need to know every consequence immediately. What mattered was that no one could use that piece of paper to control my finances.
The mobile notary was another surprise.
I had assumed she was part of the scheme. She was not.
Her name was Allison Reed. Diane had told her I wanted to sign several family financial documents after dinner. When Allison arrived and saw that my signature already appeared on the power of attorney, she refused to notarize it without watching me sign a fresh copy and checking my identification.
That refusal was why Eric needed me physically present.
It was also why Diane kept calling.
The lender’s representative had been told a similar story. He believed he was attending a holiday gathering to complete a private business transaction between spouses. When I failed to appear and the bank verification failed, he began asking questions. The family’s entire plan started collapsing in front of their guests.
For years, they had called me difficult whenever I asked for boundaries.
That Christmas, the people they were trying to impress finally saw why I had them.
I filed for divorce in January.
Eric’s first response was not an apology. It was a demand that I stop “criminalizing a family problem.” His attorney later took a more careful position. The bank records, hotel security footage, screenshots, Nora’s video, forged documents, and location tracking made casual explanations difficult.
The civil side moved faster than I expected in some places and slower in others.
My house remained mine.
The home equity loan was canceled.
The fraudulent power of attorney was never validly completed.
My business bank reimbursed part of the unauthorized transfers after its review, while the remaining amount became part of claims against Eric and Mark. We eventually reached a financial settlement that returned most of what had been taken from me, including money Eric had hidden in a separate account.
The criminal investigation did not end with everyone being dragged away in handcuffs on Christmas night. Real life was less theatrical than that.
It was also more satisfying.
Documents had dates.
Servers had logs.
Banks had records.
Phones had messages people thought they had deleted.
Eric eventually admitted, through a negotiated plea, that he had used my credentials to move money without authorization and had submitted financial documents containing a false signature. Mark separately accepted responsibility for receiving funds he knew I had not approved and for his role in preparing the false loan paperwork.
Diane was not charged with every terrible thing she had said or planned. Cruelty is not automatically a crime. But her messages and recorded statements became part of the evidence, and the false physician’s letter could no longer be dismissed as a misunderstanding.
The consequence she hated most was simpler.
People knew.
Relatives who had spent years hearing that I “ruined” holidays learned that I had been paying for most of them.
The Christmas dinners.
The rental houses.
The wine.
The gifts signed from “the whole family.”
Even the expensive watch Diane gave Eric one year had been purchased on a card I paid off.
I found that out while reviewing statements with Rachel.
I laughed when I saw it.
Not because it was funny.
Because after everything else, it was almost absurd.
Nora left Mark that spring.
We did not become instant best friends. She had stayed quiet for too long, and she knew it. But she testified truthfully, gave investigators access to the messages she had saved, and never asked me to pretend her silence had not hurt.
That honesty was enough for me.
Months later, she told me one final detail.
At 6:30 on Christmas evening, just before Eric began calling me in a panic, Diane had stood in the middle of her dining room with twenty-four guests watching as the caterer rolled trays back toward the door.
The family credit cards were maxed out.
The private lender would not proceed.
The notary refused to certify anything.
The bank had placed a hold on the loan.
And the woman they had spent nine years calling selfish was nowhere there to rescue them.
That was the moment they realized I had stopped participating in my own exploitation.
The following Christmas, I did not book a ballroom.
I did not buy twenty gifts.
I did not spend three days cooking food for people who criticized the menu.
I invited six people to my house.
My sister brought dessert. A friend brought wine. Nora came with a small plant and asked before stepping into the kitchen to help.
At 6:30 p.m., my phone was on the counter.
It did not ring once.
For a second, I looked at the clock and remembered the hotel room, Eric’s fist against the door, the red folder sliding across the carpet, and the sick feeling of realizing that people I had trusted were preparing to use my own name against me.
Then my sister asked me to taste the potatoes.
I did.
They needed salt.
No one called me difficult.
No one told me I had ruined Christmas.
We ate late, laughed too loudly, and left the dishes until morning.
For years, I thought keeping the peace meant paying whatever it cost.
I finally learned the difference between peace and surrender.
And for the first time in a very long time, Christmas cost me exactly what I chose to give.