“We’re co-owners here,” my sister Taryn announced at the closing table, according to the affidavit I received six months later. She had said it with enough confidence that nobody stopped her. The problem was simple: she had never owned one square foot of my land.
The property was sixty-two acres outside Bend, Oregon, inherited from my grandfather before I married or started my business. The deed had been recorded solely in my name for nine years. But Taryn and my parents wanted financing to convert an old barn near the highway into an event venue, and the lender required substantial equity.
Apparently, my land became their solution.
They presented the property as family-owned acreage and claimed Taryn held a fifty-percent interest. That supposed equity helped support a $325,000 loan at closing. By the time I discovered it, almost every dollar had been spent—contractors, landscaping, a commercial kitchen, furniture, marketing, and nearly $28,000 toward my parents’ personal debts.
I found out on a Monday at 9:06 a.m. when a state building inspector named Owen Hadley called me. “Ms. Marlowe, I’m reviewing the occupancy application for Juniper Ridge Events. Your name appears on the county ownership record, but the financing packet identifies another owner.”
My stomach tightened. “What other owner?”
“Taryn Marlowe.”
I stopped walking.
Twenty minutes later, Owen emailed me the page. Taryn’s signature sat beneath the words CO-OWNER/AUTHORIZED LANDHOLDER. Below it was an owner-consent form supposedly permitting improvements and liens against the property.
The signature beside my printed name was not mine.
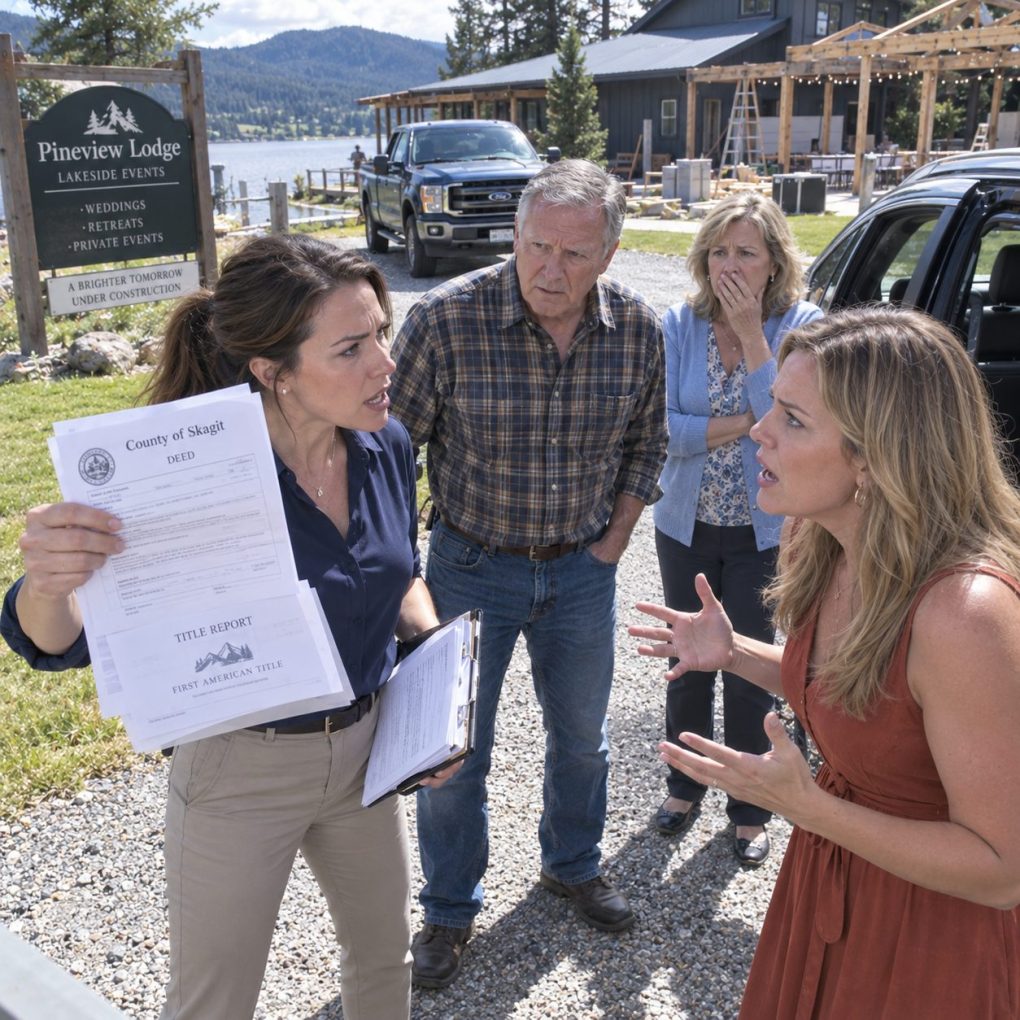
I called the Deschutes County recorder, ordered certified copies of the deed, then paid for a current title report. Both showed exactly what I already knew: Elise Marlowe, sole owner. No Taryn. No parents. No shared ownership.
At 2:41 p.m., I emailed those verified records to Owen and copied the lender’s compliance department. My message contained only three sentences: “I am the sole recorded owner. I did not authorize my sister to represent herself as co-owner. I did not sign the attached consent.”
At 4:17, Taryn called screaming. “What did you send them?”
“The deed.”
“You’re going to destroy everything!”
Behind her, I heard Mom crying and Dad saying my name like a warning.
Then another call came through.
It was the lender’s legal department.
The attorney introduced herself as Dana Rourke and spoke with terrifying calm.
“Ms. Marlowe, please do not sign anything your family sends you tonight. We have frozen the remaining loan activity and opened a title-and-fraud review.”
For the first time, Taryn stopped yelling.
The next morning, my parents arrived at my house before eight.
Dad placed a folder on my kitchen counter. “Just sign this and confirm Taryn had permission.”
I did not open it.
Mom whispered, “The money’s already gone, Elise. What good does ruining your sister do now?”
That sentence hurt more than I expected. They still saw the problem as my reaction, not what had been done in my name.
I asked one question. “Did you know she claimed to own my land?”
Dad stared at the floor.
That was my answer.
The lender’s investigation moved quickly. The closing company had relied on a family-prepared ownership affidavit instead of resolving the conflict with the county deed before funding. The title file also contained my supposed consent bearing an electronic signature tied to an email address I had never used.
Dana’s legal team demanded contractor invoices, bank statements, closing communications, and the original electronic-signature records. The lender also suspended any attempt to place a lien on my acreage while its counsel reviewed whether the loan documents were enforceable against the property.
Taryn called again that evening.
“We thought Grandpa meant the land for all of us.”
“He deeded it to me.”
“You never used it.”
“That doesn’t make it yours.”
She started crying. “We can’t repay $325,000.”
For a moment, I saw my little sister at seventeen, not the woman who had signed my name into a financing package.
But sympathy did not change the records.
I hired attorney Nadine Foster, who sent formal notice that I had never pledged the property or authorized anyone to act for me. She also instructed the family not to contact county offices pretending to represent my interests.
The state inspector postponed final occupancy approval for the venue—not as punishment, but because ownership authorization for several site improvements had to be corrected.
My parents blamed me publicly.
Taryn blamed the lender.
But three weeks later, the lender’s forensic review found the timestamped document trail.
The false ownership statement had not been a misunderstanding.
It had been created the night before closing.
From Taryn’s laptop.
The lender could have pursued the hardest possible path immediately, but Dana told everyone during mediation that their first priority was protecting the innocent property owner and recovering the loan without creating unnecessary damage.
That distinction mattered.
My land was released from the disputed collateral claim once the title analysis confirmed I had never executed a valid mortgage or security agreement. The lender preserved its claims against the people and entities that had actually signed the financing documents.
Taryn’s event company still owed the money.
My parents had personally guaranteed part of it.
And the closing company faced its own review over why obvious discrepancies between the affidavit and public land records had not been resolved before funding.
There were consequences, but not the dramatic kind my relatives predicted.
Nobody arrived in handcuffs at Thanksgiving.
Nobody lost everything overnight.
Instead, there were months of statements, lawyers, amended documents, repayment negotiations, and painfully detailed accounting.
The worst moment came during mediation when Dana displayed where the $325,000 had gone. Most of it had genuinely funded the venue. But the $28,000 used for my parents’ credit cards and an additional $17,500 Taryn had transferred into her personal account changed the room.
Taryn stared at the transaction list.
Mom covered her mouth.
Dad finally said, “We told ourselves we’d replace it after opening.”
I looked at him. “With money earned on property you told the bank belonged to Taryn?”
He had no answer.
Taryn eventually admitted that she had been terrified the lender would reject the project. She had convinced herself that because Grandpa had loved all of us, claiming part of my acreage was only “borrowing family equity.”
“That’s how I made it sound in my head,” she said. “Like I wasn’t taking anything from you.”
“But you were risking the land.”
“I know.”
It was the first time she said those words without adding “but.”
The final agreement required Taryn’s company to sell several expensive event fixtures, contribute all available business cash, and refinance the remaining balance against assets it actually owned. My parents entered a structured repayment plan for the money used personally. Taryn also surrendered control of the company to an independent manager while the lender monitored repayment.
The venue eventually opened eleven months late.
I did not invest in it.
I did not become a partner.
And I never transferred any part of my land to my family.
What I did agree to was an easement allowing customers to use an existing access road, but only after my attorney drafted it properly, the venue paid fair value, and every signature was legitimate.
That surprised Taryn.
“After everything, you’re still letting us use the road?”
“I’m allowing a legal agreement,” I said. “That’s different from pretending what’s mine belongs to everyone.”
Two years later, Juniper Ridge Events was smaller than my family had dreamed but finally profitable. My parents had repaid their personal portion. Taryn was still making payments, and our relationship had become careful rather than close.
One autumn afternoon, she came to the acreage while I was repairing a fence.
She handed me a small envelope.
Inside was a certified copy of the original deed.
“I ordered it for myself,” she said. “I wanted something I couldn’t reinterpret.”
I looked at her.
She swallowed. “Grandpa gave this land to you. I should have respected that before a lender had to teach me.”
I put the deed back into the envelope and handed it to her.
“Keep it.”
She did.
People sometimes think family loyalty means sharing everything without limits. I learned the opposite. Healthy families survive because some lines are clear enough that nobody has to guess where love ends and ownership begins.
I did not save my family by pretending the fraud never happened.
I saved what was left of us by finally insisting that the truth be recorded correctly.